Annuities: What You Need to Know Before Investing Your Money
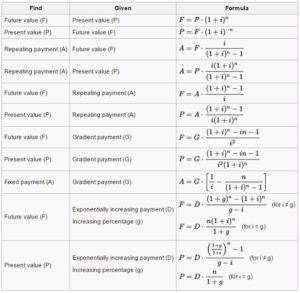
An annuity is a contract between an individual and an insurance company. The main purpose of the agreement is to provide income to the policyholder or their beneficiaries in exchange for regular payments made during a specific period or until death. Annuities are often used as a retirement income stream, but they can also be purchased with lump-sum payments.
Types of Annuities
There are different types of annuities available, each designed for specific needs and objectives:
1) Fixed Annuity – This type of annuity provides guaranteed interest rates on your investment amount over time. It offers a fixed return which makes it less risky than other forms of investments like stocks and mutual funds.
2) Variable Annuity – In this category, the rate of return depends on how well the underlying investments perform. This means that while you have more control over your investment portfolio than with fixed annuities, there is also more risk involved.
3) Indexed Annuity – These are similar to variable annuities except that they offer returns based on stock market indexes such as the S&P 500 rather than directly investing in stocks themselves.
4) Immediate Annuity – This type of annuity guarantees immediate payments once purchased. It’s ideal for people who need lifetime income immediately after retirement or those who want to transfer their assets into guaranteed lifetime income streams without worrying about fluctuations in interest rates or market conditions.
Benefits of Owning an Annuity
One major advantage of owning an annuity is its tax-deferred growth potential. With traditional savings accounts and CDs, you pay taxes annually on any earned interest; however, with most types of annuities, you don’t pay taxes until you start receiving payouts from your account after age 59 1/2 (or if certain circumstances apply). Additionally, because these products are issued by insurance companies and regulated by state authorities to protect consumers’ interests at all times, they are considered very safe investment vehicles.
Another benefit of annuities is that they offer a guaranteed income stream, which can be especially important for retirees who no longer have a steady source of income from their job. This guaranteed income can help ensure that your basic living expenses are covered each month and provide peace of mind throughout retirement.
How to Purchase an Annuity
To purchase an annuity, you’ll need to find a reliable insurance company and decide what type of annuity best suits your needs. You should also consider factors like payout rates, fees, surrender charges, and the financial strength rating of the insurer before making any final decisions. Once you’ve chosen an annuity provider and product, you’ll typically undergo underwriting–a process during which the insurer will evaluate your health status or other relevant information to determine how much it will charge in premiums and what benefits will be available after purchasing this policy.
It’s essential to work with a knowledgeable financial advisor who can guide you through the process so that you make informed choices about your financial future. They can help assess whether an annuity is right for your situation and recommend specific products based on your personal goals and circumstances.
Risks Associated with Annuities
Although there may be many benefits to owning an annuity, there are also some risks involved. One significant risk is inflation; if prices rise faster than anticipated over time (e.g., healthcare costs), it might reduce the purchasing power of fixed payments received over extended periods.
Another possible issue worth considering is liquidity: once funds have been invested into certain types of contracts like deferred variable ones with high surrender charges or multi-year guarantee lengths where early withdrawals could trigger penalties-this money cannot easily be accessed without paying expensive fees or facing substantial losses from selling these policies prematurely (i.e., “surrendering” them).
Furthermore, while it’s true that most annuities offer guarantees against market downturns or other significant losses, these products are not risk-free. Annuities may expose you to certain risks that you might not otherwise encounter with other types of investments. For example, if an insurer goes bankrupt or defaults on its obligations to policyholders (e.g., paying promised benefits), investors could lose some or all of their principal.
Conclusion
An annuity is a financial product that offers a guaranteed income stream for life or over a period of time. It can be purchased in different forms depending on the investor’s needs and objectives. While there are many benefits associated with owning an annuity, it’s essential to understand the potential drawbacks before investing your money into one.
To make sure you’re making informed decisions about your financial future, consult with a qualified financial advisor who specializes in retirement planning and has extensive experience working with annuities. They will help you evaluate different options based on your unique circumstances and goals so that you can achieve long-term success through sound investment strategies tailored specifically for you!