Unlocking the Flexibility of Credit Lines: Everything You Need to Know
Credit Lines: What You Need to Know
Credit lines are a type of credit that allows you to borrow money up to a certain limit. They are a popular form of credit for both individuals and businesses due to their flexibility and ease of use. In this post, we will answer some commonly asked questions about credit lines, including what they are, how they work, and how to get one.
What is a Credit Line?
A credit line is a pre-approved amount of money that you can borrow as needed, up to your approved limit. It works similarly to a credit card in that you have access to funds whenever you need them, but instead of making purchases with the card directly, you withdraw cash or make payments from your account.
How Does a Credit Line Work?
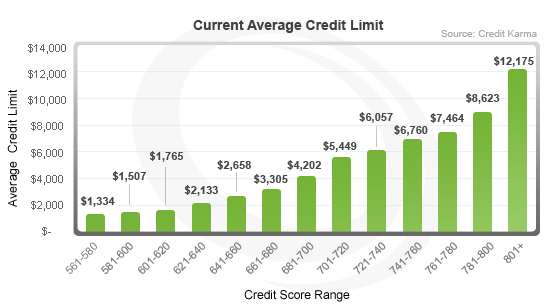
When you apply for a credit line, the lender will determine your maximum borrowing limit based on factors such as your income, credit score, and financial history. Once approved for the line of credit, you can draw down funds up to this limit at any time without needing further approval from the lender.
The repayment terms for a credit line vary depending on the lender’s policy. Some lenders may require monthly payments or minimum balances while others allow interest-only payments until the end of the term when all borrowed amounts must be repaid in full.
Interest rates on credit lines also vary depending on several factors such as your current financial situation (credit score and debt-to-income ratio) and market conditions. Generally speaking though interest rates tend to be lower than those offered by traditional loans because lenders know there is less risk involved with unsecured revolving debt like this which means it has more flexibility with repayments than other types of financing options available.
How Do I Get Approved For A Credit Line?
To qualify for most types of personal or business-related credit lines requires good personal finances (including good past payment history), stable employment history or business growth trend. Your personal or business assets may also be considered as collateral to guarantee the loan.
Before you apply for a credit line, it’s important to know your credit score and history. This information can help you determine if you’re likely to be approved for a credit line and what interest rate you may qualify for.
To improve your chances of getting approved, work on improving your credit score. You should also gather all necessary documentation such as proof of income, tax returns, bank statements or financial reports (for businesses) before applying.
Once you have applied for a credit line, the lender will review your application and make a decision based on their lending criteria. If approved, they will notify you of the maximum amount that they are willing to lend out at any given time.
Are There Different Types Of Credit Lines?
Credit lines come in different types depending on who is offering them and how they are used:
Personal Credit Line: Personal lines of credit are usually unsecured which means that no collateral is required when borrowing money from this type of account. These types of accounts are often used by individuals who need extra cash during emergencies or unexpected expenses like home repairs or medical bills.
Business Credit Line: Business lines of credit offer more flexible funding options than traditional loans with better rates because lenders understand there’s less risk involved with revolving debt financing compared to other forms such as term loans or SBA loans etc.. They can be used to finance operations such as inventory purchases, equipment upgrades or expansion projects among others.
Secured Credit Line: A secured line requires collateral like real estate property or vehicle against which funds can be borrowed from an account secured by these assets making it easier for borrowers who don’t qualify due low personal finances but have valuable assets available instead; these types typically carry lower interest rates than unsecured ones since there’s less risk involved in lending against collaterals offered by borrowers.
Home Equity Line Of Credit (HELOC): HELOCs allow homeowners to borrow against the equity in their homes. These types of credit lines are popular among homeowners because they offer low-interest rates and flexible repayment terms.
How Can I Use My Credit Line?
Once approved for a line of credit, you can use the funds as needed up to your maximum limit. This means that if you only need to borrow $1,000 one month, you can do so without having to take out the full amount at once. You will only be charged interest on the amount borrowed from the line of credit.
Credit lines can be used for any number of purposes such as emergency expenses, home repairs or renovations, debt consolidation or even business expansion projects.
What Are The Advantages Of A Credit Line?
There are several advantages to using a credit line:
Flexibility: Because you only draw down what is needed when it’s actually required rather than taking lump sum loans upfront which marks higher monthly repayments regardless; this saves money in terms of interest payments over time since less money would have been borrowed overall.
Lower Interest Rates: Generally speaking, interest rates on credit lines tend to be lower than those offered by traditional loans because lenders know there is less risk involved with unsecured revolving debt like this compared with other forms such as secured loan options available elsewhere (e.g., home equity loans).
Ease Of Access: Once approved for a credit line account – borrowers can access funds immediately after drawing them down whenever necessary rather than going through an approval process every time they need money urgently making it easier and more convenient for daily expenses too!
What Are The Disadvantages Of A Credit Line?
There are also some disadvantages associated with using a credit line:
Interest Costs: As mentioned earlier – although these types typically carry lower rates compared with other financing options due reduced risks involved but still borrowing costs could add up quickly if not managed carefully especially if minimum payment amounts aren’t kept up-to-date since this increases total balance owed over time resulting in more accrued interest charges over long periods of time.
Potential For Overspending: This type of account can be tempting to use for non-essential purchases or expenses which means it’s important to have a budget plan in place before using one because the more you borrow, the higher your interest rate will be and it could end up costing more than originally anticipated if not managed responsibly.
Risk Of Defaulting: If you fail to repay the borrowed funds within terms set, your credit score will suffer making it difficult to get approved for future financing options. It’s crucial that borrowers stay on top of their payments and avoid taking out more money than they can afford or pay back completely.
In Conclusion
Credit lines are a flexible and convenient form of borrowing that can be used for a variety of purposes. They offer lower interest rates compared with other forms such as secured loans and give borrowers access to funds when needed without having to go through an approval process every time they require cash immediately. However, like all financial products, there are risks involved too so borrowers should take care to manage their accounts responsibly by keeping minimum payment amounts up-to-date while avoiding overspending habits whenever possible!