FDIC Insurance: Protecting Depositors and Promoting Stability in the Banking System
The Federal Deposit Insurance Corporation (FDIC) was established in 1933 during the Great Depression to protect depositors from bank failures. Since then, it has become a critical component of our banking system and provides peace of mind to millions of Americans.
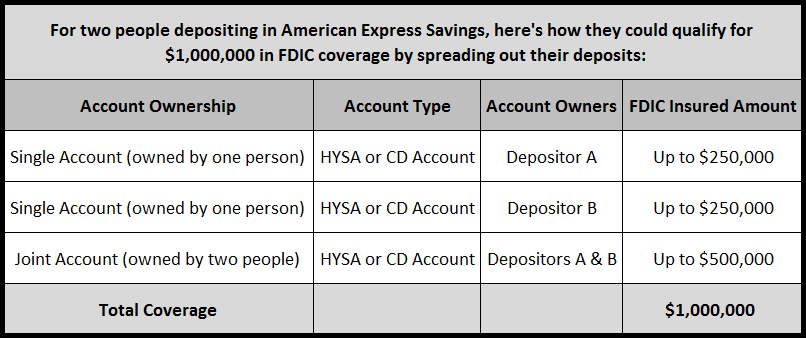
The FDIC is an independent agency of the federal government that insures deposits at banks and savings associations. This insurance covers deposits up to $250,000 per depositor, per insured bank or savings association. The coverage limit applies to all account types, including checking accounts, savings accounts, money market deposit accounts (MMDAs), and certificates of deposit (CDs).
One important thing to note is that not all financial institutions are FDIC-insured. Credit unions are insured by a different organization called the National Credit Union Administration (NCUA). It’s essential to make sure that any financial institution you use is federally insured so that your deposits are protected.
If a bank or savings association fails, the FDIC steps in as receiver and takes over its operations. The goal is for customers to have uninterrupted access to their funds while the failed institution’s assets are liquidated. In most cases, this process takes only a few days before customers can access their money again.
It’s worth noting that there have been very few instances where depositors lost money because of an FDIC-insured bank failure since its inception in 1933. The last significant wave of bank closures occurred in the late 1980s and early 1990s during the Savings and Loan Crisis.
FDIC insurance not only protects individuals’ deposits but also promotes stability in our banking system as a whole. It reduces fear among consumers about putting their money into banks which makes them more likely to save instead of hold onto cash under mattresses or other unsafe places.
Another benefit provided by the FDIC is education on financial literacy through their Money Smart program designed for adults and young people alike. They offer free resources that cover topics such as budgeting, saving, credit management, and more. The program is available online or in-person through various community organizations.
It’s important to remember that FDIC insurance only covers deposits at a bank or savings association. Investments made through brokerage firms or other types of financial institutions are not covered by FDIC insurance but may be insured by the Securities Investor Protection Corporation (SIPC) up to $500,000 per account type.
While it’s unlikely for a depositor to lose their money due to an FDIC-insured bank failure, it’s still possible. For depositors with over $250,000 in one institution, there are ways to increase coverage beyond this limit. One option is to open accounts at different banks or savings associations so that each account is under the $250k limit.
Another option is using CDARS (Certificate of Deposit Account Registry Service), which allows depositors to have all their funds placed into CDs with varying maturities while still maintaining full FDIC insurance coverage on all funds deposited.
Finally, some banks offer “brokered” deposits where a broker places your money into several different banks for you so you can stay under the $250k limit while earning higher interest rates than most traditional bank products offer.
In conclusion, FDIC insurance has been a vital component of our banking system since its establishment in 1933. It provides confidence and peace of mind for depositors knowing their money is protected up to $250k per institution. While it’s rare for an FDIC-insured bank failure to happen these days, it’s still important always to double-check any financial institution you use ensures federal protection before opening an account there. Additionally try utilizing resources offered by the Money Smart program and considering alternative options if you have more than $250k deposited at one institution.