Short Sale 101: A Viable Option for Struggling Homeowners?
Short Sale 101: What You Need to Know
If you’re looking for a way out of your mortgage but don’t want to go through foreclosure, a short sale might be an option. A short sale is when the lender agrees to accept less than the full amount owed on the mortgage loan. In this article, we’ll go over some of the basics of short sales and what you need to know if you’re considering one.
What is a Short Sale?
A short sale occurs when a homeowner sells their property for less than what they owe on their mortgage(s). The lender accepts a lower payoff amount so that the homeowner can sell the property and avoid foreclosure. It’s important to note that not all lenders will agree to a short sale, and there are certain eligibility requirements that must be met.
Why Would Someone Choose a Short Sale?
There are several reasons why someone may choose a short sale instead of going through foreclosure. Some of these include:
– Avoiding foreclosure: A short sale allows homeowners to sell their property and avoid having their home foreclosed on.
– Credit impact: While both options will hurt your credit score, going through a short sale typically has less of an impact than foreclosure.
– Moving forward with life: By avoiding foreclosure or bankruptcy, homeowners can move forward with their lives without as much financial burden.
How Does it Work?
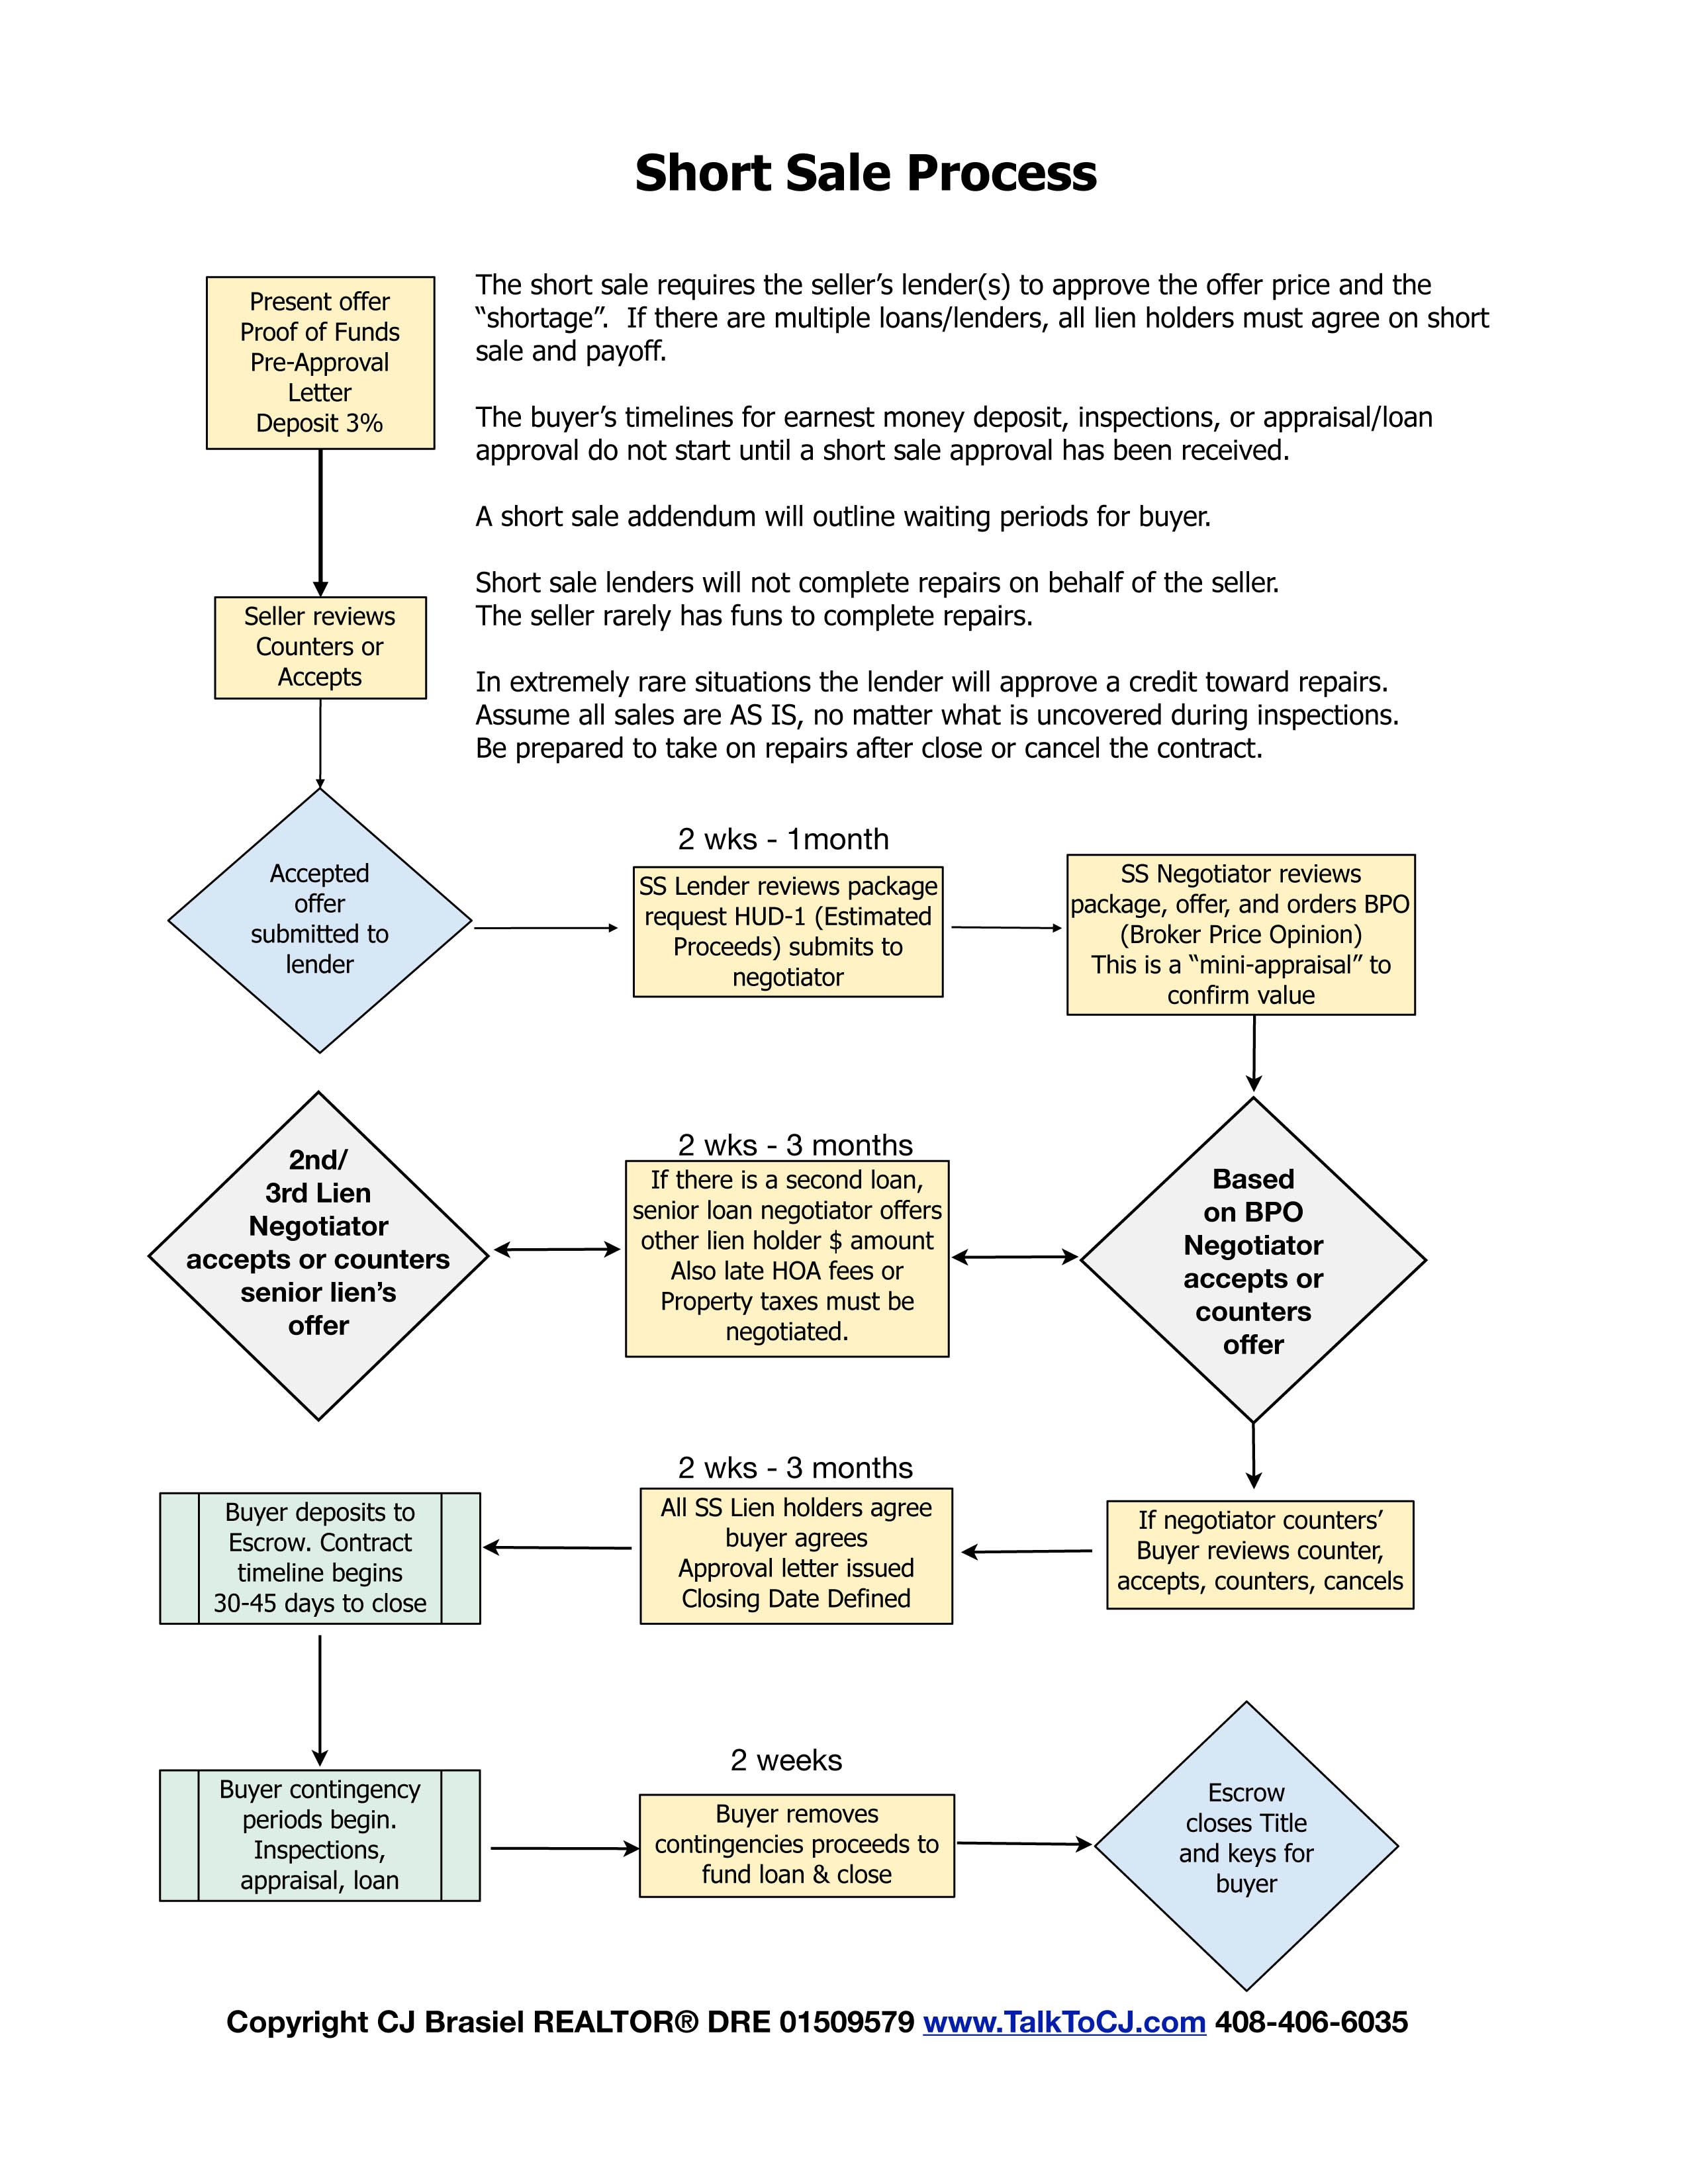
The first step in pursuing a short sale is contacting your lender or loan servicer. They will provide you with information about eligibility requirements and what documentation they’ll need from you. From there, it’s up to you (or your agent) to find a buyer for your home who is willing to pay at least close to market value.
Once you have an offer from a potential buyer, it must be submitted along with other required documents (such as proof of income) for approval by your lender/servicer. If approved, closing can take place within two months (although it can take longer).
It’s important to note that not all short sales are approved, and the process can be time-consuming. Additionally, there may be tax implications depending on your situation.
Conclusion
While a short sale can be a viable option for those struggling with their mortgage payments, it’s important to understand the process and requirements before pursuing one. It’s also worth noting that a short sale is not necessarily the best option for everyone – consulting with a financial advisor or housing counselor may help you make an informed decision about what path is right for you.