The Fascinating History and Impact of Interest Rates on Personal Finance
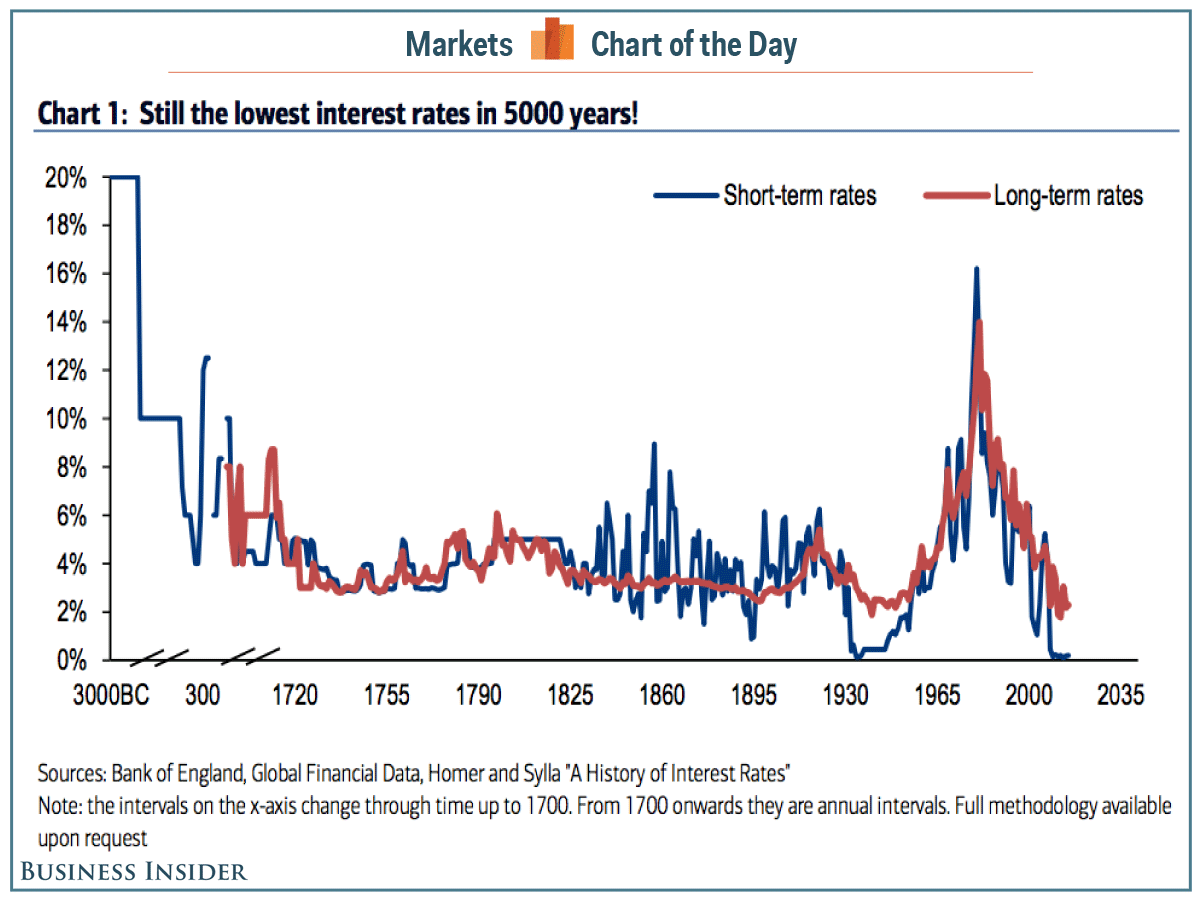
Interest rates are a key component of the modern economy, and they have been for centuries. From the earliest days of banking to the present day, interest rates have played a major role in shaping financial markets and influencing economic growth. In this retrospective article, we will explore the history of interest rates and their impact on personal finance.
The concept of interest dates back to ancient times when loans were made between individuals or groups. Interest was charged to compensate lenders for the risk they took by lending money, as well as for foregoing other opportunities that could have generated income. Interest rates were typically agreed upon based on market conditions, with lenders seeking higher rates during periods of high demand or low supply.
Over time, banks emerged as intermediaries between borrowers and lenders, offering a range of financial products such as savings accounts, certificates of deposit (CDs), mortgages and personal loans. Banks earn money by charging interest on these products at a rate higher than what they pay out in deposits.
Interest rates became more standardized over time with governments regulating them through central banks or other monetary authorities. The first central bank was established in Sweden in 1668 followed by England’s Bank of England in 1694 which used its power to regulate interest rates among other functions.
Initially set up to help fund government debt and regulate currency exchange rates during wartime and emergencies like financial crises; these institutions soon began playing an integral role beyond just issuing currency notes but also managing credit flows within economies around the world.
In recent years, most countries moved towards floating exchange rate systems where currencies’ values fluctuate based on market forces rather than being pegged against each other under fixed systems like gold standards which prevailed till early 20th century until abolished after WWI due to inflationary pressures caused by war efforts taking away resources that would otherwise be used for productive purposes leading into hyperinflation across Europe including Germany.
The global economic recession triggered by subprime mortgage crisis in US housing market in 2008 resulted in a global financial crisis that prompted central banks to cut interest rates to stimulate the economy. These low-interest rate policies, known as quantitative easing or “QE,” provided cheap credit and liquidity for banks to lend out at lower borrowing costs.
In turn, these actions have led to an increase in consumer spending which has helped boost economic growth. However, this also led to increased debt levels among individuals and governments alike who took advantage of the low-cost borrowing environment.
Interest rates continue to fluctuate depending on various factors such as inflation, market demand for credit and government policy decisions. When inflation is high, central banks usually increase interest rates to curb spending; however when it’s too low they may reduce them again as seen during COVID-19 pandemic where many countries slashed their benchmark interest rates near zero or even negative territory making borrowing cheaper than ever before.
For personal finance purposes, interest rates play a critical role in determining how much you pay for loans or earn from savings accounts. For example, if you take out a mortgage at a higher rate than what you can afford then your monthly payments will be more significant; conversely if you invest money into savings accounts with higher yields then over time your returns on investment may compound faster leading into significant wealth accumulation over time.
When it comes to managing personal finances effectively, keeping track of changing interest rates is crucial. You should regularly review your investments and loans against current market conditions while considering future trends and forecasts – so that you can make informed decisions about when best is the right time either buy assets like property or stocks when prices are low compared against historic averages thus increasing chances for long-term gains; alternatively refinancing existing debts like loans or mortgages at lower repayment terms saving potentially thousands of dollars per year until paid off completely avoiding additional fees associated with early repayments.
In conclusion, understanding how changes in interest rates affect personal finance is essential for anyone looking to manage their money effectively. From the earliest days of banking to the present day, interest rates have played a major role in shaping financial markets and influencing economic growth. Whether you are taking out a loan or investing in stocks, keeping track of changes in interest rates can help you make informed decisions about your money and maximize your returns over time.