The Importance of Your Down Payment When Buying a Home or Property
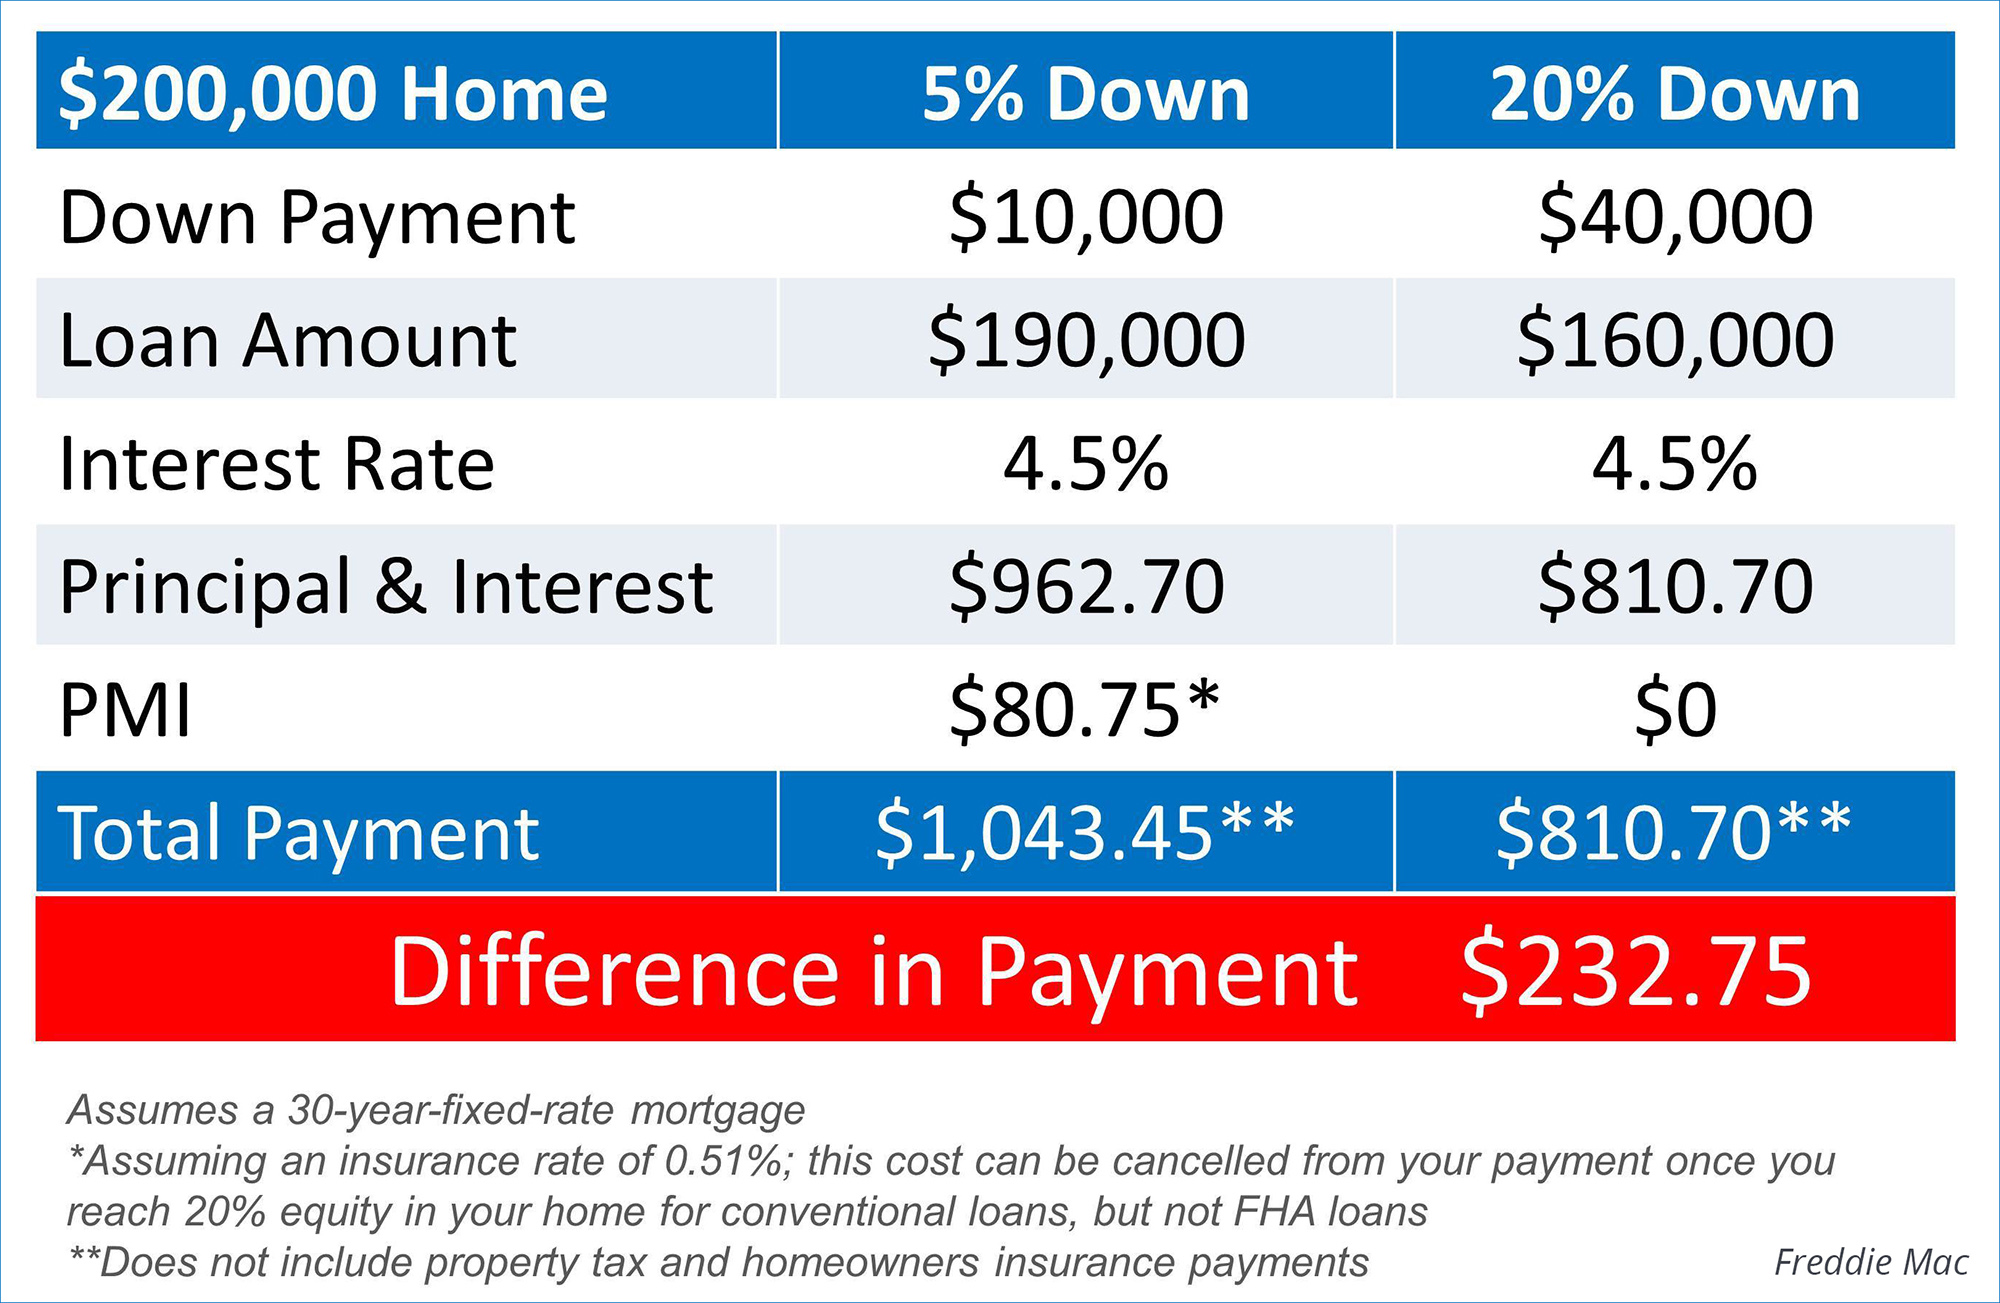
Are you in the market to buy a new home or property? If so, one of the most important factors to consider is your down payment. A down payment is the amount of money you pay upfront when purchasing a home or property. The size of your down payment can impact several aspects of your mortgage, including interest rates and monthly payments.
In this article, we’ll take a closer look at what a down payment is and explore some common requirements that lenders may impose.
What Is a Down Payment?
A down payment is an initial sum paid by a buyer as part of their purchase agreement. This amount is usually expressed as a percentage of the total price being financed. For example, if you’re purchasing a $300,000 home and are required to make a 20% down payment, you would be expected to pay $60,000 upfront.
Why Do You Need One?
A down payment serves two primary purposes:
1) It reduces the lender’s risk: When you put money into your own purchase up front, it demonstrates that you have some skin in the game. You’re less likely to walk away from your investment if it means losing that much cash.
2) It reduces overall borrowing costs: By putting more money toward your purchase initially, less financing will be needed over time—resulting in lower interest rates and fewer fees across the life of your loan.
How Much Should Your Down Payment Be?
The amount required for a down payment varies depending on several factors such as credit score and loan type. However, there are some general rules regarding how much should be put towards this expense:
– Conventional loans typically require at least 5% – 20% (depending on creditworthiness)
– FHA loans usually require around 3%-4%
– VA loans often offer no-down-payment options
It’s worth noting that while smaller amounts may seem appealing because they’re easier to come up with initially—they can end up costing you more over the long term. By putting down a larger initial payment, you’ll save on interest and fees in the long run.
What Are Some Down Payment Requirements?
Lenders may have several requirements for borrowers before lending them money:
1) Credit score: A higher credit score is generally required to qualify for lower rates and better terms. For example, if your credit score is 700 or above, you might be able to get approved for a loan with a lower down payment requirement than someone whose credit score is below 600.
2) Debt-to-income ratio: Lenders will often look at how much debt you already have compared to your income when deciding whether they can lend to you. Ideally, this ratio should be less than 36%.
3) Employment history: To help demonstrate that you’re capable of making regular payments on time, lenders may want to see proof of steady employment or income.
4) Appraisal value: Before approving any loan amount, lenders will conduct an appraisal of the property being purchased. This helps them determine its true value so that they can offer an appropriate loan amount based on their risk tolerance.
5) Cash reserves: While not always required upfront—some lenders may require proof that applicants have enough cash available (in savings accounts or otherwise) as backup funds in case of emergencies.
Conclusion
When it comes to buying a home or property there are many considerations involved; however, one important factor stands out among all others – the down payment. By knowing what’s expected and understanding how it impacts mortgage agreements – buyers can make informed decisions about how much should be put towards this expense initially which ultimately translates into lower borrowing costs over time. Whether opting for conventional loans with high requirements or VA Loans with no-down-payment options – it pays off well in the end by weighing risks against rewards!