Demystifying Car Loan Amortization: Understanding How it Works
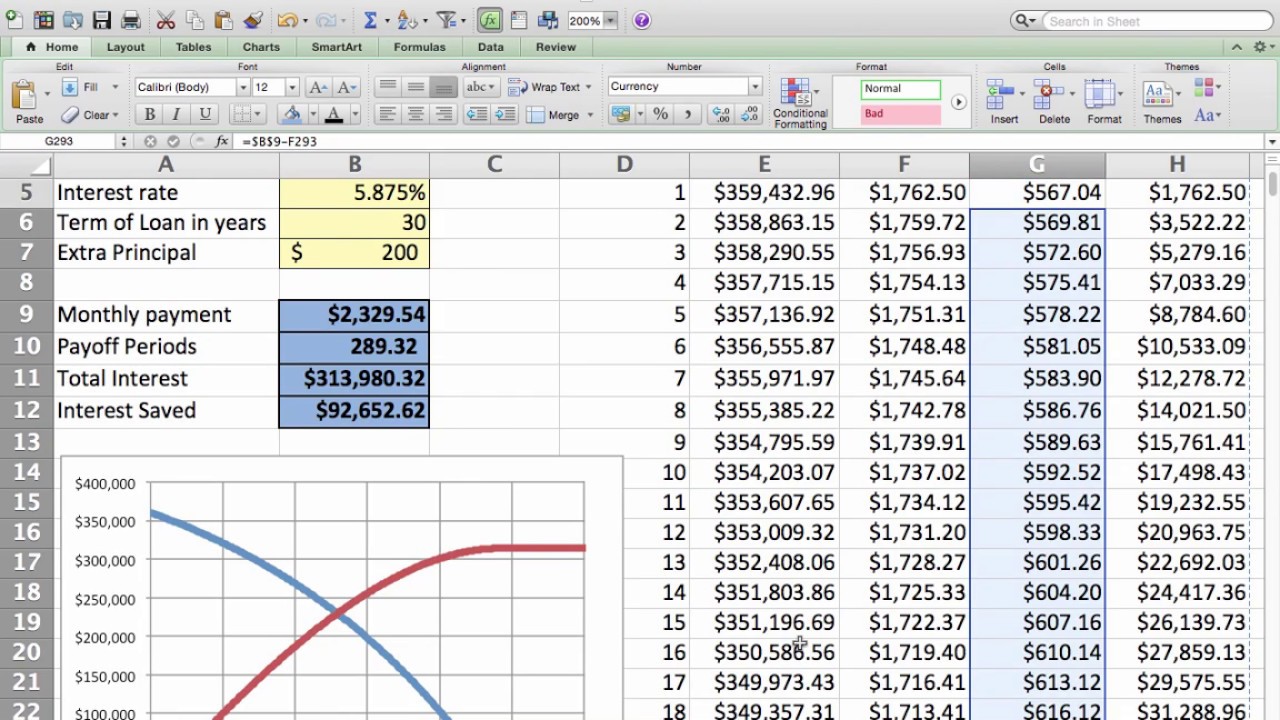
Car Loan Amortization: Understanding How it Works
When you’re considering purchasing a car, one of the things you’ll need to think about is financing. For many people, this means taking out a loan. Car loans are an excellent way to purchase a vehicle that you can’t afford to pay for upfront.
However, when taking out a car loan, it’s essential to understand how car loan amortization works. In this post, we’ll go over everything you need to know about car loan amortization and how it affects your monthly payments.
What is Car Loan Amortization?
Amortization refers to the process of paying off debt over time through regular payments that cover both principal and interest. When you take out a car loan, your payments will be calculated based on the amount borrowed and the interest rate applied.
The goal of amortizing a car loan is to make sure that each payment covers both principal and interest while also ensuring that the total cost of borrowing is spread out evenly over time.
How Does Car Loan Amortization Work?
Car loans are typically structured as installment loans with fixed monthly payments. The amount you borrow (the principal) plus any interest charged on the balance owed determines your monthly payment.
Most lenders use what’s called compound interest when calculating your monthly payment. This means they charge interest not only on what’s left unpaid but also on any unpaid accrued interest from previous months.
At the beginning of your repayment period or term (usually 36-60 months), most of your monthly payment goes towards paying off accrued interests rather than reducing the principal balance owed. This stage in repayment is known as negative equity or being underwater in terms of ownership value relative to outstanding debt/loan balance.
As time passes, more and more of each payment goes towards reducing Principal because less Interest accrues due to lower remaining balances owed by then until fully paid-off at maturity or early payoff if possible without penalty fees assessed.
Why Understanding Car Loan Amortization is Important
Understanding how car loan amortization works is crucial because it can help you make better financial decisions. Here are some of the reasons why:
1. Budgeting – Knowing what your monthly payments will be and how much interest you’ll pay over the life of the loan can help you create a realistic budget.
2. Comparison Shopping – When comparing different car loans, understanding the terms of each one’s amortization schedule will help you choose which one is best for your needs.
3. Early Payoff Strategies – If you decide to pay off your car loan early, understanding how your payments are being applied to principal and interest can help you determine the most effective payoff strategy.
How To Calculate Your Monthly Payment
Calculating your monthly payment requires knowing three things: The amount borrowed (the principal), the interest rate, and the length of time or term for repayment.
You could use an online calculator or let a lender do that work for you; however, here’s a formula that can give an estimate with simple math:
Monthly Payment = [Principal x Interest Rate] / [1 – (1 + Interest Rate)^(Term in months *-1)]
For example, suppose you take out a $20,000 car loan at 6% APR with a four-year repayment term (48 months). In that case, using this formula:
Monthly Payment = [$20,000 x .06] / [1 – (1 + .06)^(48 *-1)]
Monthly Payment = [$20k x .06] / [1 – (.06)^(-48)]
Monthly Payment = $466.10
Conclusion
Car loans are an excellent way to purchase a vehicle when paying upfront isn’t possible. However, when applying for such loans or considering taking them up as an option in financing purchases like cars or other assets on credit terms offered by lenders/creditors, it’s essential to understand how car loan amortization works.
Knowing how much you’ll pay monthly, what goes towards principal and interest, and the total cost of borrowing over time can help you make informed financial decisions. It also allows for effective budgeting, comparison shopping of terms offered by different lenders/creditors, and crafting a payoff strategy that suits your preference when ready or capable of doing so without penalty fees assessed.