Understanding the Prime Rate: How it Affects Borrowers and Lenders
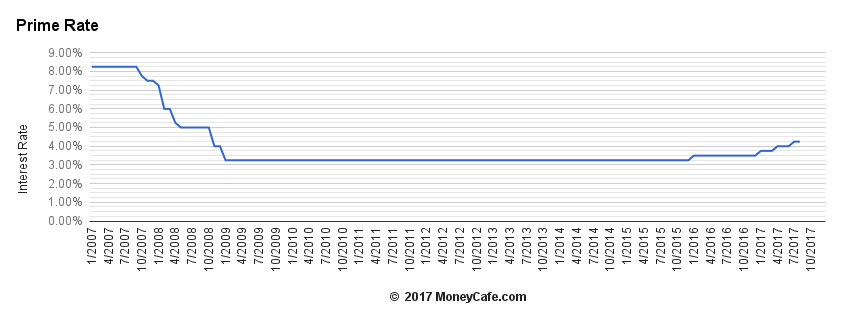
The prime rate is a crucial element in the financial world, and it affects borrowers and lenders alike. The prime rate refers to the interest rate that commercial banks charge their most creditworthy customers for loans. It is essentially a benchmark interest rate used to determine the cost of borrowing money. The prime rate serves as a basis for other lending rates such as mortgages, auto loans, and personal loans.
The Federal Reserve Bank sets its target federal funds rate which can influence changes in the prime rate. This means that when the Fed decides to increase or decrease its target federal funds rate, there’s often an associated change in the prime interest rate as well. Commercial banks use this as a reference point to set their own lending rates.
It’s important to note that not all borrowers get offered the same prime interest rates. Banks look at different factors like credit score, history of on-time payments, debt-to-income ratio and collateral when deciding what kind of loan terms they offer potential borrowers. Those who have good credit scores are more likely to receive better rates than those with poor credit scores.
One significant advantage of having lower interest rates is that it reduces overall borrowing costs for businesses and consumers – making it easier for them to obtain financing or pay off existing debts faster without going bankrupt over high-interest charges.
Additionally, fluctuating Prime Rates can impact economic growth both positively or negatively depending on whether we are experiencing an expansionary period (low unemployment/high output) or recession (high unemployment/low output). During times of low inflation/deflationary pressure where consumer spending is limited due decreased purchasing power- lowering these costs might help stimulate demand by incentivizing individuals looking for cheaper ways access cash needed during tough times.
On average, mortgage loans tend to follow fluctuations in the Prime Rate with some variation between different types of mortgages like adjustable-rate vs fixed-rate options which may be affected differently by these changes depending on market conditions such as inflation expectations among others factors unique to each type of loan.
For instance, if the interest rate on a 30-year fixed-rate mortgage is 4.5% and the prime rate drops from 3.75% to 3%, it’s unlikely that you will see any changes in your monthly payments since the two aren’t directly linked. However, if you have an adjustable-rate mortgage with a variable interest rate or home equity line of credit (HELOC), then a change in the prime interest rate could impact your monthly payments because they are directly tied to this benchmark.
In conclusion, understanding how Prime Rates work can be extremely beneficial for anyone seeking funding through loans or other types of financing options like credit cards, personal loans and mortgages since fluctuations can have significant impacts on borrowers’ costs over time. It’s important to keep track of changes in these rates so that you can make informed financial decisions when it comes to borrowing money either as an individual or business owner looking for opportunities during different economic conditions throughout their lifespan.