Unlocking Your Home’s Equity: A Guide to Second Mortgages
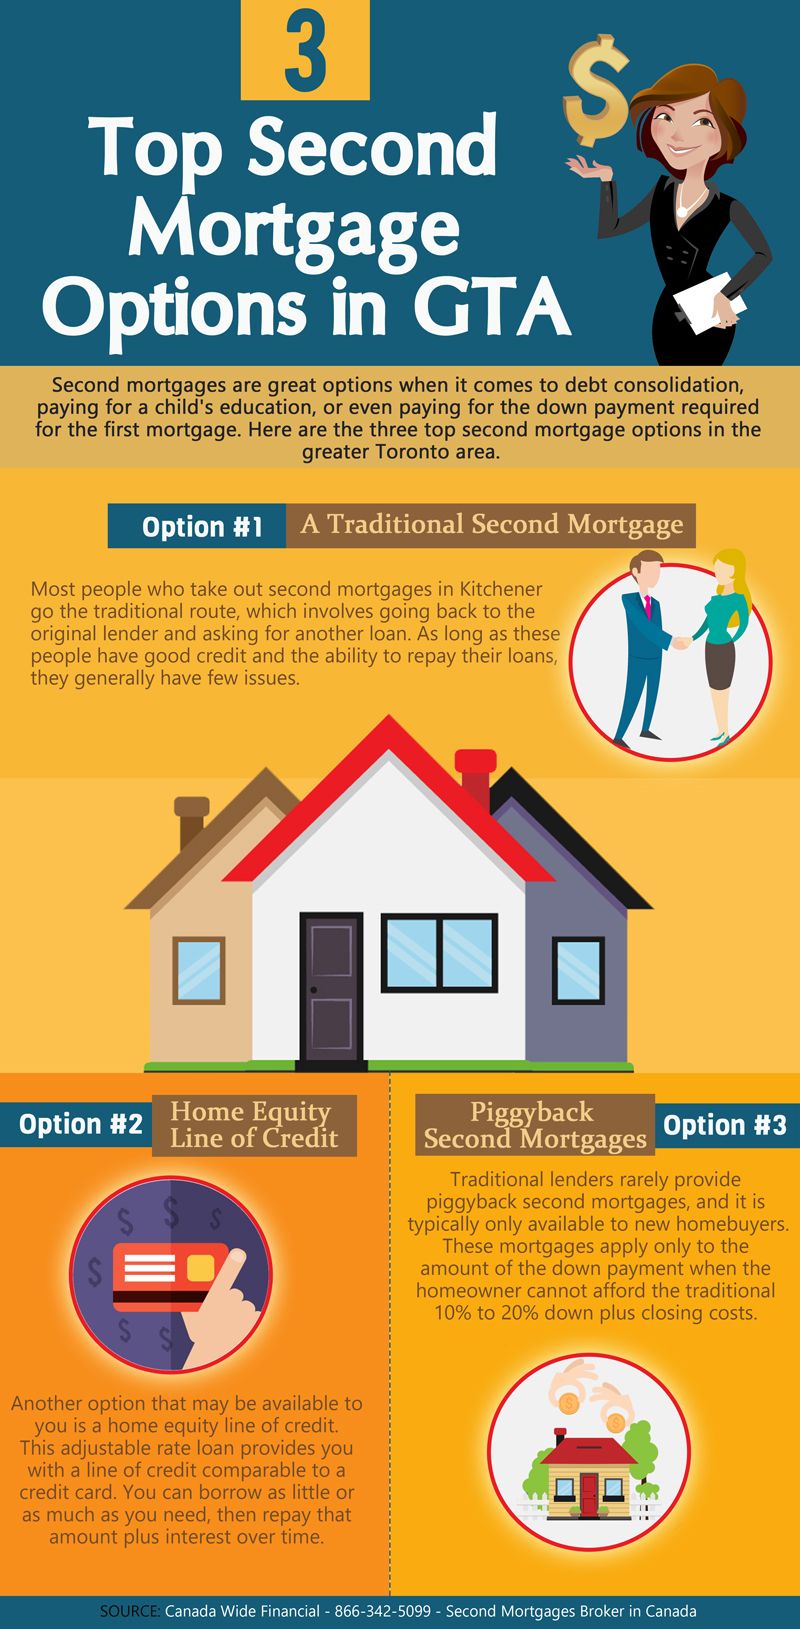
Second Mortgages: A Comprehensive Guide
For many homeowners, a second mortgage can be an attractive option. They offer access to cash and can be used for a variety of purposes such as home renovations, debt consolidation, or even funding a child’s college education. However, before taking out a second mortgage, it is important to understand what they are and how they work.
What is a Second Mortgage?
A second mortgage is a loan taken out against the equity in your home after you have already taken out your first mortgage. This type of loan allows you to borrow money using your home as collateral.
Types of Second Mortgages
There are two types of second mortgages: Home Equity Loans and Home Equity Lines of Credit (HELOCs).
Home Equity Loans – These loans allow you to borrow a lump sum amount at a fixed interest rate that must be repaid over time with regular payments.
HELOCs – HELOCs provide you with access to funds on an as-needed basis up to a certain limit approved by the lender. You only pay interest on the amount borrowed and can repay the borrowed funds at any time during the term.
Pros and Cons
One benefit of having a second mortgage is that it allows homeowners access to cash without having to sell their homes or refinance their primary mortgage. Additionally, interest rates tend to be lower than other forms of credit such as credit cards or personal loans.
However, there are also risks associated with second mortgages. If homeowners cannot make payments on their loans as agreed upon in their contract terms, then lenders could take possession of their homes through foreclosure proceedings. Additionally, fees associated with these types of loans may add up over time making them more expensive overall than alternatives like personal loans or credit cards.
Conclusion
Second mortgages can be useful tools for those who need financial assistance but should not be taken lightly. Before pursuing this option, consider all the factors involved in obtaining one including costs incurred throughout the loan term and the potential risks associated with repayment. By understanding all of this information, you can make a well-informed decision about whether or not a second mortgage is right for you.