Avoiding Early Withdrawal Penalties: 15 Fees to Watch Out For
Early withdrawal penalties are something that many people don’t think about until it’s too late. Whether you’re withdrawing from your retirement account, a savings account or a CD, the fees can add up quickly and eat into your hard-earned money. In this article, we’ll cover 15 early withdrawal penalties to help you avoid any unwanted surprises.
1. 401(k) Early Withdrawal Penalty: One of the most common early withdrawal penalties is for taking money out of your 401(k) before age 59½. You’ll typically be hit with a 10% penalty on top of income taxes.
2. IRA Early Withdrawal Penalty: Similar to the 401(k), if you withdraw funds from an IRA before age 59½, you’ll face a similar penalty.
3. Roth IRA Early Withdrawal Penalty: If you take earnings out of your Roth IRA before five years have passed since opening it, expect to pay taxes and a penalty.
4. Traditional IRA Early Withdrawal Penalty: The traditional IRA carries its own set of rules when it comes to early withdrawals; consult with your financial advisor.
5. Savings Account Early Withdrawal Penalty: Some banks may charge fees for taking money out before a certain period has elapsed after depositing funds in their savings accounts.
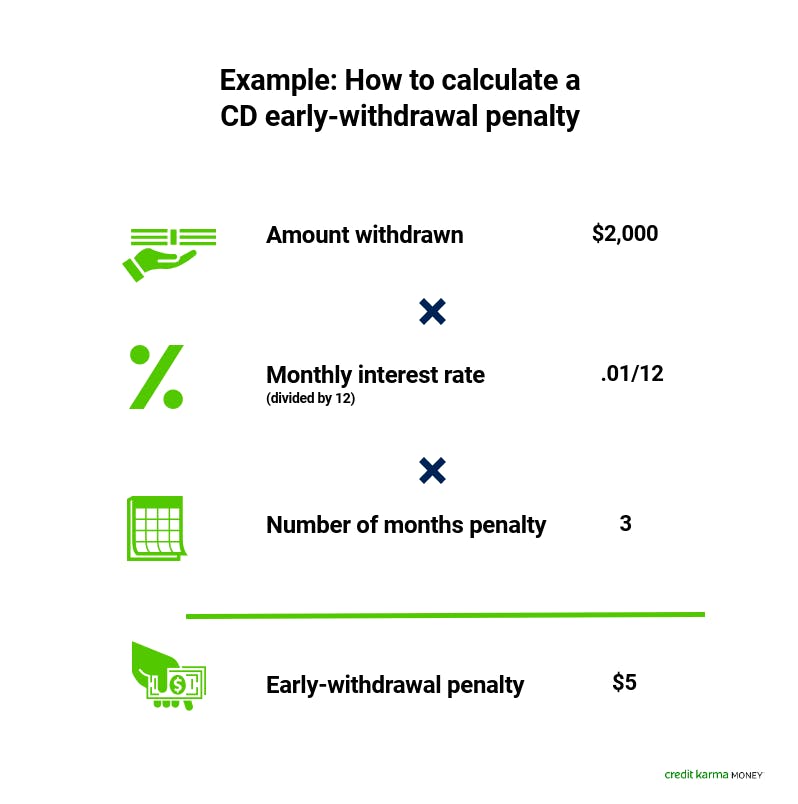
6. Certificate of Deposit (CD) Early Withdrawal Penalty: CDs usually offer higher interest rates than savings accounts but come with stiff early-withdrawal fees if you need access to cash sooner than agreed upon terms dictate.
7. Health Savings Account (HSA) Early Withdrawal Penalty: Withdrawing HSA funds for non-medical reasons will result in tax consequences and potential fines by the IRS
8. Education Savings Accounts (ESA) Early Withdrawal Penalties – ESA withdrawals not used towards qualified educational expenses are subject both federal and state income tax as well as an additional ten percent penalty on earnings
9.Municipal Bonds – Municipal bonds may be subject to early withdrawal penalties if sold before the maturity date
10. Annuities – Depending on the type and specific terms of your annuity, you may face surrender charges or penalty fees for withdrawing money before a predetermined time.
11. Real Estate Investing – Early withdrawal from real estate investments can result in significant tax consequences.
12. Stocks- When selling stocks too soon after purchase, investors may have to pay capital gains taxes as well as potential brokerage fees.
13. Life Insurance Policies – Liquidating life insurance policies too quickly can lead to fines or other charges by insurers that need to recoup losses they incur because of an early payout.
14. Credit Cards: Withdrawing cash from your credit card account is expensive; interest rates are high, and additional transaction fees are added in most cases.
15. Penalty-Free Exceptions – Certain situations such as medical expenses or buying a first home allow for penalty-free withdrawals from certain types of accounts like the 401(k) plan without triggering early withdrawal penalties.
In conclusion, early withdrawal penalties can be costly and prevent you from accessing much-needed funds when you need them most. The best way to avoid paying these fees is by planning ahead, understanding the rules that govern each account type and exploring alternative options such as loans or lines of credit instead of taking outright withdrawals whenever possible. Remember always consult with your financial advisor whenever making investment decisions that could affect your financial goals in any way shape or form!