Is Converting from a Traditional IRA to a Roth IRA Right for You?
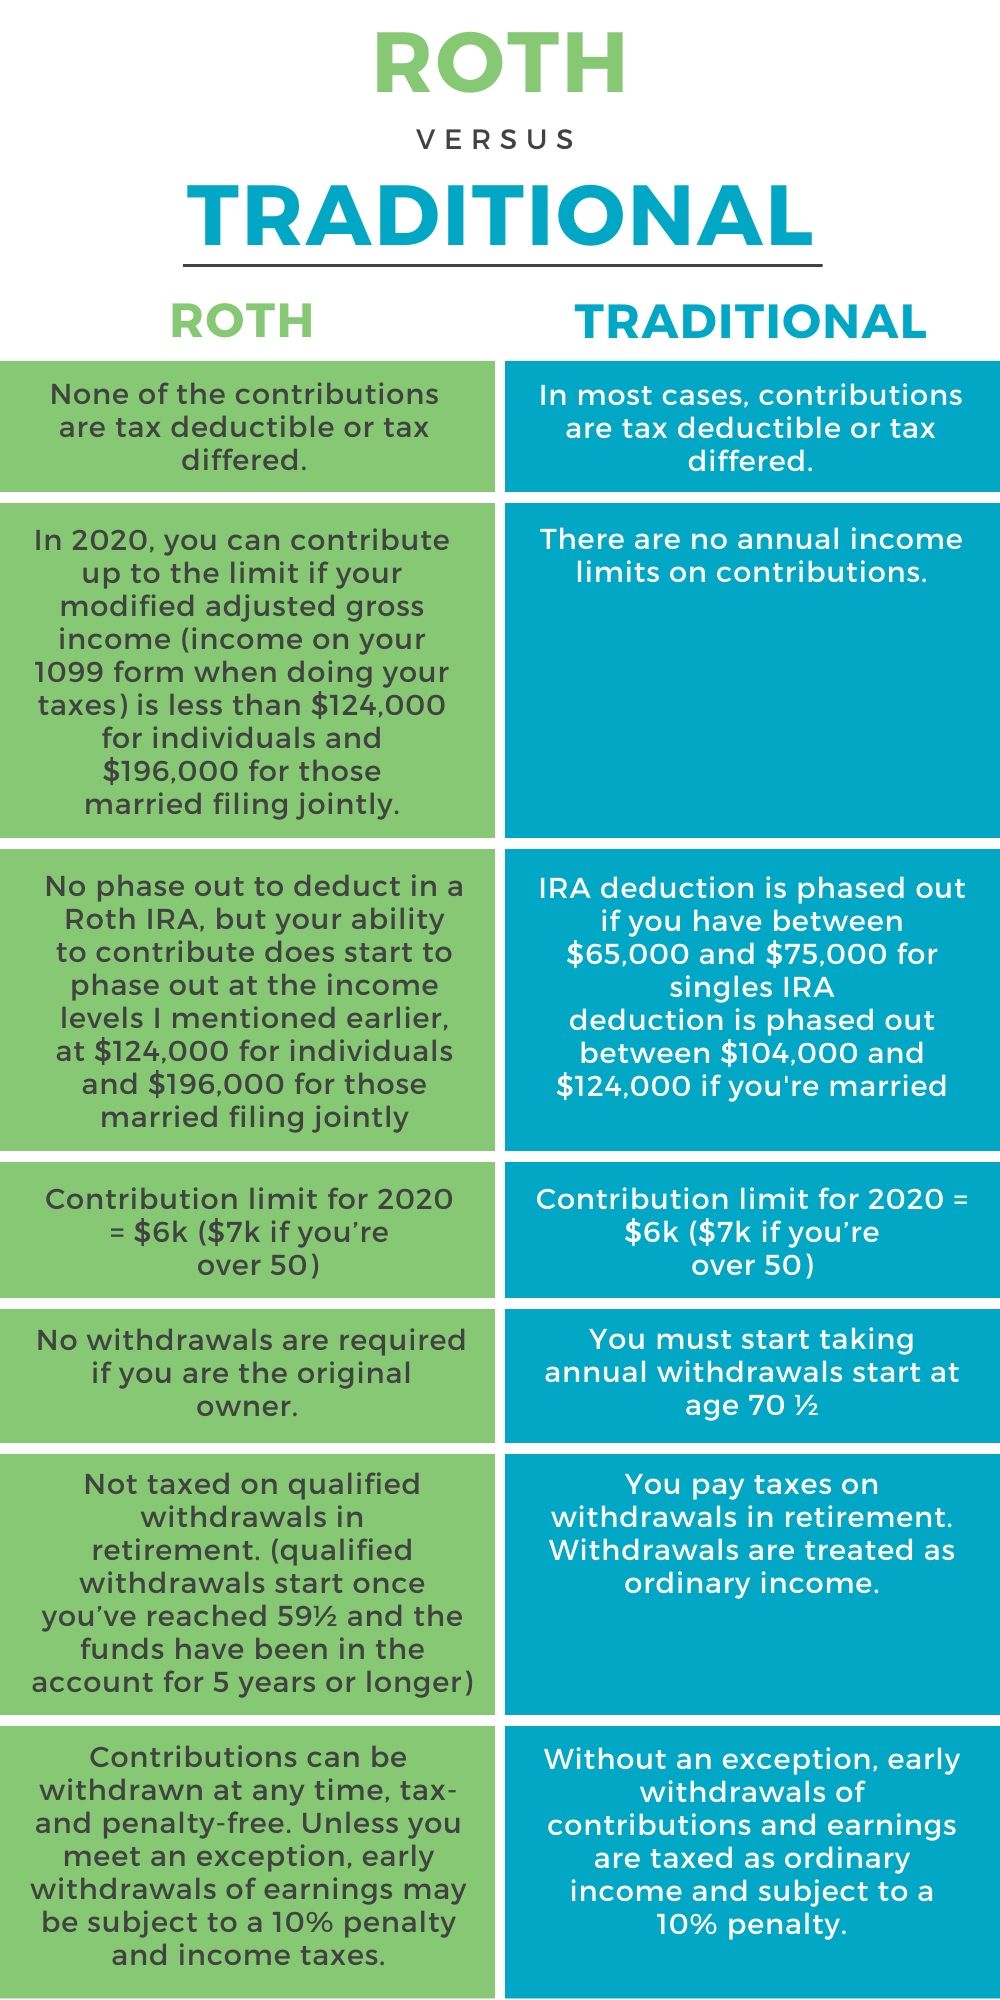
Individual Retirement Accounts (IRAs) are an excellent way to save for retirement. Traditional IRAs allow you to contribute funds before taxes, which can lower your taxable income in the year of contribution. Roth IRAs, on the other hand, require after-tax contributions but offer tax-free withdrawals in retirement. If you’re thinking about converting from a traditional IRA to a Roth IRA, there are some important things you should consider.
What is a Traditional IRA?
A Traditional IRA is an account that allows individuals under age 70½ who have earned income to make tax-deductible contributions up to certain limits each year. The amount of the deduction depends on whether or not the individual is covered by another plan at work and their modified adjusted gross income (MAGI). Contributions grow tax-deferred until withdrawn; however, when distributions are made during retirement years they will be taxed as ordinary income.
Traditional IRAs also come with Required Minimum Distributions (RMDs), which means that once you reach age 72, you must take out a minimum amount of money each year regardless of whether or not you need it.
What is a Roth IRA?
A Roth IRA is similar to a traditional IRA except for one major difference: contributions are made after taxes have been paid. This means that any earnings within the account grow tax-free and qualified withdrawals taken during retirement years are also tax-free.
Another advantage of Roth IRAs over traditional IRAs is that RMDs do not apply; this means that there’s no requirement for mandatory withdrawals at any point in time.
Why Consider Converting from a Traditional to a Roth IRA
There are several reasons why someone might want to convert their traditional IRA into a Roth:
1. Tax-Free Withdrawals: By converting from your traditional IRA into a Roth, all future qualified withdrawals will be completely tax-free – meaning more money in your pocket!
2. No RMDs: As mentioned earlier, Roth IRAs do not have RMDs. This can be a major advantage for someone who doesn’t need the required distributions or is looking to minimize their taxable income during retirement.
3. Tax Diversification: Having both Roth and traditional IRA accounts allows you to diversify your tax burden in retirement. You can withdraw from either account based on which one makes the most sense at any given time, depending on your tax situation.
4. Lower Taxes: If you’re currently in a lower tax bracket than what you anticipate being in during retirement, converting from a traditional to a Roth IRA now may help you pay less taxes overall over time.
Considerations Before Converting
Before deciding whether or not to convert from a Traditional IRA to a Roth IRA, it’s important to consider several factors:
1. Your Current Tax Bracket: Converting from Traditional IRA into a Roth will require paying taxes on all of the pre-tax contributions made so far plus any earnings within the account. Therefore, if you are currently in a higher tax bracket than what you expect your future rate will be during retirement years, it may not make sense financially.
2. Time Horizon: The longer period of time before withdrawals begin means more time for investments within the account to grow and compound without being subject either taxation or mandatory distribution requirements (RMDs). However, if there’s no plan to keep funds invested for an extended period of time after conversion then this strategy might not work best for everyone.
3. Availability of Funds Outside of Retirement Accounts: It is essential that individuals have enough money outside their retirement accounts that they can use if something unexpected happens – like an emergency expense occurs – before reaching age 59 ½ when penalties apply for early withdrawals.
4. Future Contribution Limits/Eligibility Requirements: If someone converts their traditional IRA into a Roth but later finds out that they’re no longer eligible due to income limits on contributions towards regular IRAs, or the total contributions made exceed annual limits for Roth accounts then this may not be the best strategy.
How to Convert from a Traditional IRA to a Roth IRA
Once you’ve determined that converting from your traditional IRA into a Roth is in your best interest, there are several ways to make the switch:
1. Direct Rollover: The easiest way to convert is through a direct rollover. This involves transferring assets directly from one account into another without any distribution being made. There’s no tax liability with this option and it can be completed quickly and easily.
2. Indirect Rollover: An indirect rollover involves withdrawing funds from your traditional IRA and depositing them into your Roth within 60 days of withdrawal. With this option, however, there’s an increased risk of tax liability if you fail to complete the deposit within 60 days.
3. Partial Conversion: If someone wants more control over their taxes they can choose partial conversion – only converting part of their Traditional IRA balance at once instead of all at once which would result in higher taxes overall due to large income spikes when making bigger withdrawals.
Conclusion
Converting from a traditional IRA to a Roth may make sense for some individuals; however, before making any decisions it’s important to consider factors like current tax brackets, future contribution eligibility requirements/limits as well as availability of funds outside retirement accounts among other things so that you’ll have enough money available throughout retirement years while minimizing taxation along the way!