Maximizing Tax Efficiency: Tips and Strategies to Save Money
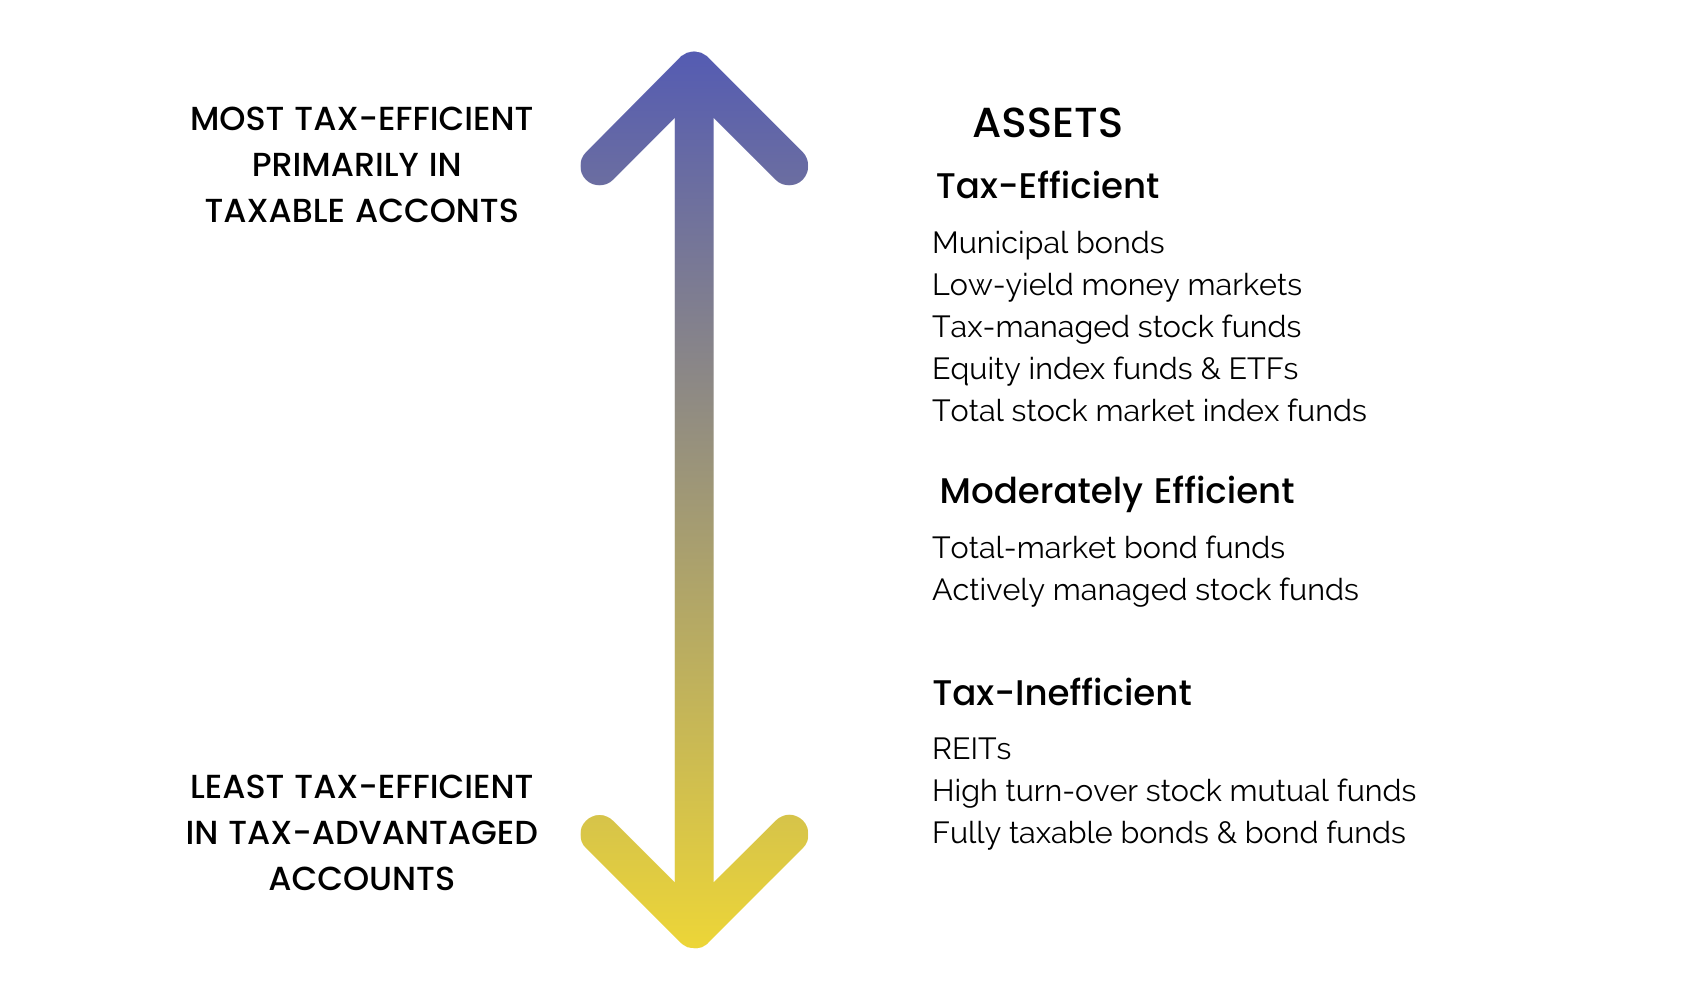
Tax Efficiency: How to Maximize Your Savings
No one likes to pay more taxes than they have to, but many people aren’t taking advantage of all the tax-saving strategies available to them. With a little bit of planning and attention, you can significantly reduce your tax bill and keep more money in your pocket.
Here are some tips for maximizing your tax efficiency:
1. Contribute to Retirement Accounts
One of the most effective ways to reduce your taxable income is by contributing to a retirement account such as an IRA or 401(k). Not only will this lower your current-year taxes, but it will also help you save for retirement.
2. Consider Roth Contributions
If you’re eligible for a Roth IRA or 401(k), consider making contributions. Although these accounts don’t offer immediate tax benefits, qualified withdrawals are entirely tax-free.
3. Take Advantage of Tax Credits
Tax credits can be incredibly valuable because they directly reduce your tax liability dollar-for-dollar. Examples include the Child Tax Credit and Earned Income Tax Credit.
4. Itemize Deductions
Many taxpayers claim the standard deduction without considering whether itemizing would result in a larger deduction. If you have significant expenses such as charitable donations or mortgage interest, it may be worth itemizing instead.
5. Avoid Capital Gains Taxes
Capital gains occur when you sell an asset such as stocks or real estate for a profit. However, if you hold onto an asset for at least one year before selling it, any gains will be taxed at lower long-term capital gains rates rather than higher short-term rates.
6. Use Tax-Loss Harvesting
If you’ve realized losses on investments during the year, consider using those losses to offset any capital gains that might otherwise increase your tax liability.
7. Be Strategic About Timing
You may be able to control when certain types of income are received in order to minimize taxes owed in any given year—for example, by delaying a bonus until the following year.
8. Make Charitable Donations
Charitable donations can not only benefit your favorite causes but also help reduce your taxable income. Be sure to keep receipts for all charitable contributions.
9. Consider Health Savings Accounts (HSAs)
If you have a high-deductible health plan, contributing to an HSA can be an excellent way to save on taxes while preparing for future healthcare expenses.
10. Educate Yourself About Tax Law Changes
Tax laws are constantly changing, and staying informed about new provisions or regulations can help you take advantage of tax-saving opportunities as they become available.
11. Use a Professional Accountant or Tax Advisor
A qualified accountant or tax advisor can offer personalized advice and guidance that takes into account your specific financial situation and goals.
12. Keep Accurate Records
To ensure that you’re taking full advantage of all available deductions and credits, it’s crucial to keep accurate records of all income, expenses, and other financial transactions throughout the year.
While some of these strategies may require more effort than others, investing time in tax planning now will pay off in significant savings down the line. By taking control of your finances through smart tax management, you’ll be well on your way to achieving long-term financial security.