Refinancing Options: Your Guide to Saving Money
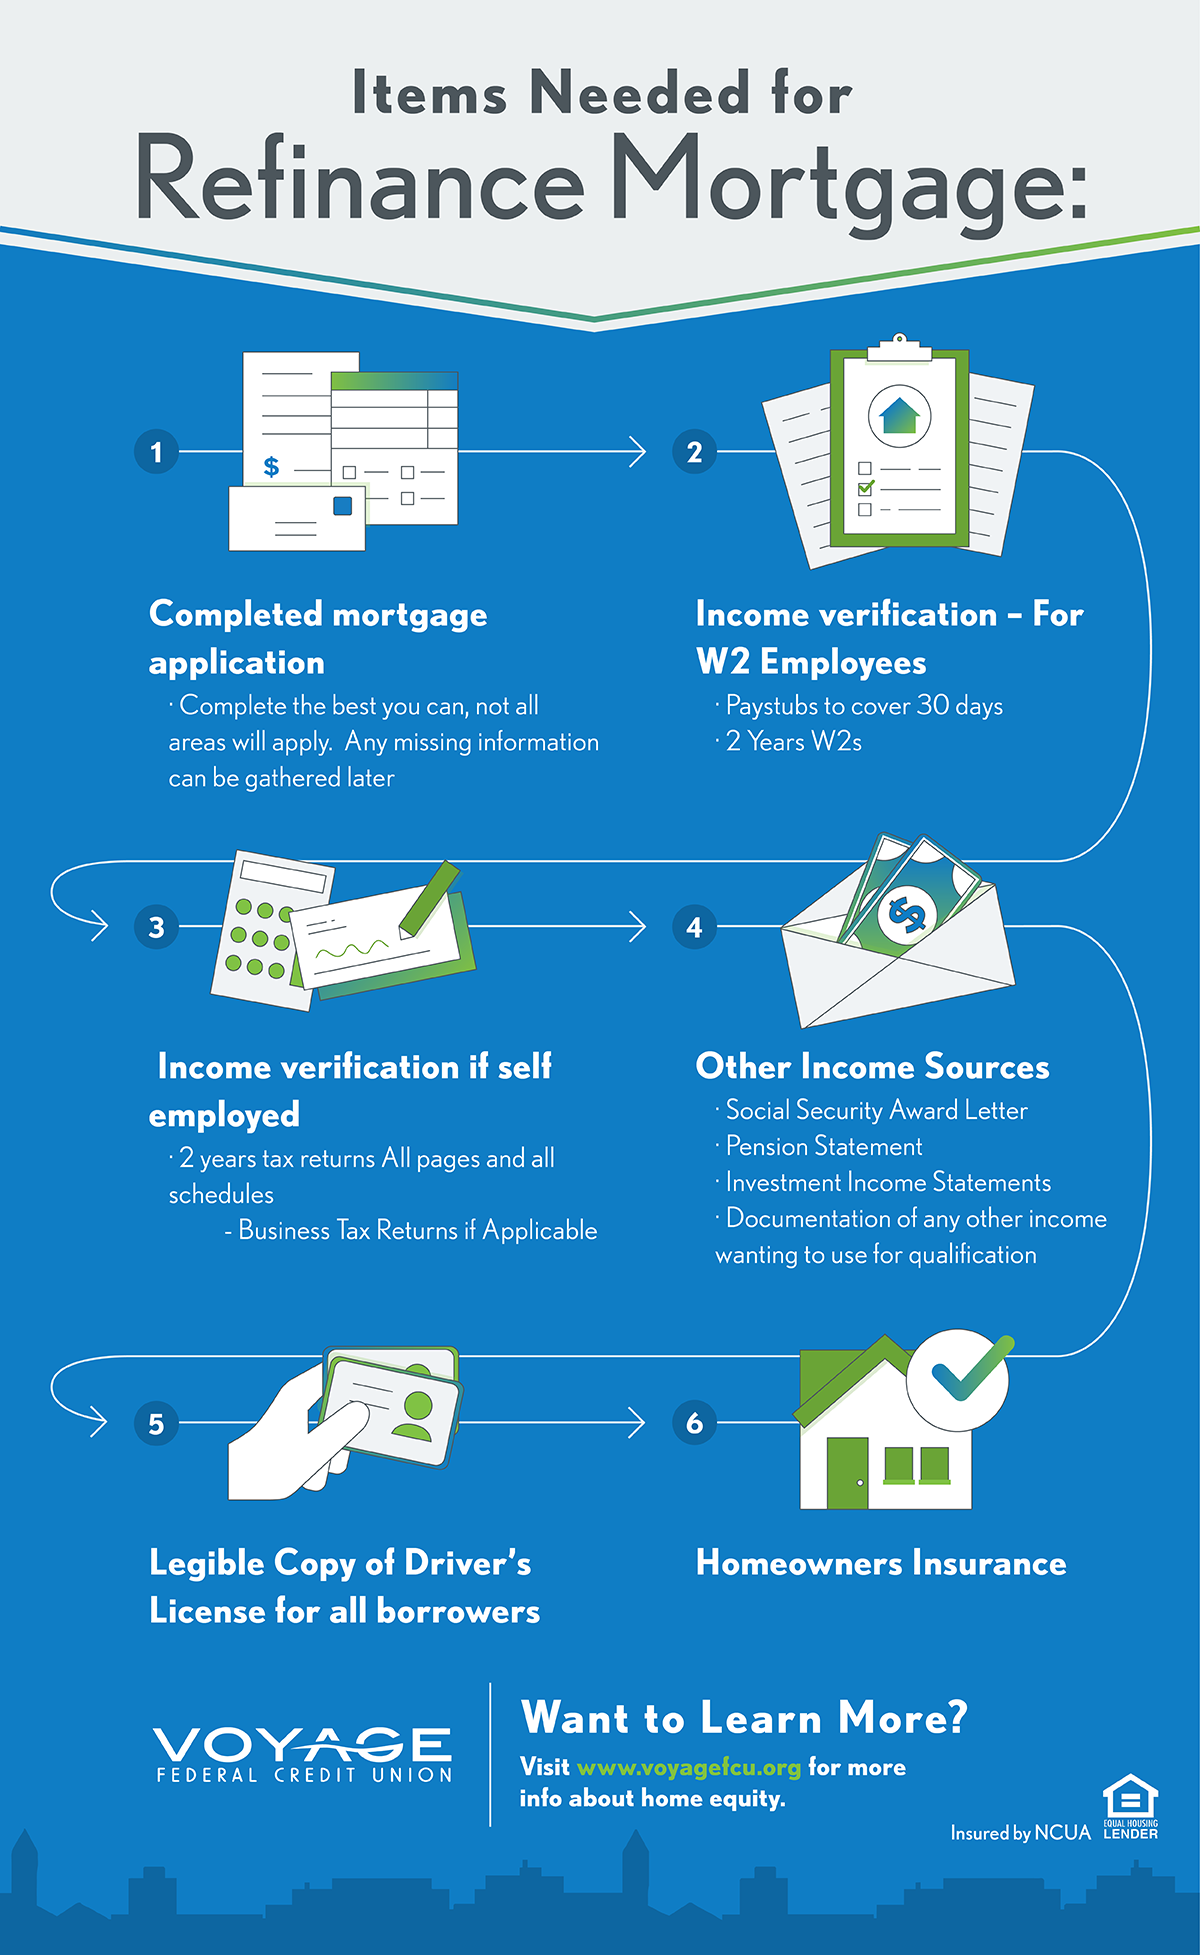
Refinancing Options: A Guide to Saving Money
Refinancing can be a great way to save money on your monthly mortgage payments or reduce the overall interest paid over the life of a loan. However, it’s important to understand the various options available and determine which one is right for you.
Option 1: Traditional Refinance
A traditional refinance involves replacing your current mortgage with a new one that has better terms. This can include an interest rate reduction, shorter loan term, or switching from an adjustable-rate mortgage (ARM) to a fixed-rate mortgage. To qualify for a traditional refinance, you’ll need good credit and equity in your home.
Option 2: Cash-Out Refinance
With a cash-out refinance, you take out a new mortgage that’s larger than your existing balance and receive the difference as cash. This option is best suited for those who have significant equity in their home and want to use it for things like home improvements or debt consolidation.
Option 3: Streamline Refinance
Streamline refinancing is available only for certain types of loans such as FHA or VA loans. It requires less paperwork and may not require an appraisal or income verification. The main goal of streamline refinancing is to lower monthly payments by reducing interest rates.
Option 4: HARP Refinance
The Home Affordable Refinance Program (HARP) allows homeowners who owe more than their homes are worth to refinance at lower rates without having to pay extra fees or mandatory PMI insurance premiums.
Before deciding on any refinancing option, it’s important to do research and compare offers from multiple lenders. You should also carefully consider closing costs associated with refinancing as they can add up quickly. With careful consideration though, refinancing could lead to substantial savings over time!