Theta: From Ancient Greece to Modern-Day Options Trading
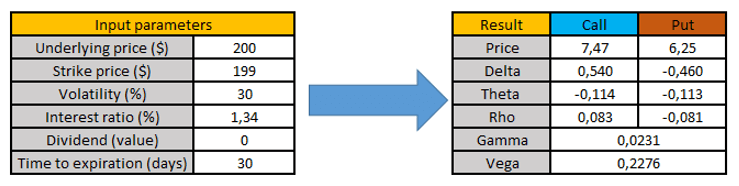
Theta: A Historical Perspective
Theta is a Greek letter that has become synonymous with options trading. It represents the rate of decay or time erosion of an option’s value as it approaches its expiration date. Theta is one of several “Greeks” used by traders to measure the sensitivity of their options positions to changes in various market factors.
The concept of theta, however, goes back much further than modern-day options trading. The ancient Greeks had their own understanding and use of theta in mathematics and philosophy.
In mathematics, theta was used to represent angles in geometry and trigonometry. The symbol θ was commonly used to denote unknown angles or variables. In physics, it represented temperature or potential energy.
In philosophy, theta had a more mystical meaning. It was associated with the concept of thymos or soul, which encompassed emotions such as anger, courage, and love. Plato believed that thymos played a crucial role in human behavior and morality.
The symbol for theta also appears in early Christian art as a representation of the Holy Trinity – Father, Son, and Holy Spirit – united as one Godhead.
Fast forward to modern times; Theta has taken on new significance in finance as an essential tool for option pricing models. Options are financial instruments that give buyers the right but not the obligation to buy (call) or sell (put) an underlying asset at a predetermined price within a specified timeframe.
The value of an option depends on several factors such as the price movement of the underlying asset (stock), volatility levels, interest rates and time left until expiration.
Time decay is one aspect that affects options pricing model significantly. For instance consider two call options contracts expiring on different days – one due today while other due after 30 days- both based on similar stocks having similar strike prices will have different values because they have different amounts remaining before expiry dates.
This difference between these values accounts for time decay or theta. Theta measures how much the value of an option will erode over time as it approaches expiration. It is a critical component in determining the fair price for an option, along with other Greeks such as Delta (sensitivity to stock prices), Gamma (sensitivity to changes in delta) and Vega (sensitivity to volatility).
Theta can be positive or negative, depending on whether an option is “in-the-money” (ITM), “at-the-money” (ATM), or “out-of-the-money” (OTM). ITM options have intrinsic value and are more expensive than their ATM and OTM counterparts; therefore, they have higher absolute theta values.
On the other hand, ATM options tend to have zero or near-zero absolute theta values because they are priced at fair value based on Black Scholes pricing model assumptions. For out-of-the-money options, theta is typically negative since these contracts are less likely to end up profitable as expiration approaches.
Theta’s importance lies not only in pricing models but also in trading strategies. Options traders use various techniques to capitalize on changes in underlying asset prices, volatility levels and time decay using different combinations of calls and puts.
One popular strategy that involves theta is known as selling covered calls. This strategy involves owning shares of a stock while simultaneously selling call options against those shares at above-market strike prices.
The premium collected from the sale of the call reduces the cost basis of owning the stock while limiting potential upside gains if shares rise significantly before expiry date resulting into early assignment by holders.
Since covered calls generate income through premium collections due upon writing those contracts – which depends largely upon their associated tetha values- this strategy has been used extensively by investors looking for steady income streams from their investments over extended periods.
Another approach that utilizes theta is known as calendar spreads or horizontal spreads where an investor purchases one option contract with longer-term expiry date while simultaneously selling another option with shorter-term expiration date on the same underlying asset at an equal or higher strike price.
This strategy aims to profit from the difference in time decay between two options contracts. The long-term option will have a lower absolute theta value than the short-term option, so as time passes, the spread should widen resulting into profits for investors.
In conclusion, Theta is not just another Greek letter used in finance but has a rich history across various fields such as mathematics, philosophy and religious symbolism. In modern times it has become an essential tool for pricing models and trading strategies in options markets.
Options traders looking to capitalize on changes in market conditions while limiting risks can use Theta along with other Greeks to develop profitable trading strategies that generate steady income streams over extended periods.