Credit Scores 101: Boost Your Ratings and Secure Your Financial Future
Credit Scores: Understanding the Basics and How to Improve Them
Credit scores play a significant role in our financial lives. They determine whether we can get approved for credit cards, loans, mortgages, and other financing options that allow us to make significant purchases. A good credit score is essential if you want to buy a car or a house, start your own business or even secure employment.
What is a Credit Score?
A credit score is a numerical representation of how well you have managed your finances over time. It reflects how likely you are to pay back debts on time based on past behavior. The most commonly used type of credit score in the United States is the FICO® Score.
Your FICO® Score ranges from 300 to 850 points, with higher scores indicating better creditworthiness. Lenders use these ratings as part of their decision-making process when considering loan applications.
In general terms, people with high credit scores tend to be more responsible borrowers who pay their bills promptly and keep their balances low. Conversely, those with low scores may have missed payments or defaulted on loans in the past.
Factors That Affect Your Credit Score:
1) Payment History – This accounts for about 35% of your FICO® Score and looks at whether you’ve paid your bills on time consistently.
2) Amount Owed – This factor accounts for around 30% of your FICO® Score and considers how much debt you have relative to your available credit.
3) Length of Credit History – This represents roughly 15% of your FICO® Score and takes into account how long each account has been open.
4) New Credit – Opening too many new accounts in quick succession can negatively impact this section which makes up around 10%.
5) Types of Credit Used – This final category consists of approximately 10%, it’s important because it shows lenders that you can handle different types of debt such as installment loans, credit cards and so on.
How to Improve Your Credit Score:
1) Pay Bills on Time – Payment history is the most significant factor in your credit score. Late payments can harm your score severely, so be sure to make all your payments on time.
2) Keep Balances Low – High balances can indicate that you’re not managing your finances well. Lenders prefer borrowers who use less than 30% of their available credit.
3) Limit New Credit Applications – Opening too many new accounts at once will signal desperation for money and lenders may view this as a sign of financial instability or irresponsibility.
4) Build a Good Credit History – It takes time to build up a good credit history but it’s worth it in the long run. Consider opening one or two accounts and paying them off consistently each month over several years.
5) Check Your Credit Report Regularly – Requesting reports from each of the three main bureaus (TransUnion, Equifax and Experian) annually allows you to keep tabs on any unusual activity such as identity theft which could harm your scores.
What is Considered a Good Credit Score?
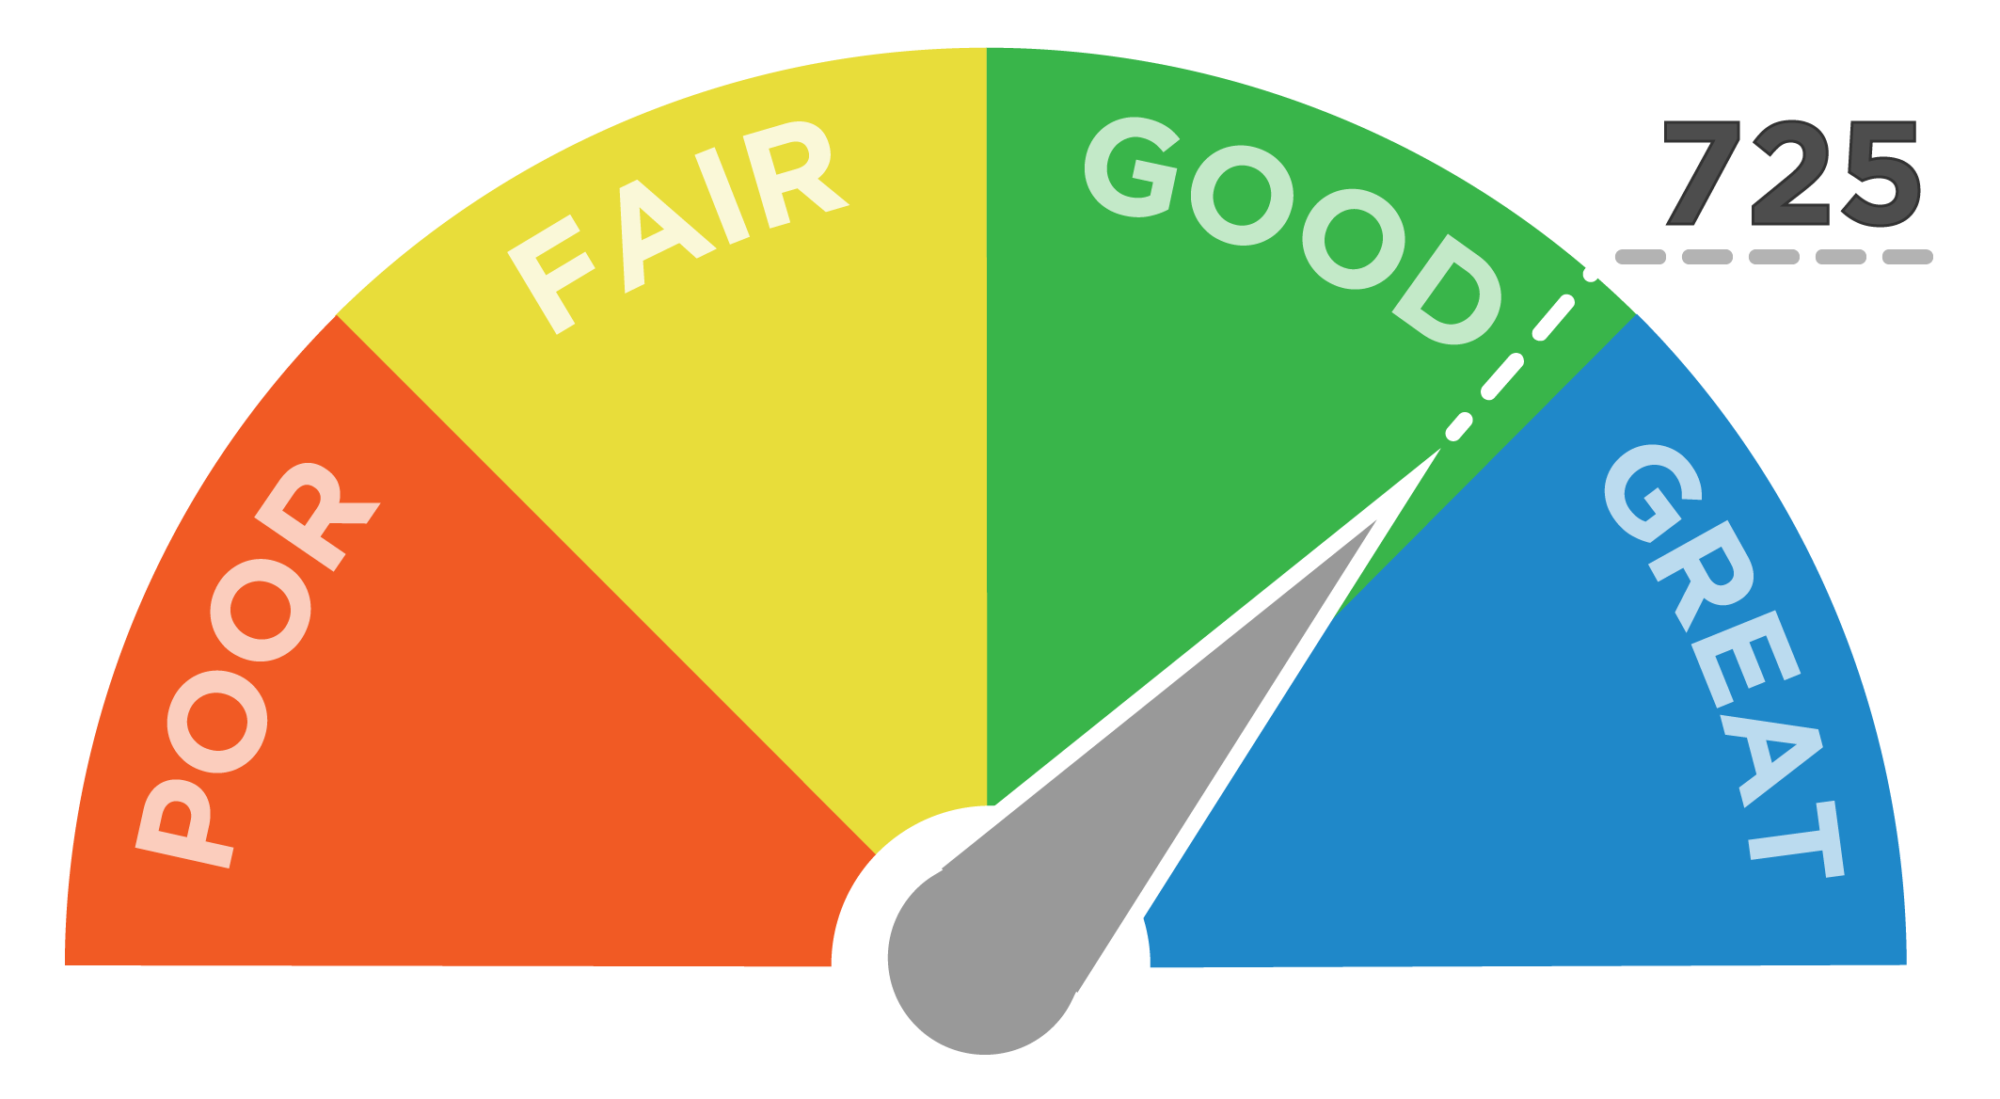
A high FICO® Score indicates that you are more likely to repay debts reliably than someone with lower ratings. Here’s how scores typically break down:
– Excellent: 800+
– Very Good: 740-799
– Good: 670-739
– Fair: 580-669
– Poor: <580
Most lenders consider anything above 670 as good enough to approve loans or extend credit facilities. However, these numbers vary by lender type; some may require higher scores before granting approvals while others might have more lenient standards.
Conclusion
Your credit score plays an essential role in determining whether you qualify for financing options like loans and mortgages. As such, it's crucial that you manage your finances responsibly if you want excellent ratings.
Improving your score starts by paying your bills on time and keeping balances low. Limiting new credit applications, building a good credit history over time, and checking your reports regularly are also important steps to take.
Remember that some factors affecting your score carry more weight than others; payment history is the most significant, so try not to miss any payments if possible. By understanding these basics of credit scores and taking steps to improve it, you'll be in a better position to achieve financial stability and reach your long-term goals.