“Expert Panel Reveals Essential Personal Finance Tips for Financial Security”
Introduction:
Personal finance is an essential aspect of everyone’s life. It involves managing your money, investing in the right assets, and planning for a secure future financially. However, with the current economic situation, it has become even more crucial to take control of our personal finances. In this panel discussion style post, we will discuss some essential personal finance tips that can help you achieve financial security.
The Panelists:
1. Jane Doe- Financial Advisor
2. John Smith – Investment Banker
3. Emily Johnson- Personal Finance Writer
Question 1: What Are Some Essential Personal Finance Tips That Everyone Should Know?
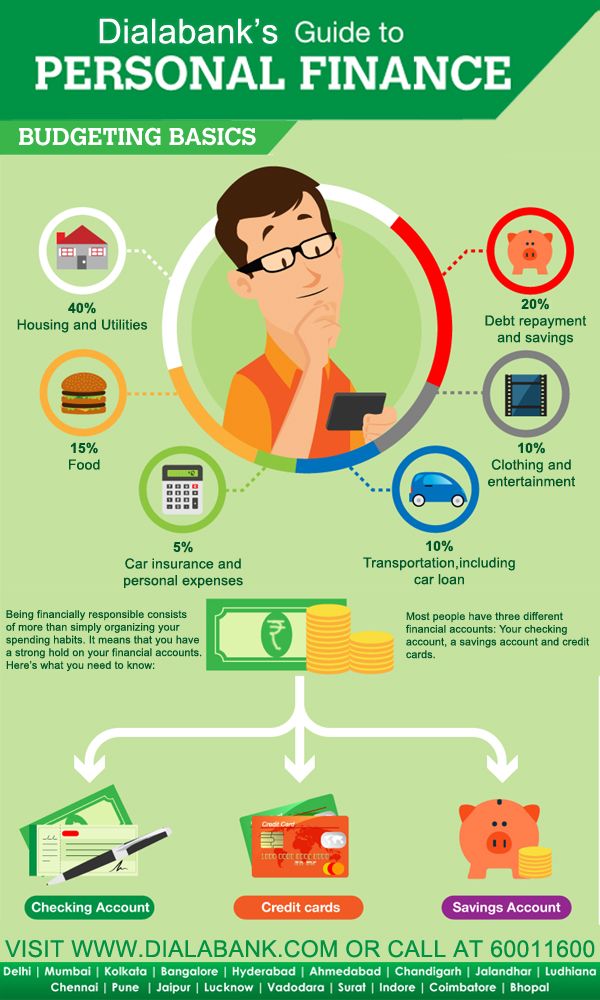
Jane Doe: The first thing people should do is create a budget and stick to it. You need to know how much money you have coming in versus how much you spend each month.
John Smith: Another tip is to start investing early! Compound interest can work wonders over time if you start early enough.
Emily Johnson: I also recommend building up an emergency fund that covers at least three months’ worth of expenses.
Question 2: How Can Someone Get Started Investing?
John Smith: Start by learning about different types of investments such as stocks, bonds or mutual funds. Then open an account with a reputable brokerage firm or robo-advisor like Betterment or Wealthfront.
Jane Doe: I agree; education is key when it comes to investing because there are risks involved. You don’t want to invest blindly without knowing what you’re getting into.
Emily Johnson: Also remember not to put all your eggs in one basket- diversification is important when it comes to investing!
Question 3: How Can One Pay Off Debt More Effectively?
Jane Doe: One way would be using the snowball method where you pay off debts starting from smallest balance while maintaining minimum payments on other accounts until they’re paid off too.
John Smith: Another option would be consolidating debt through a low-interest loan or balance transfer credit card.
Emily Johnson: And it’s important to avoid accruing more debt while trying to pay off existing ones. Try living below your means and cutting back on expenses, so you have more money for paying down debt.
Question 4: What Are Some Common Mistakes People Make With Personal Finance?
John Smith: One common mistake is not saving enough for retirement. Many people put it off and miss out on the opportunity to take advantage of compound interest over a long period.
Jane Doe: Another mistake I often see is overspending or taking on too much debt without a plan in place to pay it off.
Emily Johnson: Also, some people don’t invest because they think they can’t afford it, but the truth is that everyone can start small and work their way up. It’s better than not investing at all!
Question 5: How Can Someone Improve Their Credit Score?
Jane Doe: Pay bills on time! Timely payments are one of the most significant factors that affect your credit score positively.
John Smith: Another tip would be keeping your credit utilization ratio low- meaning using less than 30% of available credit limit
Emily Johnson: Also, dispute any errors or inaccuracies in your report with the three major bureaus – Equifax, Experian & TransUnion – as these could negatively impact your score if left unresolved.
Conclusion:
In conclusion, personal finance requires discipline and consistency over time. By implementing some of the tips discussed above such as budgeting wisely, starting early when investing in diversified portfolios with sound investment strategies tailored towards achievable goals; managing debts effectively by consolidating them smartly; avoiding common mistakes like overspending or under-saving for retirement while improving one’s credit score through timely payments and disputing errors where necessary – anyone can achieve financial security gradually over time.