“Grow Your Wealth with Dollar-Cost Averaging: The Automated Approach to Investing”
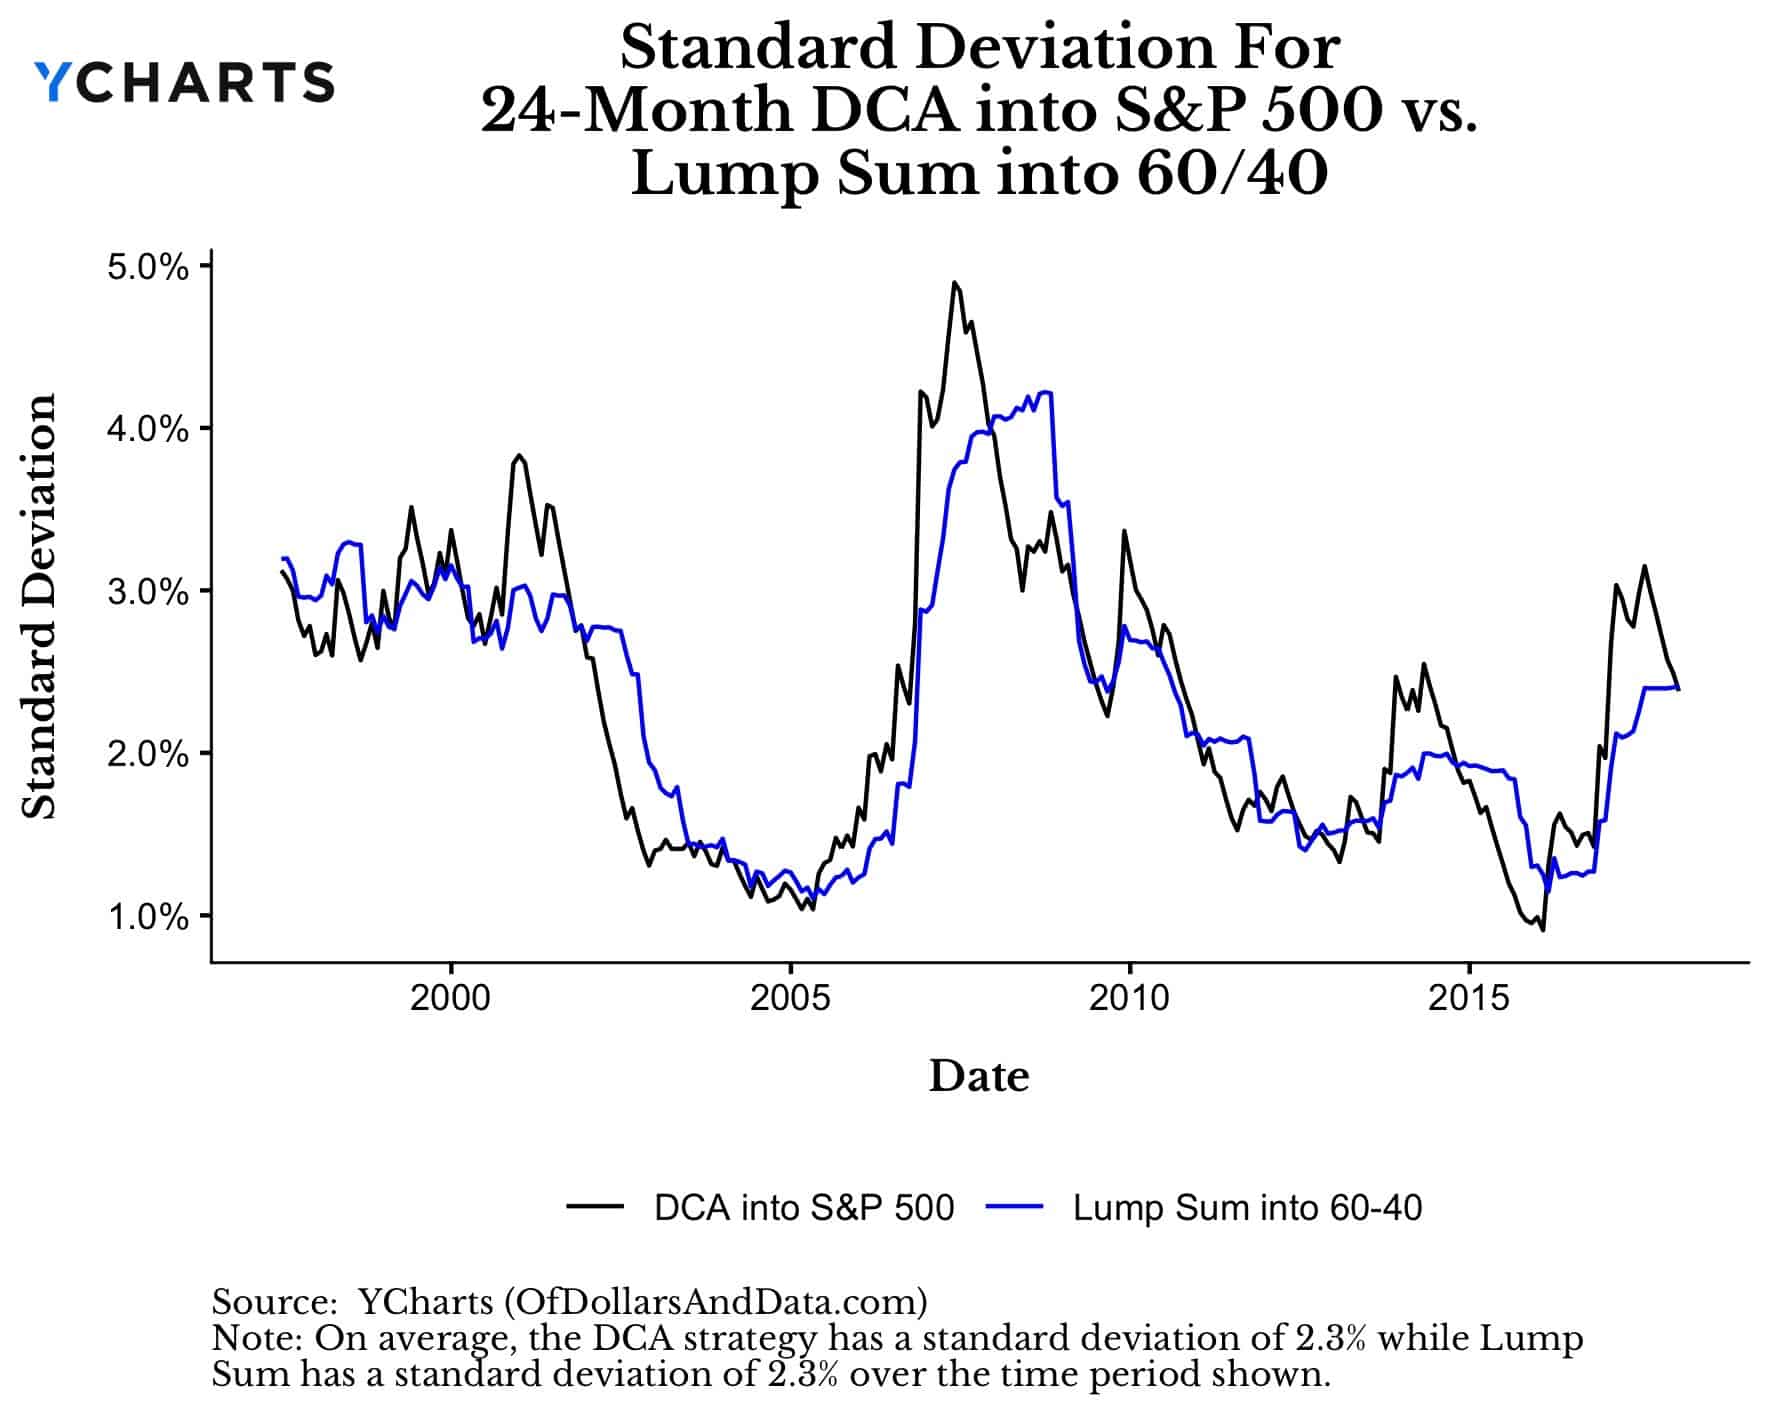
As a writer and journalist who focuses on personal finance, I have come across many investment strategies that people use to grow their wealth. One of the most popular ones is dollar-cost averaging (DCA). DCA is an investing strategy where you invest a fixed amount of money at regular intervals over a long period. The idea behind this strategy is that it helps reduce the impact of market volatility by spreading your investment over time.
The concept of DCA is quite simple. Instead of investing all your money at once, you divide it into equal parts and invest those parts gradually over time. For example, if you want to invest $10,000 in stocks, instead of doing so all at once, you could split it up into $1,000 investments spread out over ten months or even years.
One significant advantage of DCA is that it reduces the risk associated with timing the market. It eliminates the need for investors to make predictions about whether markets will rise or fall in the short term because they are investing regularly regardless of current market conditions.
Another advantage is that DCA can help investors avoid emotional decisions based on fear or greed during times of extreme market volatility. For instance, when markets are crashing and everyone else appears to be selling off their shares in panic mode, investors using DCA can continue buying stocks as usual since they know they’re getting them cheaper than before.
Furthermore, with DCA being an automated approach to investing regularly over a long period (generally years), it helps build discipline among investors who might otherwise struggle with staying committed to their long-term financial goals.
When considering dollar-cost averaging as an investment strategy there are some key factors worth keeping in mind:
Firstly; choosing what assets/classes should be bought requires due diligence and research by would-be investors beforehand so they can decide which options best fit their financial objectives.
Secondly; some investments may attract fees such as upfront charges or annual management costs or transaction fees that could potentially impact the overall returns of the investment or cause it to become more expensive.
Lastly, DCA is all about investing regularly over a long period. It requires patience and discipline as investors need to be prepared to stick with their chosen asset allocation plan even when markets are volatile or their investments seem not to be doing well in the short term.
In conclusion, Dollar-cost averaging can be an excellent strategy for anyone who wants to invest but doesn’t want the stress of timing the market fluctuations. By investing a fixed amount at regular intervals over time, you can reduce your risk and take advantage of dollar-cost averaging’s benefits. Additionally, DCA can help build financial discipline while achieving long-term financial goals gradually. However, like any investment strategy and approach, it is important for investors considering this option first to carry out due diligence and research before committing themselves fully.