“Snowball Your Way to Debt Freedom: Experts Share Tips on the Debt Snowball Method”
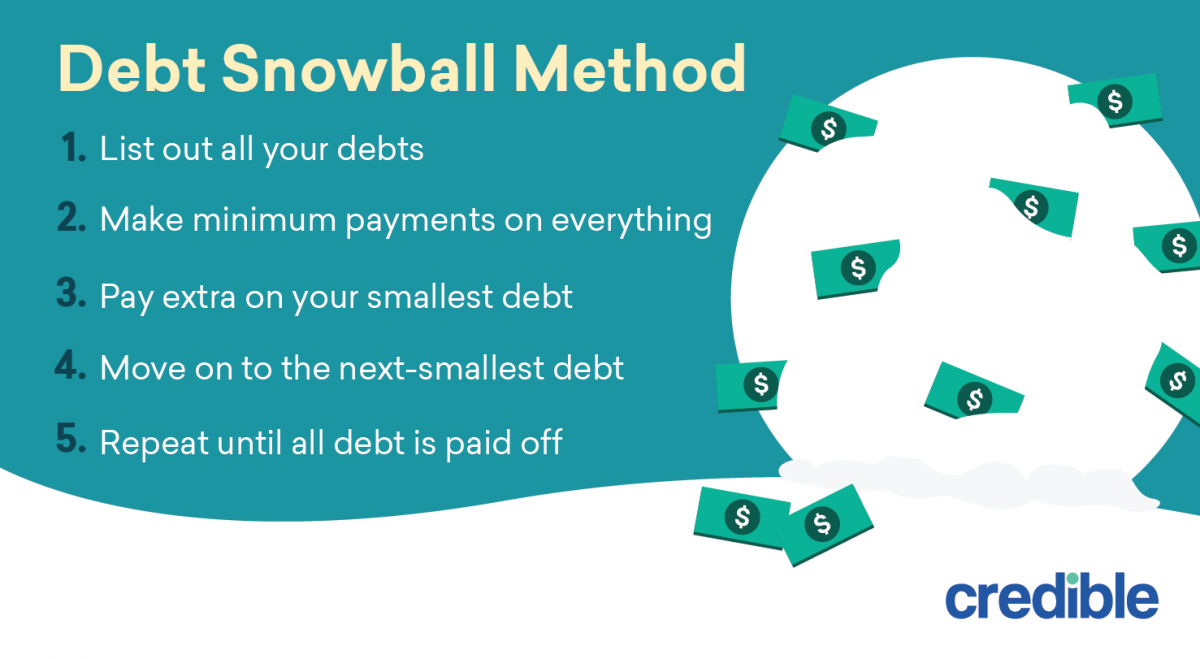
Panel Discussion: The Debt Snowball Method
Welcome to our panel discussion on the debt snowball method! Today, we have three experts in personal finance who will share their thoughts and experiences on this popular strategy for paying off debt.
First, let’s define what the debt snowball method is. This approach involves listing all of your debts from smallest to largest balance and focusing on paying off the smallest one first while making minimum payments on the others. Once you’ve paid off that first debt, you move onto the next smallest one and so forth until all of your debts are paid in full.
Our first expert is Jane Smith, a financial coach with over 10 years of experience helping people manage their money. Jane, can you tell us why the debt snowball method works?
Jane: Absolutely! The reason it’s effective is because it gives people a sense of accomplishment early on in the process. When they see that first small debt get paid off quickly, it motivates them to keep going and tackle larger debts. It also simplifies things by focusing on one debt at a time rather than feeling overwhelmed by multiple balances.
Next up is John Doe, a personal finance blogger with a strong following online. John, have you seen any downsides to using the debt snowball method?
John: While I generally think it’s a great strategy for many people, there are some potential drawbacks to consider as well. For example, if someone has high-interest credit card balances but chooses to pay off lower-interest student loans or car loans first just because they’re smaller balances, they could end up paying more interest overall in the long run.
Finally, we have Sarah Lee who works as an accountant for a large corporation and has helped many employees improve their finances through workshops and counseling sessions. Sarah, do you have any tips for using the debt snowball method effectively?
Sarah: Yes! One thing I always recommend is being intentional about where any extra money comes from. This could mean taking on a part-time job, selling unused items around the house, or even using your tax refund to pay down debt. Also, don’t forget to negotiate with creditors if you’re struggling to make payments – they may be willing to work out a payment plan or settle for less than what’s owed.
Thank you all for sharing your insights on the debt snowball method! As our experts have shown, it can be a powerful tool for getting out of debt and achieving financial freedom.