Unlock Your Home’s Equity with a Reverse Mortgage
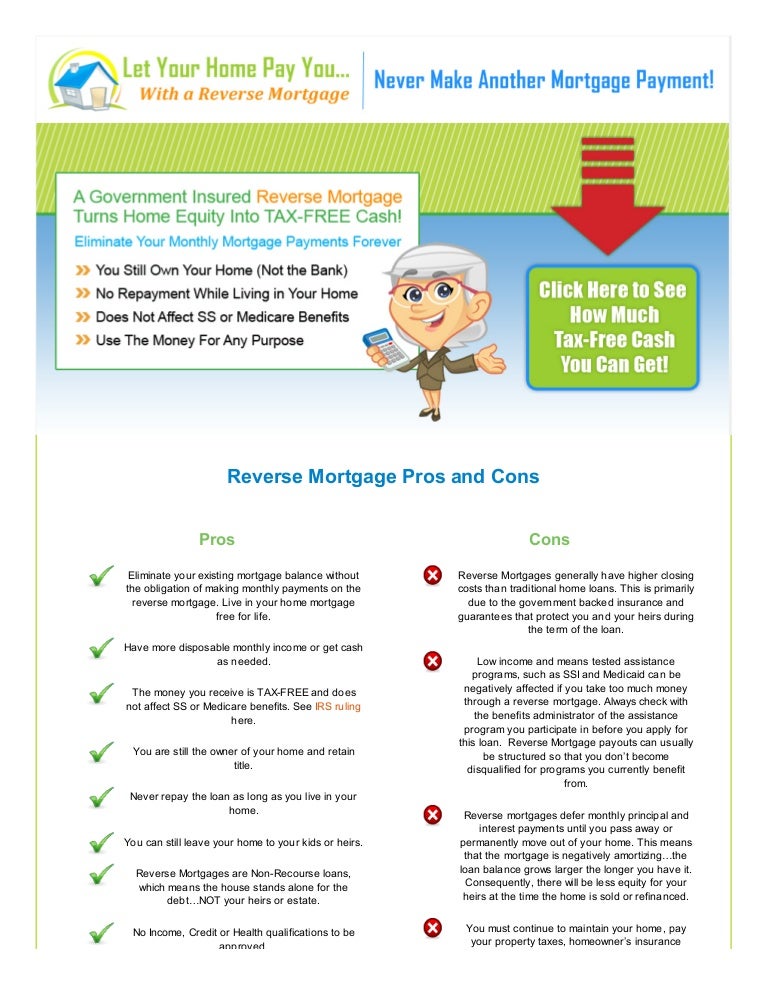
Reverse Mortgages: An Overview
Reverse mortgages are a type of home loan that can be an attractive option for older adults who need access to additional funds. However, like any financial product, it’s important to understand how they work and the potential benefits and drawbacks before deciding whether or not to pursue one.
What is a Reverse Mortgage?
A reverse mortgage is a loan that allows homeowners aged 62 or older to convert some of their home equity into cash. Unlike traditional mortgages where you make monthly payments towards paying off the loan, with a reverse mortgage the lender pays you instead. The amount you receive depends on your age, the value of your home, current interest rates, and other factors.
The loan doesn’t have to be repaid until you sell your home or pass away. At that point, if there is still equity left in the property after paying off the outstanding balance on the reverse mortgage and any other liens on the property, it goes to you (or your heirs).
Types of Reverse Mortgages
There are three main types of reverse mortgages available:
1. Home Equity Conversion Mortgage (HECM): This is the most common type of reverse mortgage backed by the Federal Housing Administration (FHA). It has no income requirements but does require borrowers to undergo counseling from an approved agency before applying.
2. Proprietary Reverse Mortgage: These are private loans offered by lenders that aren’t insured by FHA. They may offer higher borrowing limits than HECMs but also come with stricter underwriting standards.
3. Single-Purpose Reverse Mortgage: These are offered by state and local government agencies as well as non-profit organizations for specific purposes such as making repairs or improvements to a property.
How Much Money Can You Get With a Reverse Mortgage?
The amount you can borrow with a reverse mortgage depends on several factors including:
– Age: Typically, older borrowers can qualify for larger loans.
– Home Value: The more valuable your home is, the more you’ll be able to borrow.
– Interest Rates: The higher the interest rate on your loan, the less money you can receive.
– Loan Limits: There are limits on how much you can borrow with a reverse mortgage that vary by location.
Generally speaking, borrowers can expect to receive anywhere from 30% to 60% of their home’s value in a lump sum or as monthly payments. Additionally, there may be fees associated with taking out a reverse mortgage including origination fees, closing costs and ongoing service fees.
Pros and Cons of Reverse Mortgages
As with any financial product, there are both benefits and drawbacks associated with reverse mortgages. Some potential pros include:
– Access to additional funds: Reverse mortgages provide homeowners with the ability to tap into their home equity without having to sell their property.
– No monthly payments required: With a reverse mortgage, borrowers don’t have to make monthly payments towards paying off the loan while they’re still living in the house.
– Flexibility in how funds are used: Borrowers can use the funds for anything they choose such as paying off debt or covering medical expenses.
However, there are also some potential cons including:
– High fees: Reverse mortgages tend to come with higher upfront costs than traditional loans which can eat into any equity gained from borrowing against your property.
– Complicated terms and conditions: Reverse mortgages can be confusing due to their unique structure so it’s important for borrowers to understand what they’re getting into before deciding whether or not it’s right for them.
– Reduced inheritance amount for heirs: If you pass away before repaying your reverse mortgage balance (or if you need long-term care), there may not be much (if any) equity left in your home for your heirs once everything is settled.
Is a Reverse Mortgage Right For You?
Whether or not a reverse mortgage makes sense depends on individual circumstances. If you’re considering one, it’s important to talk with a qualified financial advisor who can help you weigh the pros and cons. Additionally, be sure to shop around and compare lenders as rates and fees can vary greatly.
In conclusion, reverse mortgages are a valuable tool for some older adults but they’re not right for everyone. Make sure you understand all of the factors involved before making any decisions about whether or not one is right for your situation.