Don’t Forget About Required Minimum Distributions When Planning for Retirement
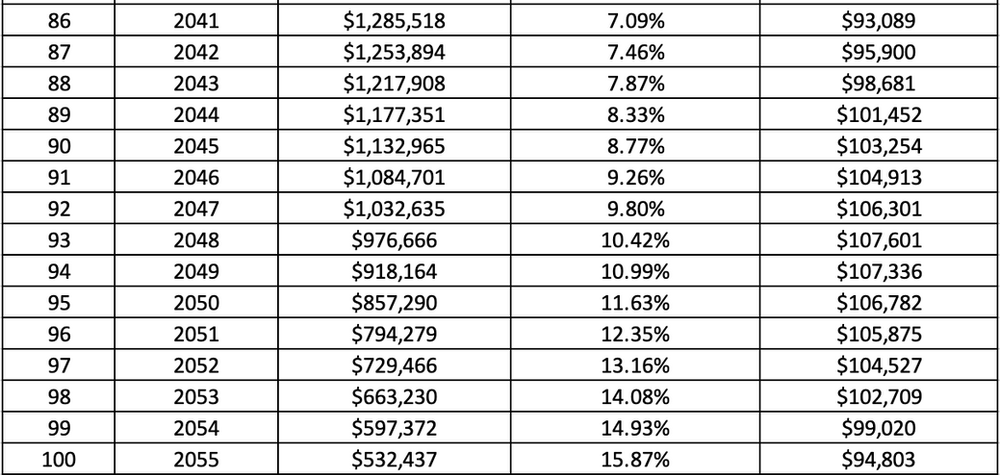
As we age, it’s important to consider how our retirement savings will last for the remainder of our lives. One aspect that should not be overlooked is Required Minimum Distributions (RMDs).
What are RMDs? They are the minimum amount of money a retiree must withdraw from their retirement accounts each year once they reach age 72 (or 70½ if you were born before July 1, 1949). These accounts include traditional IRAs, SEP IRAs, SIMPLE IRAs, and employer-sponsored plans such as 401(k)s.
The purpose of RMDs is to ensure that retirees don’t leave all their funds in these tax-deferred accounts indefinitely and avoid paying taxes on them. The IRS requires these withdrawals so that they can collect taxes on the withdrawn amounts.
Calculating your RMD can be tricky but it’s important to do so correctly or face significant penalties. The formula used takes into account your life expectancy and account balance at the end of the previous year. Your financial institution will usually calculate this for you but it’s ultimately your responsibility to ensure that you’re withdrawing enough each year.
It’s worth noting that Roth IRA owners are exempt from having to take RMDs throughout their lifetime since contributions were made with after-tax dollars. However, beneficiaries inheriting a Roth IRA must take distributions based on certain rules set by the IRS.
When do you need to start taking RMDs? Usually, April 1st following the year in which you turn age 72 (or age 70½ if born before July 1, 1949) is when most people begin taking their first RMD. If you wait until April 1st though, then there will be two distributions due in one calendar year which could result in higher taxable income and push you into a higher tax bracket. Subsequent years’ distributions will have to be taken by December 31st each year.
Missing the RMD deadline can result in hefty penalties. The penalty for not taking an RMD is 50% of the amount that should have been withdrawn. For example, if your RMD was supposed to be $10,000 but you only withdrew $5,000, then you would owe a penalty of $2,500 ($5,000 x 50%).
If you have multiple retirement accounts, it’s important to make sure that each account has its own RMD calculation and distribution. You’re not allowed to aggregate them into one lump sum and take the distribution from just one account.
As with most financial matters related to retirement planning, there are exceptions and special circumstances when it comes to Required Minimum Distributions:
– If you continue working past age 72 (or age 70½ if born before July 1, 1949), you may be able to delay taking distributions from your employer-sponsored plan until after you retire.
– If you inherit an IRA or other qualified retirement plan as a non-spouse beneficiary (such as a child), then different rules apply regarding when and how much must be distributed.
– If your spouse is more than ten years younger than you and is named as the sole beneficiary on any of your qualified plans or IRAs then different rules also apply which allow for smaller RMDs.
– In light of COVID-19 pandemic relief measures taken by Congress in March of this year via the CARES Act legislation signed into law by President Trump these changes need to be noted:
– Special relief provision stating that no one is required to take their first withdrawal during calendar year 2020
– Anyone who already took their first withdrawal between January 1st – May15th has until August31ststo put back what they took out
– Finally any withdrawals made during this period will utilize a larger portion towards principal repayment rather than interest payment
Remember, RMDs are an important part of retirement planning and should be taken seriously. Failing to take the required amount or missing the deadline entirely can result in significant penalties. Talk with a financial advisor to ensure you’re taking your RMDs correctly and on time.