Navigating Retirement Account Rollovers and Transfers: Understanding the Tax Implications
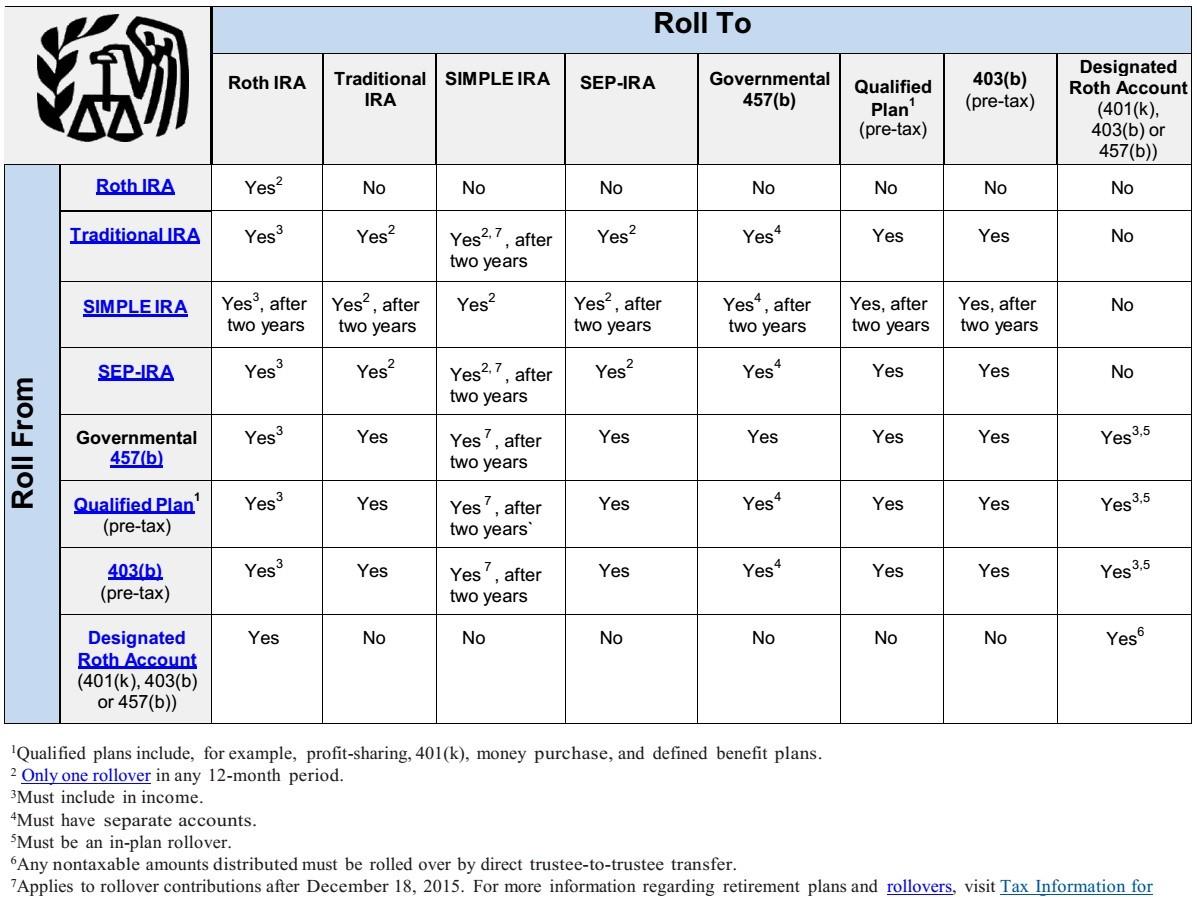
When it comes to retirement planning, many people find themselves with multiple accounts over the course of their career. It’s not uncommon for someone to have a 401(k) from an old job, an IRA they opened on their own, and a current employer-sponsored plan.
As you near retirement age or simply want to consolidate your accounts, you may consider rolling over or transferring funds between these different types of accounts. But before you make any moves, it’s important to understand the tax implications involved.
Rollovers vs. Transfers
First things first: what’s the difference between a rollover and a transfer? While both involve moving money from one account to another, there are some key distinctions:
– A rollover typically involves withdrawing funds from one account and depositing them into another within 60 days. This requires you to handle the money yourself (though some institutions will send a check directly to your new account), and if not done properly can result in penalties or taxes owed.
– A transfer involves moving funds directly from one institution to another without ever touching the money yourself. There is no time limit on completing a transfer, but there may be fees involved depending on your specific situation.
Now that we’ve got that cleared up, let’s dive into how each of these actions could affect your taxes.
Rollovers
If you’re considering rolling over funds from one type of retirement account (such as a 401(k)) into another (like an IRA), it’s important to understand how this will impact your taxes.
First off, make sure that your target account is eligible for rollovers – not all plans are created equal! You’ll also want to ensure that you follow all necessary steps in order for the transaction to count as a legitimate rollover – ask both institutions for guidance if needed.
Assuming everything goes smoothly with the rollover itself, here are some tax implications you should be aware of:
– No taxes are owed on the rollover itself – as long as you complete it within 60 days and follow all rules, moving money from one retirement account to another won’t trigger any immediate tax bills.
– Rollovers can impact your future tax situation – once funds have been moved into an IRA, for example, they’ll be subject to different rules and regulations than a 401(k). This could affect things like required minimum distributions (RMDs) in the future.
– Roth conversions can be complicated – if you’re considering rolling over pre-tax funds into a Roth IRA (which is funded with after-tax dollars), things get even more complex. You’ll owe taxes on the converted amount in the year of the conversion, which could result in a higher-than-usual tax bill.
Transfers
While transfers don’t involve taxable events themselves, there are still some important considerations to keep in mind when moving money between accounts:
– Fees may apply – some institutions charge transfer fees when you move funds out of their plan. Make sure you understand any costs involved before initiating a transfer.
– Transfers can help avoid penalties – if you have multiple retirement accounts but don’t want to withdraw from one in order to contribute to another, transferring funds directly can help avoid early withdrawal penalties or contribution limits.
– Be aware of potential investment changes – depending on what types of plans you’re transferring between and what investments each offers, your transferred funds may need to be reallocated or reinvested. Keep this in mind when planning your overall portfolio strategy.
Other Considerations
In addition to these specific tax implications around rollovers and transfers, there are other factors that could impact how much you owe come tax time:
– If you roll over pre-tax funds into an IRA but then later withdraw from that account before age 59 1/2, those withdrawals will generally be subject to income taxes plus a 10% penalty (unless you qualify for an exception). Keep this in mind if you’re considering a rollover as a way to access funds early.
– If you transfer funds directly from one IRA to another and hold those accounts at different institutions, make sure the institution sending the money knows that it’s not a taxable event. Otherwise, they may withhold taxes from your distribution that will need to be reconciled later on your tax return.
– Finally, remember that there are limits on how much you can contribute to different types of retirement accounts each year. Make sure you understand these rules before making any moves with your existing accounts.
Overall, rolling over or transferring retirement account funds can be a great way to consolidate your savings or take advantage of different investment options. Just make sure you understand all of the tax implications involved so that there are no surprises come April 15th!