“Reach Your Financial Dreams: A Guide to Effective Goal Setting”
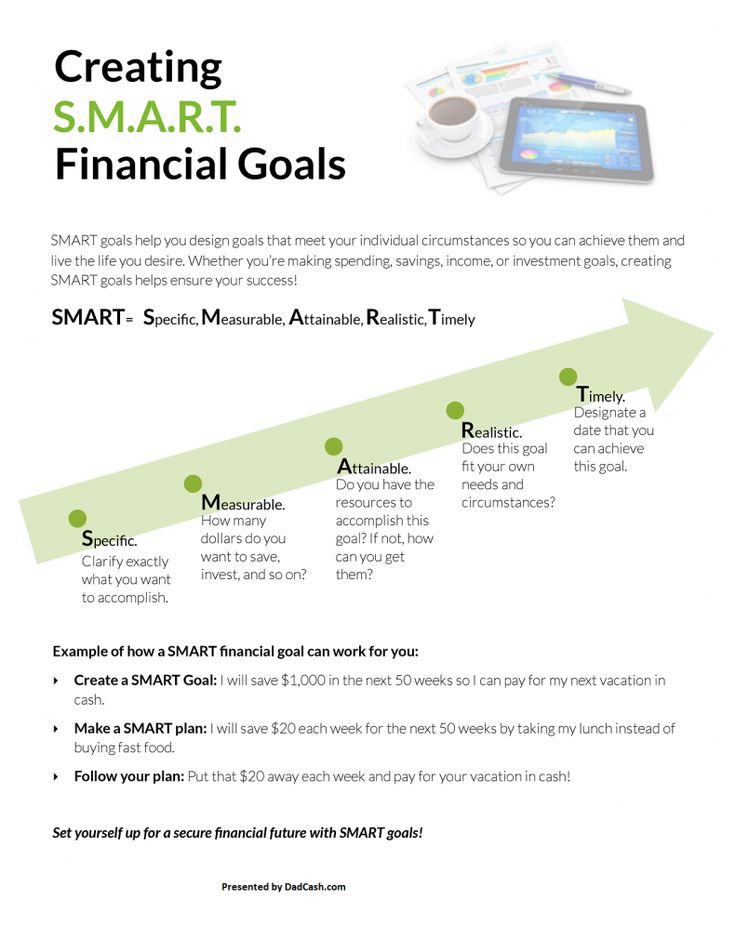
Financial Goal Setting: A Guide to Achieving Your Dreams
Everyone has financial goals, whether it’s saving up for a down payment on a house, paying off debt, or retiring comfortably. The key to achieving these goals is setting them in the first place and having a plan of action to reach them.
Here are some tips for effective financial goal setting:
1. Identify your priorities
Before you can set specific financial goals, it’s important to understand what your priorities are and what you want out of life. This will help guide your decisions when it comes to money.
Make a list of things that matter most to you – this might include family, travel, career advancement or personal development. Once you know what’s important to you, you can start setting financial goals that align with those values.
2. Set SMART goals
SMART stands for Specific, Measurable, Achievable, Relevant and Time-bound – these are the characteristics of effective goal-setting.
Specific: Instead of saying “I want to save more money,” be specific about how much money you want to save (e.g., $10k).
Measurable: Make sure your goal is measurable so that you can track progress over time (e.g., saving $500 per month).
Achievable: While it’s great to have big dreams and ambitions when it comes to finances, make sure your goals are realistic so that they’re attainable within the timeframe given.
Relevant: Ensure that each goal aligns with your overall financial priorities and values; otherwise achieving them may not bring satisfaction in the long-term.
Time-bound: Give yourself a deadline so that there’s an endpoint in sight (e.g., “I want to pay off my student loans in 3 years”).
Examples:
– Pay off $5k credit card debt within 12 months.
– Save $20k for emergency fund by end of next year.
– Increase retirement savings contributions by 5% this year.
3. Break down larger goals into smaller ones
When it comes to bigger financial goals (like paying off a mortgage), it can be helpful to break them down into smaller, more manageable chunks. This makes the goal less daunting and allows you to track progress along the way.
For example, if your goal is to pay off a $200k mortgage in 20 years, that translates to around $10k per year or ~$833 per month. Breaking this goal down further means saving roughly $208 per week – which feels much more achievable.
4. Be realistic about timelines
It’s important not only to set achievable goals but also realistic timelines for achieving them. If you’re saving for a large expense like a house or car, it might take longer than expected; so give yourself plenty of time and don’t beat yourself up if you fall behind schedule – just keep pushing forward!
5. Review your progress regularly
Regularly reviewing your financial situation helps keep you on track towards achieving your goals – otherwise there’s no way of knowing how close (or far) you are from reaching them!
Create a routine where you check on progress at regular intervals: weekly, monthly or quarterly depending on what works best for each specific goal.
6. Stay disciplined
Achieving any worthwhile objective requires discipline and commitment; sticking to the plan even when things get challenging is crucial.
But remember that setbacks happen – they’re normal! The key is learning from mistakes and getting back on track as soon as possible.
In conclusion, setting effective financial goals is critical for achieving long-term success with money management.
By following these tips outlined above- prioritizing values/priorities first before setting SMART objectives that are broken down into smaller steps while keeping realistic timelines in mind- anyone can achieve their dreams with discipline and perseverance!
So go ahead – start planning today by making actionable steps towards fulfilling those aspirations one by one until you finally achieve the financial freedom that you’ve always wanted.