Mastering Interest Rates: Tips for Managing Your Personal Finances
Interest Rates: Understanding the Impact on Your Personal Finances
Interest rates are a crucial aspect of personal finance that affects every aspect of our lives. They determine how much we pay for borrowing money, including credit card debts, mortgages, and auto loans. Interest rates also influence savings accounts and investment vehicles like bonds, stocks, and mutual funds.
In this article, we will discuss everything you need to know about interest rates so that you can make informed financial decisions.
What are Interest Rates?
An interest rate is the amount charged by a lender to a borrower for using their money. It is expressed as an annual percentage of the borrowed amount (principal). For instance, if you borrow $10,000 at 5% interest rate for one year, you will be required to repay $10,500 at the end of that period.
The Federal Reserve (Fed) sets monetary policy in the United States and regulates interest rates. The Fed uses two main tools to control the economy – open market operations and adjusting reserve requirements.
When there’s inflation in an economy or too much growth leading to excessive borrowing and spending; the Fed increases interest rates to reduce spending power which slows down economic activity. On the other hand when there’s insufficient demand for goods or services leading to low employment levels; they lower it as a way of spurring economic growth by encouraging people/businesses to borrow more at cheaper costs.
Types of Interest Rates
There are two types of interest rates: fixed-rate and variable-rate:
Fixed-Rate: A fixed-rate loan has an annual percentage rate (APR) that remains constant throughout its life. This means your payments stay consistent throughout your loan term regardless of economic changes which can help with budgeting because it allows you predict what your monthly payment amounts would look like over time. Fixed-rates are generally higher than variable-rates since they offer guaranteed stability although both have their respective advantages depending on individual needs/timing.
Variable-Rate: A variable-rate loan, also known as an adjustable rate loan, has an APR that fluctuates depending on the current market conditions. This means your payments can vary and are subject to change monthly or quarterly. Variable rates may be lower than fixed rates at first but could rise later, making it a riskier option for those who need stability in their budgets.
How Interest Rates Affect Your Personal Finances
Interest rates can have significant impacts on your personal finances:
Credit Card Debt: Credit card interest rates tend to be high compared to other forms of credit such as auto loans or mortgages because they’re unsecured debts which makes them a higher risk for lenders. If you carry a balance from month-to-month; interest cost will accumulate quickly and end up costing you more money over time.
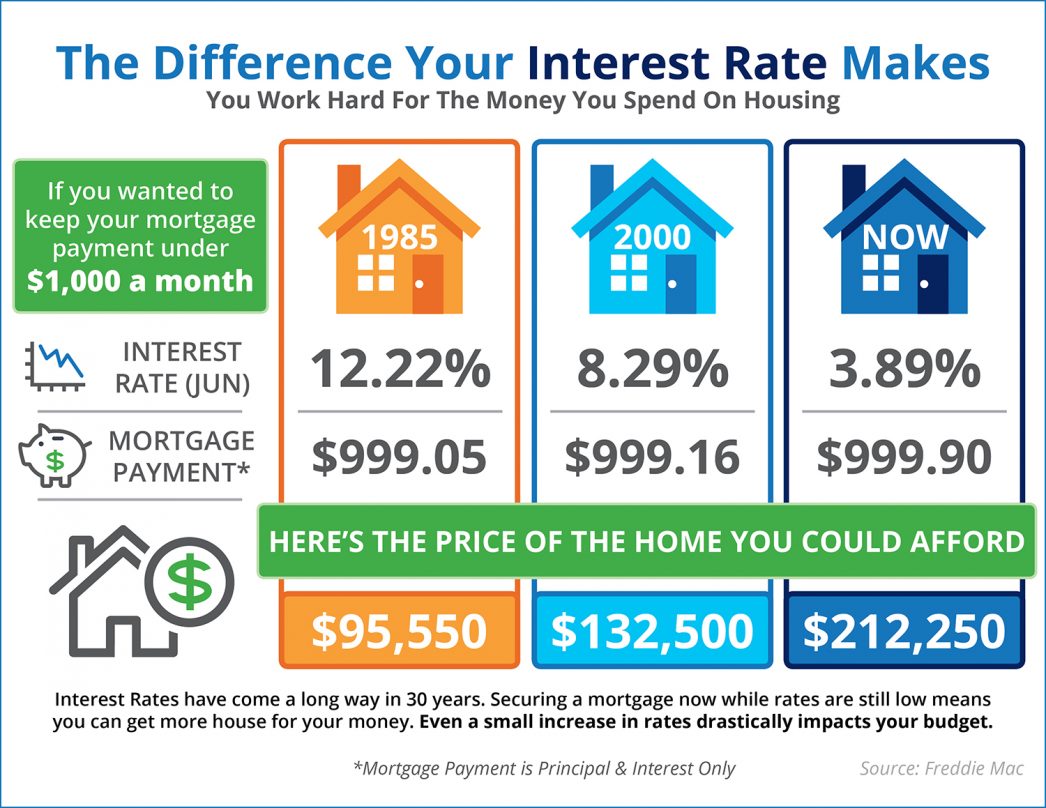
Mortgage Loans: Interest rates influence mortgage affordability. When interest rates are low, mortgage payments become cheaper; this could make homeownership more affordable for many individuals. In contrast, when interest rates are high, homebuyers’ purchasing power reduces since they must pay higher monthly installments resulting in fewer people being able to afford homes.
Savings Accounts: Interest paid on savings accounts tends to be low in today’s economy due largely because of low-interest rates set by the Federal Reserve (Fed). However some financial institutions offer competitive APYs (annual percentage yield) which can help savers earn more money with less effort/time invested into finding a good account!
Investment Vehicles: Bonds, stocks and mutual funds all have varying levels of correlation with changes in interest rates although bonds are considered most sensitive given how bond prices move inversely with changes in prevailing yields. Generally speaking though rising interest rate environments often lead investors towards safer assets like bonds while lowering ones may push stock prices higher due partly because it becomes easier/cheaper for businesses to borrow/use capital.
Tips for Managing Interest Rates
Here are some tips for managing your interest rates:
– Pay down debts with high-interest rates first. This will help reduce the amount of interest you pay over time.
– Consider refinancing debt to lower interest rates on loans such as mortgages or student loans.
– Shop around for savings accounts offering higher APYs so that your money can earn more over time without taking any additional risks!
– Understand how changes in interest rates can affect your investment portfolio and adjust accordingly (e.g., consider bonds during high-interest rate environments).
Conclusion
Interest rates are a crucial aspect of personal finance, influencing borrowing costs, savings returns, and investments. While they’re largely determined by monetary policy set by the Federal Reserve; there are steps you can take to manage them effectively including paying off debt with high-interest rates first, shopping around for competitive savings account APYs and understanding how different asset classes behave under varying market conditions!