Maximizing Net Capital Loss Deductions: A Guide for Taxpayers
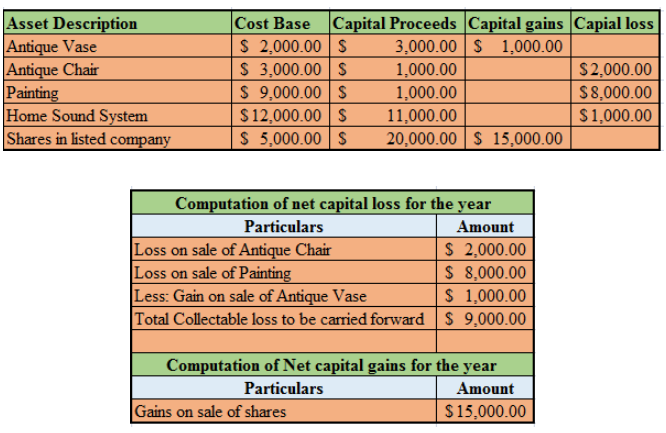
As a taxpayer, you know that filing your taxes can be quite the ordeal. With so many rules and regulations to follow, it can be tough to ensure that you’re not missing anything important. One area where taxpayers often get confused is with net capital loss deductions.
Net capital losses occur when your total capital losses exceed your total capital gains for the year. This can happen if you sold stocks or other investments at a loss during the year. The good news is that you may be able to claim a deduction for these losses on your tax return.
In this post, we’ll take a closer look at net capital loss deductions and what they mean for your tax return.
What are Capital Gains and Losses?
First, let’s define some terms. A capital gain occurs when you sell an asset (like stock or real estate) for more than what you paid for it. For example, if you bought 100 shares of XYZ Company stock for $10 per share and later sold those shares for $15 per share, you would have a $500 ($15 – $10 x 100)capital gain.
A capital loss occurs when you sell an asset for less than what you paid for it. Using our example above, if instead of selling those shares of XYZ company stock at $15 per share, they were only worth $7 per share when sold then there would be a $300 ($7 – $10×100)capital loss incurred.
When calculating your overall gain or loss from investments in any given year all gains must first be offset by any related costs such as transaction fees etc before being compared against any losses in order to calculate whether there has been an overall gain or loss in the portfolio over the course of that period.
What is Net Capital Loss?
If after careful calculation of all profits made through investments including their respective costs/expenses plus all related loses one finds out that they have lost more money than gained in a given year, then the difference between those amounts is what’s known as the net capital loss.
What are Net Capital Loss Deductions?
If you have incurred a net capital loss for the year, you may be able to claim a deduction on your tax return. In simple terms, this implies that any losses made during the course of investing can be deducted from gains when calculating overall taxable income.
There are some rules and limitations to keep in mind when claiming these deductions:
1. Only capital losses can be used to offset capital gains. You cannot use other types of losses (like business or rental property losses) to offset your capital gains.
2. If you have more capital losses than capital gains for the year, you can deduct up to $3,000 of those excess losses against your ordinary income.
3. If you still have excess net capital losses after taking into account step 2 above then it becomes necessary that it gets carried over into future tax periods until such time as they get used up by either being totally absorbed through future profits or simply expire after having been unused for decades.
How do Net Capital Loss Deductions Work?
Let’s say you had $10,000 in long-term capital gains and $15,000 in long-term capital losses during the year. This means that you would have a net long-term loss of $5,000 ($15,000 – $10,000 = -$5,000).
Since this is a net loss situation which exceeds any gain made over that period by at least $3000 rule number two applies and thus one may only deduct upto $3000 worth of loses from their ordinary income while carrying forward remaining amount i.e.,$2000 (i.e.$5000-$3000=$2000)to future years.
If instead we had 20k total realized loses with no overall gain then all 20k could be written off against regular earned income taxes.
It’s important to remember that you must report all capital gains and losses on your tax return, even if you’re not able to claim a deduction for them in the current year. This will ensure that any unused losses can be carried forward to future years when they may be needed.
Conclusion
Net capital loss deductions are an important part of the tax code for investors. By understanding how these deductions work, you can take advantage of them and potentially reduce your overall tax liability.
If you have incurred capital losses during the year, it’s important to talk with a qualified tax professional who can help you navigate the rules and regulations surrounding net capital loss deductions. With their help, you can maximize your deductions and minimize your overall tax burden.