Maximizing Your Construction Loan: Understanding Amortization Schedules
When it comes to financing a construction project, there are many options available. One of the most common is a construction loan. This type of loan is designed specifically for building projects and can help you finance everything from the land purchase to the final touches on your new home or commercial property.
One important aspect of any loan is its amortization schedule. An amortization schedule outlines how much you will pay each month and how that payment is divided between interest and principal. Understanding how your construction loan’s amortization works can help you plan your finances more effectively, avoid surprises down the road, and potentially save money in interest payments.
Construction loans typically have two phases: the draw period and the repayment period. During the draw period, which usually lasts anywhere from six months to a year or more, you can withdraw funds as needed to pay for various aspects of your construction project (such as materials, labor costs, permits, etc.). The lender will likely require some documentation before releasing funds, such as invoices or receipts from contractors.
During this phase, you may only be required to make interest-only payments on what you’ve borrowed so far. This means that none of your payments go toward paying down the principal balance of the loan – they only cover the interest charged by the lender.
Once construction is complete (or nearly so), your loan enters into its repayment phase. At this point, your monthly payments will start covering both principal and interest charges over a set period of time – typically 15-30 years for residential mortgages or up to 10 years for commercial properties.
The exact terms of your repayment schedule will depend on several factors specific to your situation:
Loan term: How long do you want/need to take out this loan? Longer-term loans generally come with lower monthly payments but higher overall interest costs due to accruing over an extended period.
Interest rate: What’s being charged in order for lenders’ funding risk taken care? Interest rates will also affect your monthly payment amounts and overall loan costs.
Down payment: Some lenders may require a down payment for construction loans, which can lower the principal balance of your loan and therefore lead to lower monthly payments.
Loan amount: The total amount you borrow will also impact your monthly payments. Higher loan amounts generally result in higher payments.
Payment schedule: You can choose between several different repayment options, including fixed-rate (where the interest rate remains the same throughout the life of the loan) or adjustable-rate (where rates change over time). Additionally, some loans allow for bi-weekly or even weekly payments instead of monthly ones.
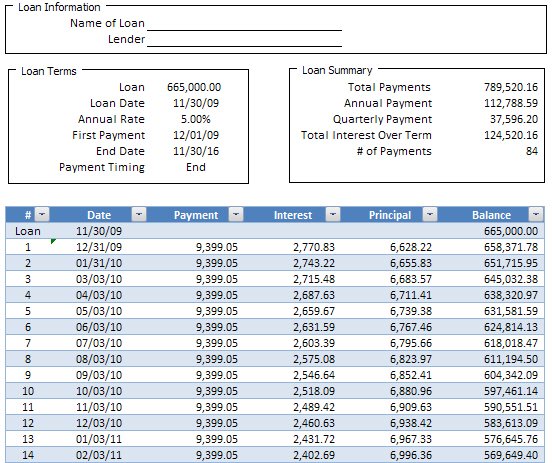
Once you’ve settled on these terms with your lender, they’ll create an amortization schedule that outlines how much money you’ll owe each month and how it’s divided between interest charges and principal repayments. This is a critical document because it shows exactly when each payment is due and what portion of that payment goes toward reducing your outstanding balance.
Construction loan amortization schedules typically have two parts:
Draw period: During this phase, as mentioned earlier, you’re only required to make interest-only payments on what you’ve borrowed so far. Your amortization schedule during this time will show only those interest charges. Note that if you don’t use all the funds available to you during this period – perhaps because construction went more smoothly than anticipated – then you won’t owe any additional interest charges on unused funds since they were never disbursed.
Repayment period: Once construction is complete (or nearly so), your loan enters into its repayment phase. At this point, your monthly payments will start covering both principal and interest charges over a set period of time – typically 15-30 years for residential mortgages or up to 10 years for commercial properties.
Your amortization schedule during this phase will show how much of each payment goes toward paying down principal versus paying off accrued interest. Typically at first very little goes toward the principal, since most of your payment is needed to pay off interest charges that have been building up over the course of construction.
However, as time goes on and more payments are made, a larger portion of each payment will go toward reducing the principal balance. This means you’ll owe less in interest charges over time and may be able to pay off your loan faster than if you only made minimum payments.
It’s also worth noting that some lenders may offer various options for accelerating your amortization schedule. For example, you might be able to make extra payments (either monthly or as lump sums) toward your principal balance without incurring prepayment penalties; this can help reduce overall interest costs and speed up debt repayment.
Overall, understanding how construction loan amortization works is an essential part of planning any building project. By working with a reputable lender and carefully reviewing your loan terms before signing any paperwork, you’ll be better equipped to manage your finances effectively while securing funding for all aspects of construction – from land acquisition to final touches.