Don’t Miss Out on Savings: Stay Informed About Contribution Deadlines
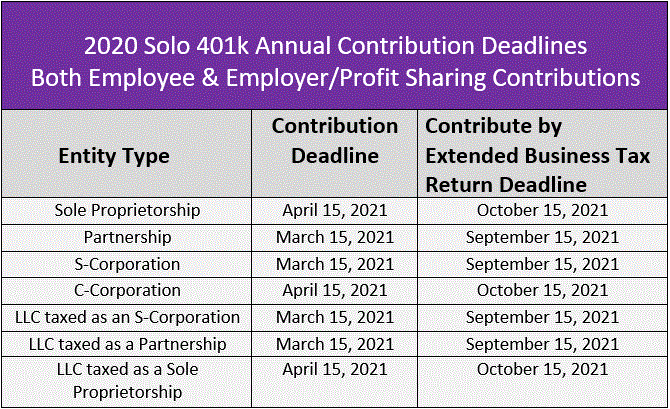
Contribution Deadlines: What You Need to Know
If you’ve ever contributed to a retirement account or an investment portfolio, you know that there are certain deadlines that must be met. These deadlines can vary depending on the type of contribution and the type of account, so it’s important to stay informed in order to avoid any penalties or missed opportunities.
One of the most common types of contributions is made to an individual retirement account (IRA). For traditional IRAs, contributions for each tax year can be made up until the tax filing deadline for that year. This means that for 2021 taxes, contributions can be made up until April 15th, 2022. However, for Roth IRAs, contributions must be made by the tax filing deadline for each year – meaning April 15th of that same year.
For employer-sponsored retirement accounts like a 401(k) or a SIMPLE IRA plan, contributions are typically deducted from your paycheck and therefore have different deadlines. Generally speaking, these types of accounts require contributions to be made by December 31st in order to count towards that calendar year’s total contribution limit.
It’s also important to note that some types of contributions come with additional requirements or restrictions. For example, if you’re over age 50 and want to make catch-up contributions in addition to your regular contribution limit for an IRA or employer-sponsored plan, those additional funds must generally be deposited by the end of the calendar year.
In addition to retirement accounts, there may also be contribution deadlines associated with other types of investments such as college savings plans (529s) or health savings accounts (HSAs). These deadlines will vary based on state regulations and other factors but should always be carefully considered when planning your financial strategy.
Finally, it’s worth noting that missing a contribution deadline can have serious consequences. Depending on the situation and type of account involved, missed deadlines could result in lost opportunities for tax deductions or matching contributions, as well as potential penalties and fees.
In conclusion, staying on top of contribution deadlines is an essential part of managing your finances and planning for the future. Whether you’re contributing to a retirement account or other investment vehicle, taking the time to understand the requirements and deadlines involved can help ensure that you maximize your savings potential while avoiding any unnecessary pitfalls.