Mastering Your Mortgage: Understanding Principal Balance and Saving Money
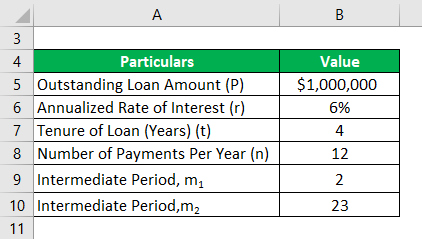
Mortgage Principal Balance: Understanding Your Loan
If you own a home, chances are you have a mortgage. A mortgage is a loan that is used to purchase or refinance a property. When you take out a mortgage, the amount of money that you borrow is called the principal.
The principal balance on your mortgage refers to the outstanding amount of your loan that has not yet been repaid. As you make payments over time, part of each payment goes towards paying down the principal balance.
Understanding how your mortgage works and what impacts your principal balance can help you make informed financial decisions and potentially save money in interest charges.
How Payments Affect Your Principal Balance
When you make a monthly payment on your mortgage, it typically consists of two parts: principal and interest. The amount of each payment that goes towards paying down the principal balance depends on several factors including:
– The size of your monthly payment
– The interest rate on your loan
– The length of your loan term
– Any additional payments made towards the principal
Generally speaking, larger monthly payments will result in more money going towards paying down the principal balance. Similarly, making extra payments beyond what’s required can also help reduce your overall debt faster.
However, keep in mind that some mortgages may charge prepayment penalties for early repayment or have restrictions on how much extra can be paid per year without penalty fees.
Refinancing Your Mortgage
One way to change your mortgage’s terms and impact its principle balance is through refinancing. Refinancing involves taking out a new loan with different terms than an existing one.
For example, if interest rates have dropped since you first took out your original loan then refinancing could potentially lower both future monthly payments and total amounts owed by reducing total interest costs as well as reduce principle balances faster due to higher percentage allocations toward principle due to lower overall cost allocation toward interests between payoff periods.
Finally…
In conclusion, understanding how your mortgage principal balance works and what impacts it can help you make informed financial decisions. By making larger monthly payments, paying down extra principal when possible, or refinancing to lower interest rates, you can potentially save money and pay off your loan faster.