Avoiding Prohibited Transactions and Disqualified Persons: The Key to Maximizing Your IRA Benefits
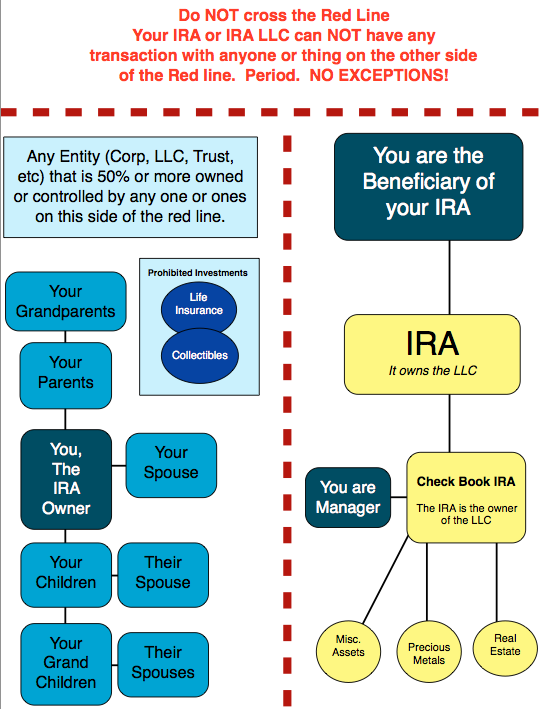
When it comes to individual retirement accounts (IRAs), there are certain rules and regulations that must be followed. One of the most important things to keep in mind is that there are prohibited transactions and disqualified persons, which can have serious consequences if not handled properly.
Prohibited Transactions
A prohibited transaction is any improper use of an IRA account by the account owner or a related party. These types of transactions are strictly forbidden by the Internal Revenue Service (IRS) and can result in severe tax penalties, including loss of tax-deferred status for the entire IRA account.
Some examples of prohibited transactions include:
1. Self-Dealing: This occurs when an IRA owner uses their account for personal gain rather than for retirement savings purposes. For example, if you purchase property with your IRA funds and then rent it out to yourself or a family member, this would be considered self-dealing.
2. Purchasing Prohibited Assets: Certain assets are off-limits when it comes to investing with an IRA, such as life insurance policies or collectibles like artwork or antiques.
3. Co-Mingling Funds: It’s important to keep your IRA funds separate from other personal accounts because co-mingling them could lead to confusion about what money belongs where.
4. Borrowing Money: You cannot borrow money from your IRA account or use it as collateral for a loan.
5. Providing Services: If you provide services to your own IRA, such as acting as a property manager for rental properties held within the account, this would also be considered a prohibited transaction.
Disqualified Persons
In addition to avoiding prohibited transactions within your own IRAs, you must also avoid engaging in certain activities with disqualified persons – individuals who have close relationships with you or control over your finances. Disqualified persons include:
1. Your Spouse: Even though spouses typically share financial decisions and responsibilities together, they’re still classified as disqualified persons according to IRS regulations.
2. Your Lineal Descendants: This includes your children, grandchildren, and great-grandchildren.
3. Service Providers: Accountants, lawyers, and financial advisers who provide services to your IRA account may be considered disqualified persons if they have decision-making power over the account’s investments.
4. Business Partners: Anyone you own a business with or engage in financial transactions with are also disqualified persons.
5. Fiduciaries: If an individual has the authority to make decisions regarding your IRA account’s investments or distributions, they would be considered a fiduciary and therefore a disqualified person as well.
The consequences of engaging in prohibited transactions or dealing with disqualified persons can be severe. The most significant penalty is losing tax-deferred status for the entire IRA account balance, which could result in thousands of dollars in taxes owed to the government. In addition, there could be additional penalties assessed by the IRS depending on the severity of the violation.
To avoid these issues altogether, it’s important to work closely with an experienced financial advisor who understands IRA regulations and can help guide you through any potential pitfalls that might arise along the way.
Tips for Avoiding Prohibited Transactions
If you’re looking to open or maintain an IRA account without running afoul of IRS rules and regulations regarding prohibited transactions and disqualified persons, here are some tips that can help:
1. Educate Yourself: Learn everything you can about IRAs before opening one so that you understand what types of activities are allowed versus forbidden under federal law.
2. Work With Qualified Professionals: Enlist the help of qualified professionals such as attorneys and licensed tax advisors who specialize in retirement planning when making investment decisions related to your IRA funds.
3. Keep Detailed Records: Maintain detailed records of all transactions made within your IRAs so that if questions arise later down the line from regulators or auditors at tax time – you’ll have documentation readily available proving proper conduct was followed.
4. Avoid Mixing Personal and Business Finances: Keep your personal and business finances separate, as co-mingling them can lead to confusion and legal issues later on.
5. Stay Up to Date with Changes in Regulations: Keep up-to-date with any changes in IRS regulations relating to prohibited transactions and disqualified persons, as they may change over time.
Conclusion
In conclusion, it’s important to be aware of the rules surrounding prohibited transactions and disqualified persons when it comes to IRA accounts. These restrictions are in place for good reason, as they help ensure that these retirement accounts are used for their intended purpose – saving money for retirement years down the line. By working closely with qualified professionals and staying up-to-date with current regulations, you can avoid potential penalties while maximizing the benefits of your IRA investment portfolio.