Understanding Collateralized Debt Obligations (CDOs): Risks and Rewards
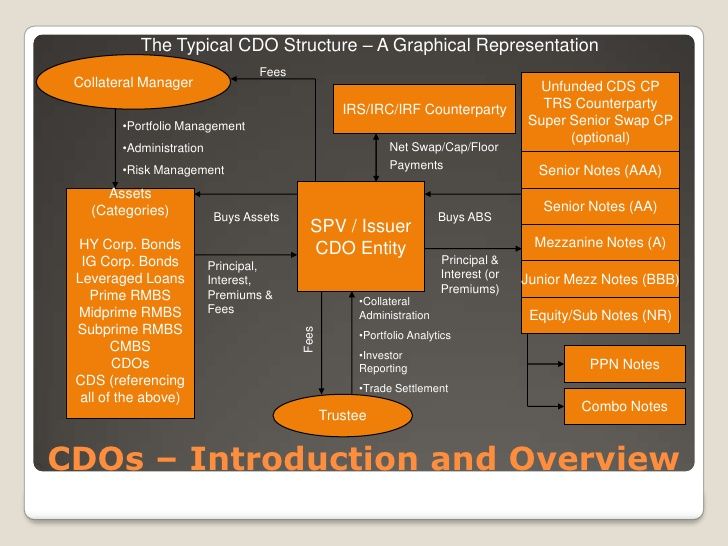
Collateralized debt obligations (CDOs) are complex financial instruments that rose to prominence in the early 2000s and were a significant contributor to the global financial crisis of 2008. At their core, CDOs are securities backed by pools of debt obligations such as mortgages, credit card loans, and other types of debt.
How do CDOs work?
To understand how CDOs work, we need to start with securitization. Securitization is the process by which banks and other financial institutions bundle up assets such as mortgages or car loans into bonds that can be sold to investors on the open market. The cash flows generated from these assets are then used to pay off bondholders.
CDOs take this concept one step further by bundling together multiple asset-backed securities (ABS) into a single entity. These ABS could be anything from subprime mortgage loans to high yield corporate bonds or even student loan debts.
Once bundled together, the cash flows generated from these ABS are divided among different tranches within the CDO. Each tranche has a different level of risk and return associated with it depending on its position in the payment waterfall.
The highest-rated tranche is typically known as the senior tranche and receives payment first until it is fully paid off before payments move down to lower-rated tranches. Lower-rated tranches have higher interest rates but also carry more risk since they may not receive any payments if there isn’t enough cash flow generated by underlying assets.
Types of CDOs
There are two primary types of CDOs – cash flow-based and synthetic-based.
Cash flow-based CDO: In this type of arrangement, investors purchase bonds backed by an existing pool of assets such as subprime mortgages or auto loans. The interest payments made on these underlying assets provide income for those holding senior tranches while simultaneously paying off lower-rated tranches over time.
Synthetic CDO: This type of arrangement is more complicated since it does not involve actual assets. Instead, synthetic CDOs are created through the use of credit default swaps (CDS). Investors purchase tranches based on the performance of a specific reference portfolio, such as corporate bonds or mortgage-backed securities.
Risks Associated with CDOs
CDOs can be complex and risky investments that require a significant amount of due diligence before purchasing. They come with several risks including:
Credit Risk – A key component of CDOs is the underlying pools of debt obligations that they represent. If borrowers in these pools begin to default on their loans en masse, this could lead to significant losses for investors holding lower-rated tranches.
Liquidity Risk – Another risk associated with CDOs is liquidity risk. These securities may be difficult to sell quickly should you need to liquidate your position in a hurry.
Counterparty Risk – Synthetic-based CDOs rely heavily on credit default swaps (CDS) which are contracts between two parties that protect against bond defaults. There is always counterparty risk involved because if one party defaults on their end, it could cause significant problems for the other party.
Market Risk – The value of a given tranche within a collateralized debt obligation will fluctuate based on market conditions and supply/demand dynamics. This means that investors must carefully consider market trends before investing in any particular tranche.
Conclusion
Collateralized debt obligations have been both lauded and criticized over time depending on how well they’ve performed in different markets. While they offer opportunities for diversification and higher yields than traditional fixed-income investments, they also carry significantly more risk than those same investments do.
For those willing to take these risks head-on, however, collateralized debt obligations can provide an excellent way to invest in innovative ways while still generating healthy returns over time. Ultimately though whether or not you choose to invest in a CDO is going to depend on your personal risk tolerance and whether or not you feel comfortable with the associated risks.