Rebalancing Strategies: Maintaining Your Portfolio’s Asset Allocation Mix
Rebalancing Strategies for Index Funds
Investing in index funds is a popular and effective way to build long-term wealth. These funds are designed to track the performance of a particular market index, such as the S&P 500 or Nasdaq Composite, by holding the same stocks in similar proportions as the underlying index. However, over time, these proportions can become unbalanced due to market fluctuations and changes in stock prices. This is where rebalancing comes into play.
What is Rebalancing?
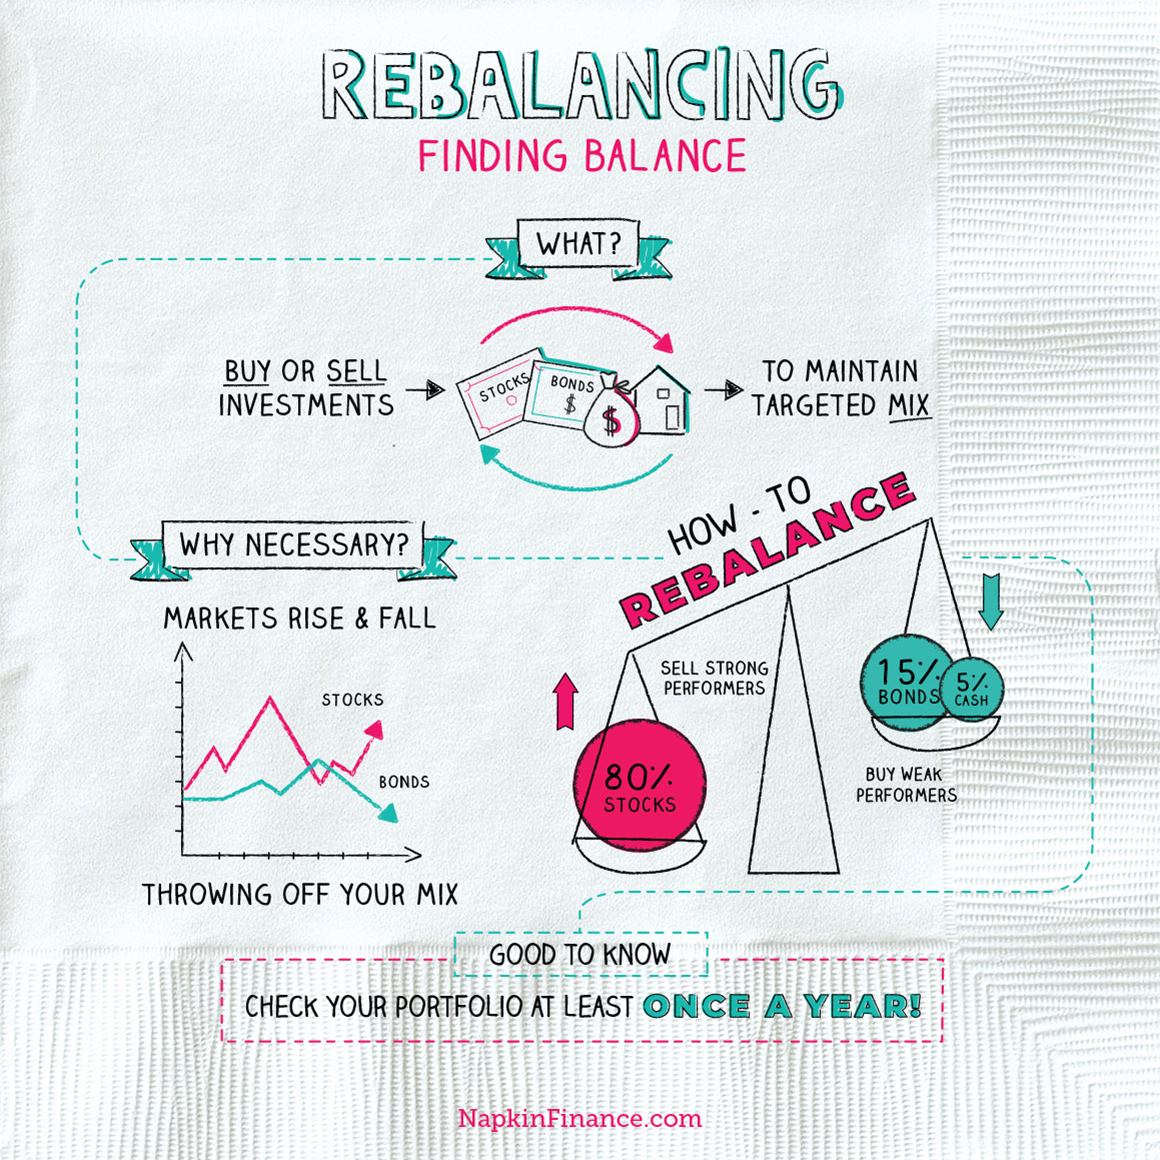
Rebalancing refers to the process of adjusting your portfolio back to its original asset allocation mix. For example, if you started with 60% stocks and 40% bonds and after some time your portfolio now has a composition of 70% stocks and only 30% bonds due to strong stock market performance, then you would need to sell some stocks and buy more bonds until you reach your original allocation.
The Benefits of Rebalancing
One major benefit of rebalancing is that it forces investors to buy low and sell high. When an investor sells an outperforming asset class (such as stocks) while they’re high in value, they are likely able to get higher returns than when selling them later when their price goes down. Additionally, rebalancing can help minimize risk by ensuring your portfolio stays aligned with your risk tolerance level over time.
When Should You Rebalance?
There are two common ways for investors who hold mutual funds or exchange-traded funds (ETFs) approach rebalancing: Time-based or threshold-based approaches.
Time-Based Approach: With this method, investors choose an interval at which they will regularly review their portfolios for potential rebalances – quarterly intervals being one popular option- regardless of how much each investment may have deviated from its target weighting since their last review.
Threshold-Based Approach: Alternatively known as “conditional” or “tolerance” based approaches; threshold-based strategies typically involve setting a percentage threshold which is higher than the original portfolio allocation. Once an asset deviates from its target allocation by this percentage or more, it triggers a review and potential rebalance of that particular asset.
For instance, if your original allocation was 50% stocks and 50% bonds with a tolerance for deviation of +/-5%, you would only need to rebalance when either the stock or bond proportion falls below 45% or shoots above 55%.
However, while both methods are widely used in the finance world, experts tend to lean towards using the threshold-based approach as it helps minimize trading costs.
How Often Should You Rebalance?
The frequency at which investors should rebalance their portfolios usually depends on their investment objectives and risk tolerance levels. Some financial advisors suggest reviewing portfolios quarterly, while others recommend monthly checks. However, more frequent reviews may result in unnecessary transaction fees since brokerage firms generally charge commissions per trade made.
On the other hand, less frequent reviews can lead to bigger deviations from the target allocations before any action is taken; hence it’s essential to strike up balance between regularity and cost-effectiveness.
Also note that some mutual funds have minimum holding periods ranging from six months to one year so make sure you check with your fund provider concerning any restrictions before making hasty decisions on selling off assets too soon.
Which Assets Should You Rebalance?
It’s important to keep in mind that not all assets require equal attention when rebalancing your portfolio. For example, an investor who holds multiple index funds may want to focus on larger positions such as those representing sectors like technology or healthcare rather than smaller holdings like those representing utilities and consumer staples sectors.
Additionally, when considering taxable accounts versus tax-advantaged accounts (such as individual retirement accounts – IRAs), be mindful of taxes incurred through capital gains distribution/realization. If possible try shifting around investments within tax-advantaged account(s) before making adjustments to taxable accounts lest you attract significant taxes.
Finally, it’s wise to consider the bigger picture of your portfolio. If rebalancing means selling outperforming assets and buying underperforming ones, try not to rush into any decisions based on short-term performance metrics; instead focus more on long term goals and overall diversification.
Final Thoughts
Rebalancing is a vital step in maintaining an investor’s asset allocation strategy and minimizing risk over time. It can also help investors buy low and sell high, which is always a good thing. Investors should review their portfolios regularly – either quarterly or monthly depending on their risk tolerance levels- using threshold-based approaches for potential deviations from target allocations. However, be mindful of trading fees when choosing how often to review your portfolio as well as tax implications incurred through capital gains distribution/realization especially within taxable accounts.