“8 Essential Things You Need to Know About Amortizing Loan Fees and Costs”
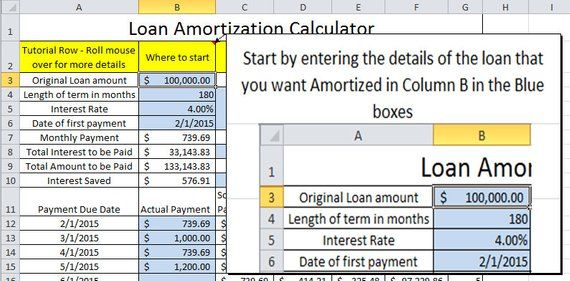
Amortizing loan fees and costs can significantly impact the overall cost of a loan. It is essential to understand these fees and costs before taking out any loans. In this article, we will discuss eight important things you need to know about amortizing loan fees and costs.
1. What are Amortized Loan Fees?
Amortization refers to the process of spreading out payments over time. This means that amortized loan fees are charges that are spread over the life of a loan rather than being paid upfront. Some examples of amortized loan fees include origination fees, application fees, processing fees, underwriting fees, and closing costs.
2. How Do Amortized Loan Fees Work?
When you take out a loan with amortized loan fees, these charges will be added to your monthly payments along with interest until they have been fully paid off. For example, if you took out a $10,000 personal loan with an origination fee of 3%, your total amount borrowed would be $10,300 ($10k + 3% fee). Over the life of the loan (let’s say it’s five years), you would pay back this amount plus interest in equal monthly installments.
3. Why Are Amortized Loan Fees Important?
Amortized loan fees help lenders cover their expenses while minimizing risk by spreading those expenses across many borrowers over time instead of charging them all at once upfront.
4. What is an Annual Percentage Rate (APR)?
The annual percentage rate (APR) includes both interest rates and any other applicable lender charges such as origination or processing fees associated with your specific type of credit product; it represents what borrowers will pay in total for borrowing money each year expressed as a percentage.
5. How Does APR Impact Your Loan Costs?
A lower APR means that borrowing money will cost less over time because there are fewer additional costs associated with it like higher interest rates on loans with higher APRs. It’s important to compare the APR of different loan products before deciding which one is best for you.
6. What Are Prepaid Finance Charges?
Prepaid finance charges are fees that borrowers pay upfront as part of their closing costs or other fees associated with obtaining credit, like origination fees, application fees, and processing fees. These charges are amortized over the life of the loan just like any other fee.
7. How Do Prepaid Finance Charges Impact Your Loan Costs?
Prepaid finance charges can significantly impact your overall loan costs because they are paid upfront instead of being spread out over time like most other fees. This means that if you take out a $10,000 personal loan and have to pay $1,000 in prepaid finance charges, your total amount borrowed would be $11,000 ($10k + $1k fee). You will then pay back this amount plus interest in equal monthly installments over the life of the loan.
8. Can You Negotiate Amortized Loan Fees?
Yes! Many lenders will negotiate their amortized loan fees if you ask them to do so; however, this may not always be possible depending on what type of credit product you’re applying for or how much money you need to borrow.
In conclusion, understanding amortizing loan fees and costs is crucial when taking out any type of credit product such as a personal loan or mortgage. By having a clear understanding of these costs and how they work together with your interest rate and term length – it can help you make more informed financial decisions about borrowing money while minimizing unnecessary expenses throughout the repayment process.