How Often Should You Rebalance Your Investment Portfolio?
Rebalancing Frequency: How Often Should You Do It?
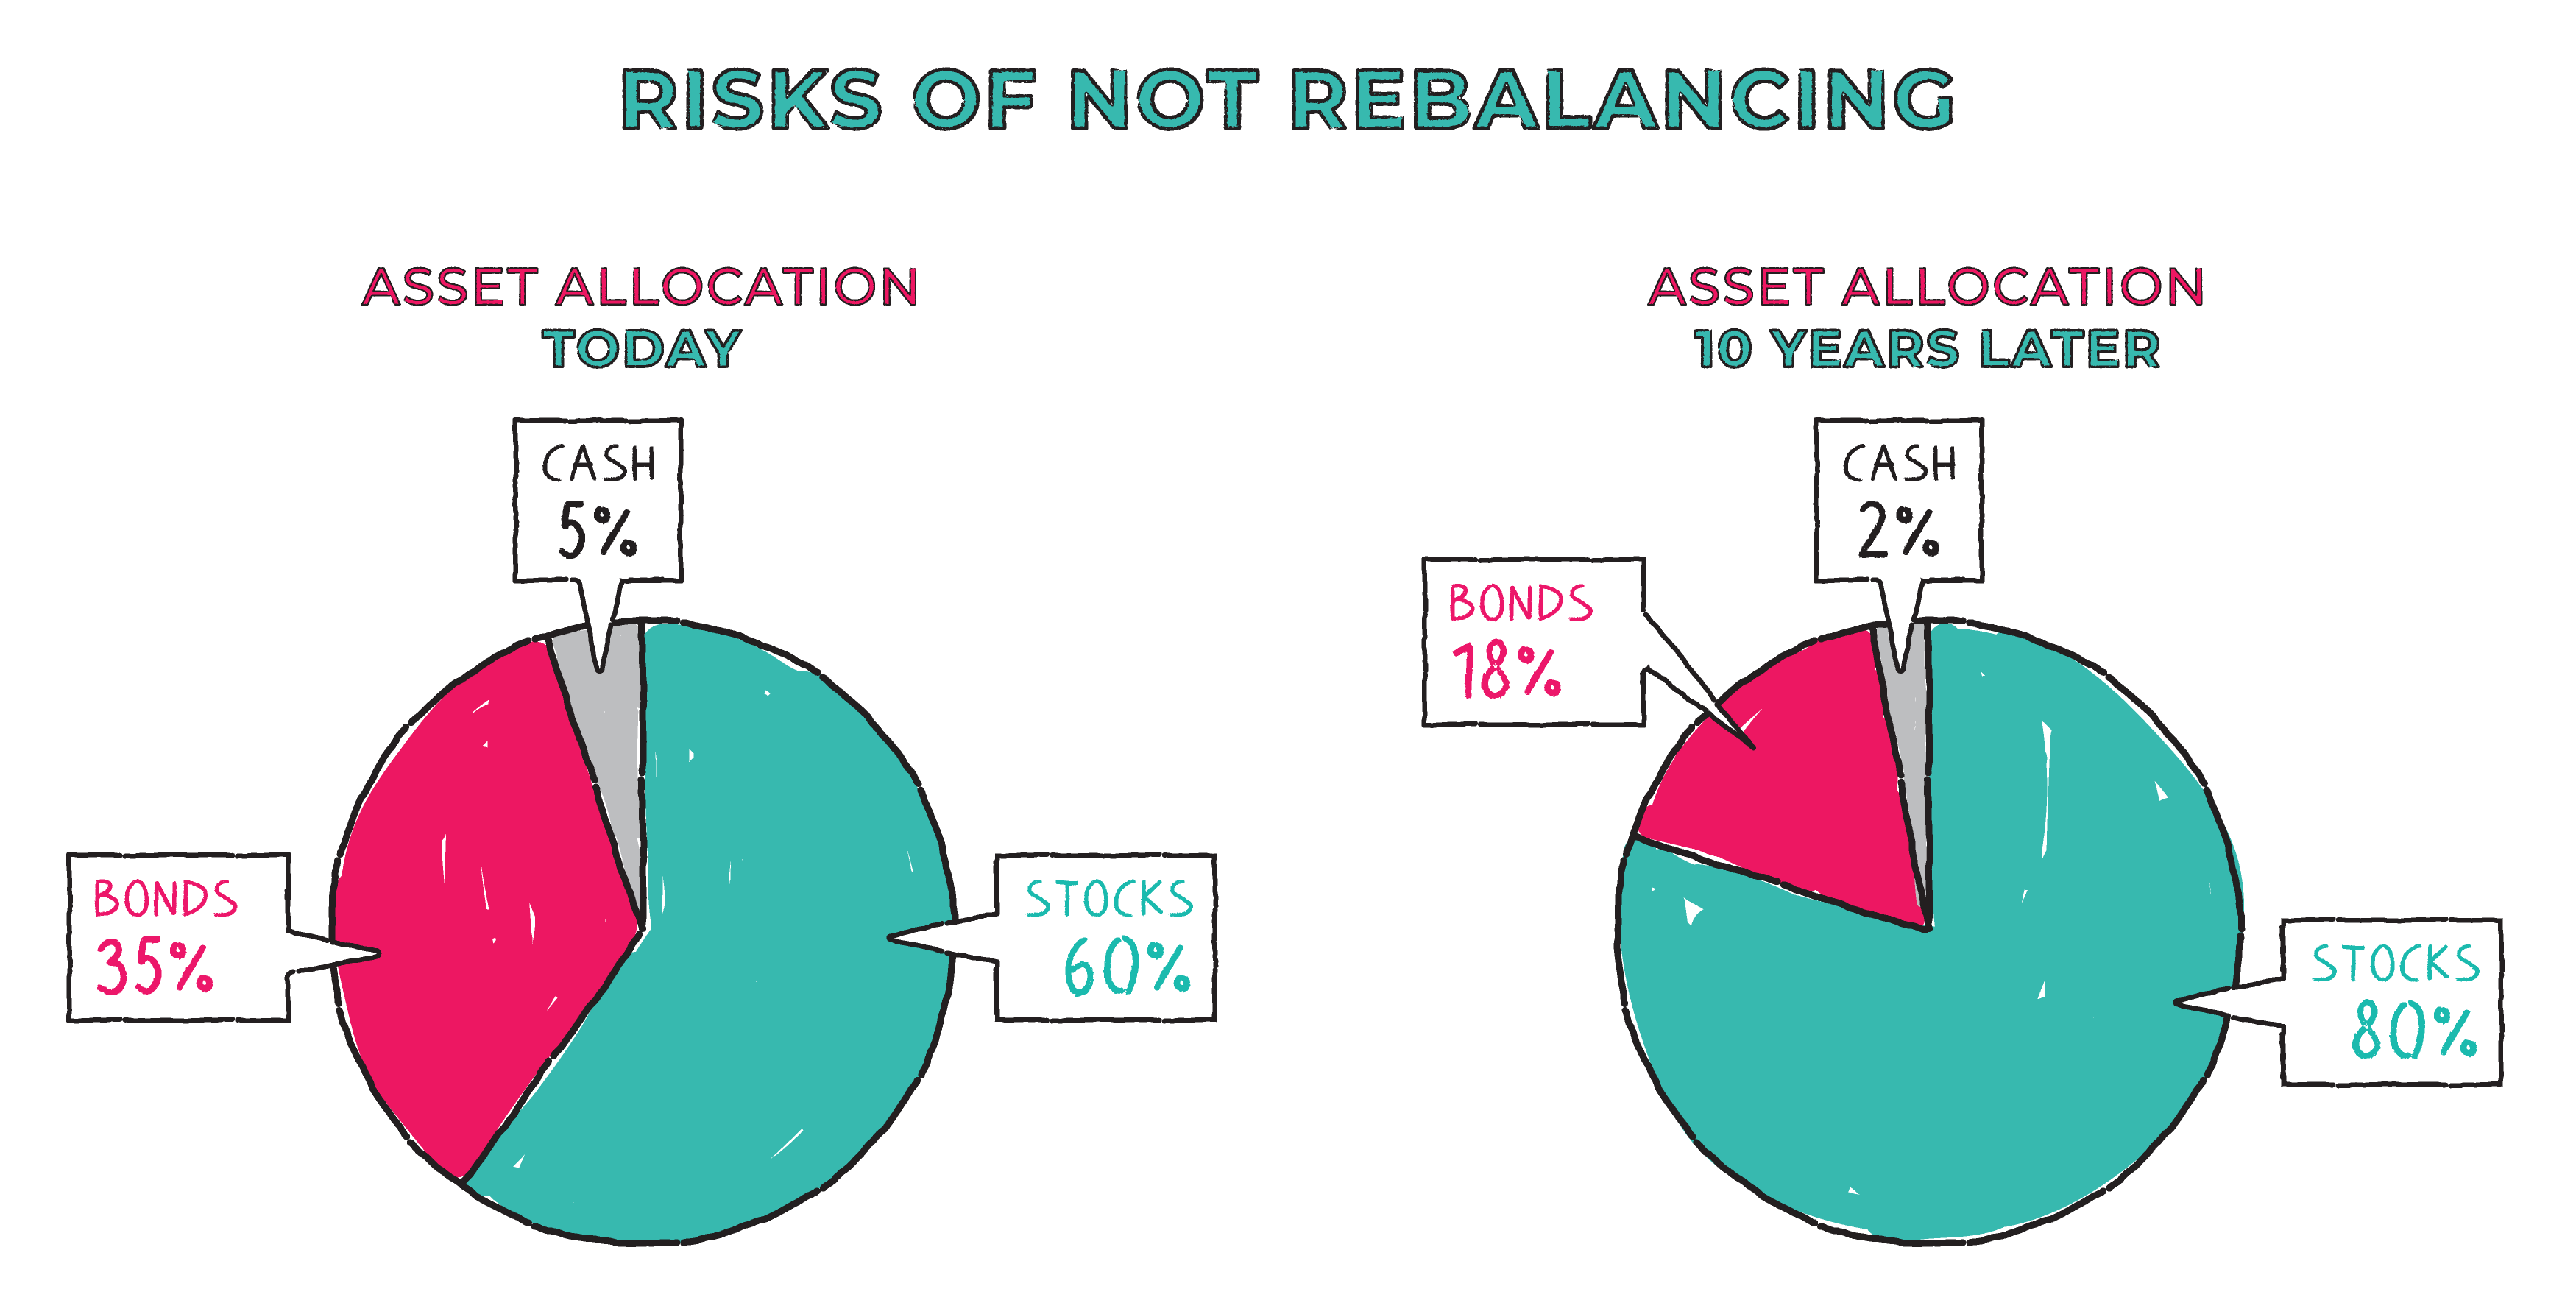
Rebalancing is the process of adjusting your investment portfolio to maintain a certain asset allocation. It’s an important step in managing your investments, but how often should you do it? The answer isn’t as simple as you might think.
Some financial advisors recommend rebalancing every quarter, some say once a year is sufficient, and others suggest only rebalancing when your portfolio deviates significantly from its target allocation. So which approach is right for you? Let’s look at the pros and cons of each option.
Quarterly Rebalancing
The most frequent rebalancing schedule is quarterly. This means reviewing your portfolio every three months and making any necessary adjustments. The advantage of this approach is that it keeps your portfolio very close to its target allocation at all times. Any market fluctuations are quickly corrected by buying or selling assets to maintain the desired balance.
However, there are also drawbacks to quarterly rebalancing. For one thing, it can be time-consuming and stressful to constantly monitor your investments and make changes accordingly. Additionally, frequent trading can result in higher transaction costs if you’re not using a commission-free broker.
Annual Rebalancing
Another popular approach is annual rebalancing. This involves reviewing your portfolio once a year and making any necessary adjustments at that time. The advantage of this method is that it requires less time and effort than quarterly rebalancing while still keeping your investments relatively balanced over the long term.
However, annual rebalancing may not be sufficient for investors with more volatile portfolios or those who want tighter control over their asset allocation. Waiting an entire year could result in significant deviations from the target allocation if there are major market movements during that time frame.
Deviation-Based Rebalancing
A third option for rebalancers is deviation-based scheduling. This involves monitoring your portfolio regularly (weekly or monthly) but only making changes when there is a significant deviation from your target allocation. For example, if your desired asset allocation is 60% stocks and 40% bonds, you might set a threshold of +/-5%. This means that if your stock holdings drop below 55% or rise above 65%, you would rebalance to bring them back into line.
The advantage of this approach is that it’s less time-consuming than quarterly or monthly rebalancing since you only need to make changes when necessary. It also allows for more flexibility in responding to market movements without being overly reactive.
However, deviation-based rebalancing may not be suitable for all investors. Setting a threshold can be arbitrary and there’s always the risk of overreacting to short-term market fluctuations. Additionally, this method requires more active monitoring than annual rebalancing, which could be stressful for some investors.
Conclusion
So which approach should you choose? Ultimately, the answer depends on your individual circumstances and investment goals. If you have a relatively stable portfolio with low volatility, annual rebalancing may be sufficient. If you’re willing to put in the time and effort to monitor your investments regularly, quarterly or deviation-based scheduling could work well for you.
Regardless of which option you choose, remember that rebalancing is an important part of managing your investments over the long term. By maintaining a consistent asset allocation, you can reduce risk and increase your chances of achieving your financial goals.