Mastering Amortization Schedules: The Key to Better Financial Planning
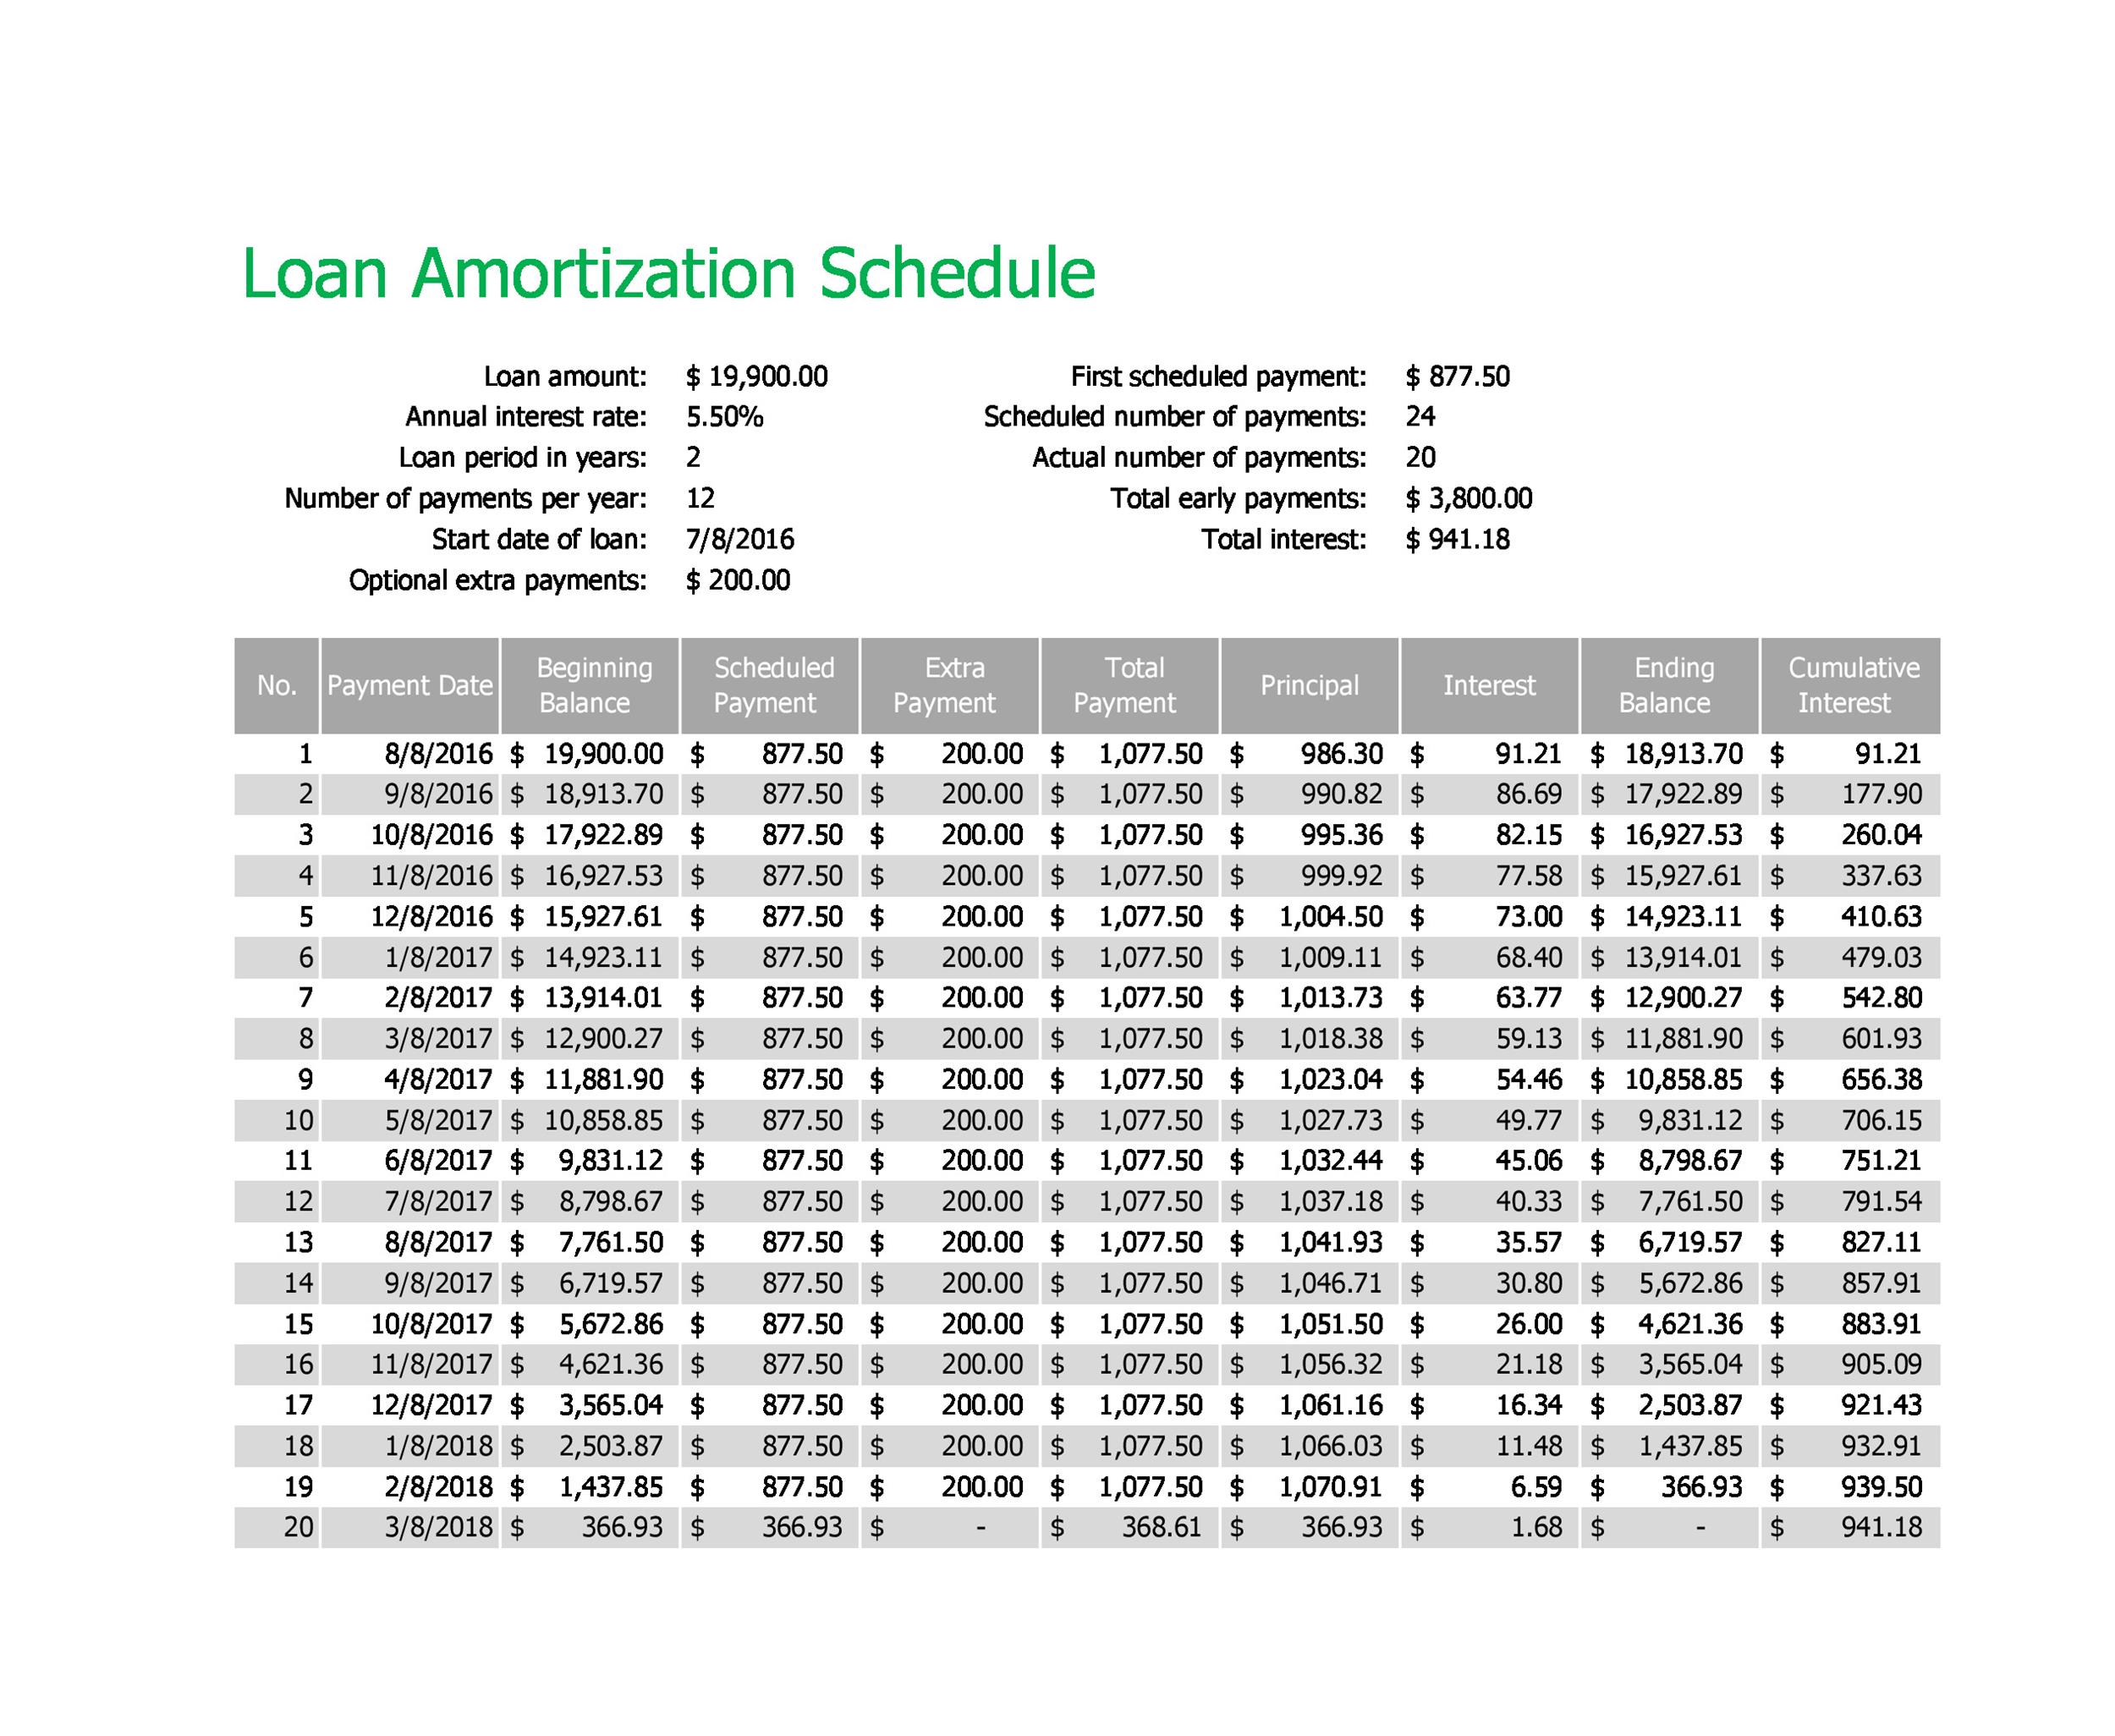
Amortization Schedules: Understanding and Using Them for Financial Planning
If you’re planning to take out a loan or mortgage, it’s important to understand how amortization schedules work. An amortization schedule is a table that shows the breakdown of your monthly payments, including the amount paid towards principal and interest. By understanding how these schedules work, you can make better financial decisions about borrowing money.
What is Amortization?
Before we dive into the specifics of an amortization schedule, let’s first define what “amortization” means. The term refers to paying off debt over time through regular payments. This payment structure applies not only to loans but also mortgages and even credit card balances.
Amortized loans are repaid in equal installments over an agreed-upon period of time until both principal and interest are fully paid back at maturity. In contrast, non-amortized loans require payment of all accrued interest plus principal in one lump sum at maturity.
How Does Amortization Work?
When taking out a loan or mortgage, the lender will calculate your monthly payments based on several factors such as the loan amount, interest rate, and repayment term (the length of time over which you’ll be making payments). The monthly payment is typically fixed throughout the life of the loan unless there’s an adjustable-rate feature built into it.
The portion of each monthly payment that goes towards paying down your principal balance gradually increases while decreasing what goes toward paying off accrued interests as per amortizing terms.
At first instance when repayments start on a newly acquired debt obligation (loan/mortgage), most of your initial payments go towards covering off accrued interests with little going toward reducing your outstanding balance. As more repayments come due over time though – this pattern reverses until ultimately where almost 100% percent goes towards decreasing outstanding balances at end-of-life stages like maturity or refinancing points along its lifespan depending upon individual circumstances.
What is an Amortization Schedule?
An amortization schedule is a table that shows the breakdown of your monthly payments, including how much goes towards principal and interest. The schedule outlines each payment due date, the amount paid toward principal, and the remaining balance on the loan or mortgage.
Many lenders provide an amortization schedule when you take out a loan or mortgage; however, it’s also possible to create one yourself using online calculators or spreadsheet programs like Microsoft Excel and Google Sheets.
Using an Amortization Schedule
Understanding how to use an amortization schedule can help you better manage your debt obligations. Here are some ways:
1. Determine Monthly Payments: By using an amortization calculator for calculating expected monthly payments on loan amounts borrowed over specific periods at pre-agreed rates – borrowers can determine what amount they will need to pay back their debts promptly while keeping within their budgetary limits.
2. Track Progress in Paying Off Debt: With each repayment made according to scheduled terms as per agreed upon with lenders, the outstanding balance reduces gradually until eventual full payoff at maturity points along its lifespan depending upon individual circumstances which can be tracked through regular review of these schedules.
3. Plan Your Finances Better: An amortization schedule helps you plan your finances by allowing you to see exactly how much money will go towards interest versus principal over time so that you can make informed decisions about borrowing more or paying off existing loans early without penalty fees.
Advantages of Using Amortization Schedules
There are several advantages to using an amortization schedule when managing debt obligations:
1. Clear Understanding of Payment Structure – An Amortisation table helps borrowers gain clarity regarding payment structure – making it easier for them in prioritizing repayments based upon respective interests and other factors influencing timely settlement thereof such as income streams available after taking into account essential expenses which must be met first before servicing any financial obligation beyond those needs deemed necessary for daily living expenses (food, housing, utilities).
2. Better Financial Planning – By analyzing expected monthly payment amounts and tracking progress over time – borrowers can plan their finances better, considering how much money is going towards interest versus principal payments each month.
3. Budget Management – An Amortization schedule helps in budget management by providing insights into cash flow projections based on repayment schedules as well as highlighting areas where adjustments may be necessary to ensure timely settlement without undue stress or financial hardship.
4. Early Settlement Opportunities – Borrowers can use an amortization schedule to identify early settlement opportunities that might reduce the overall cost of borrowing due to lower interest charges incurred at later stages when compared with earlier periods during the loan’s lifespan.
Disadvantages of Using Amortization Schedules
While there are many benefits to using an amortization schedule, some disadvantages should also be considered:
1. Inflexibility – Once you sign a loan agreement with fixed payment terms over a predetermined period at pre-agreed rates per annum (APR), it becomes inflexible and unchangeable except through refinancing which may incur extra costs that could outweigh any potential savings from reduced interest expenses if not done carefully after thorough consideration of individual circumstances involved such as income streams available after taking into account essential expenses which must be met first before servicing any financial obligation beyond those needs deemed necessary for daily living expenses (food, housing, utilities).
2. Limited Options for Payment Modification – Some lenders may limit options for modifying payments beyond those set forth in initial agreements; therefore making it difficult for borrowers who need more flexibility than provided by standard contractual terms agreed upon initially during underwriting processes conducted prior acquisition of debt obligations.
3. Repayment Risk: Depending on prevailing market conditions and other factors outside your control such as job security issues or changes in personal life circumstances- repayment risk always exists even when all efforts have been made within reasonable limits possible under specific situations faced by individuals while managing these loans/mortgages.
Conclusion
An amortization schedule is an essential tool for managing debt obligations. By understanding how it works and using it effectively, you can make better financial decisions about borrowing money. The key to success is to stay disciplined with your repayments and regularly review the schedule to track progress towards full payoff points along its lifespan depending upon individual circumstances faced by borrowers while servicing these debts over time.