Unlocking the Power of Home Equity Loan Principal Balance: What You Need to Know
Home Equity Loan Principal Balance: What You Need to Know
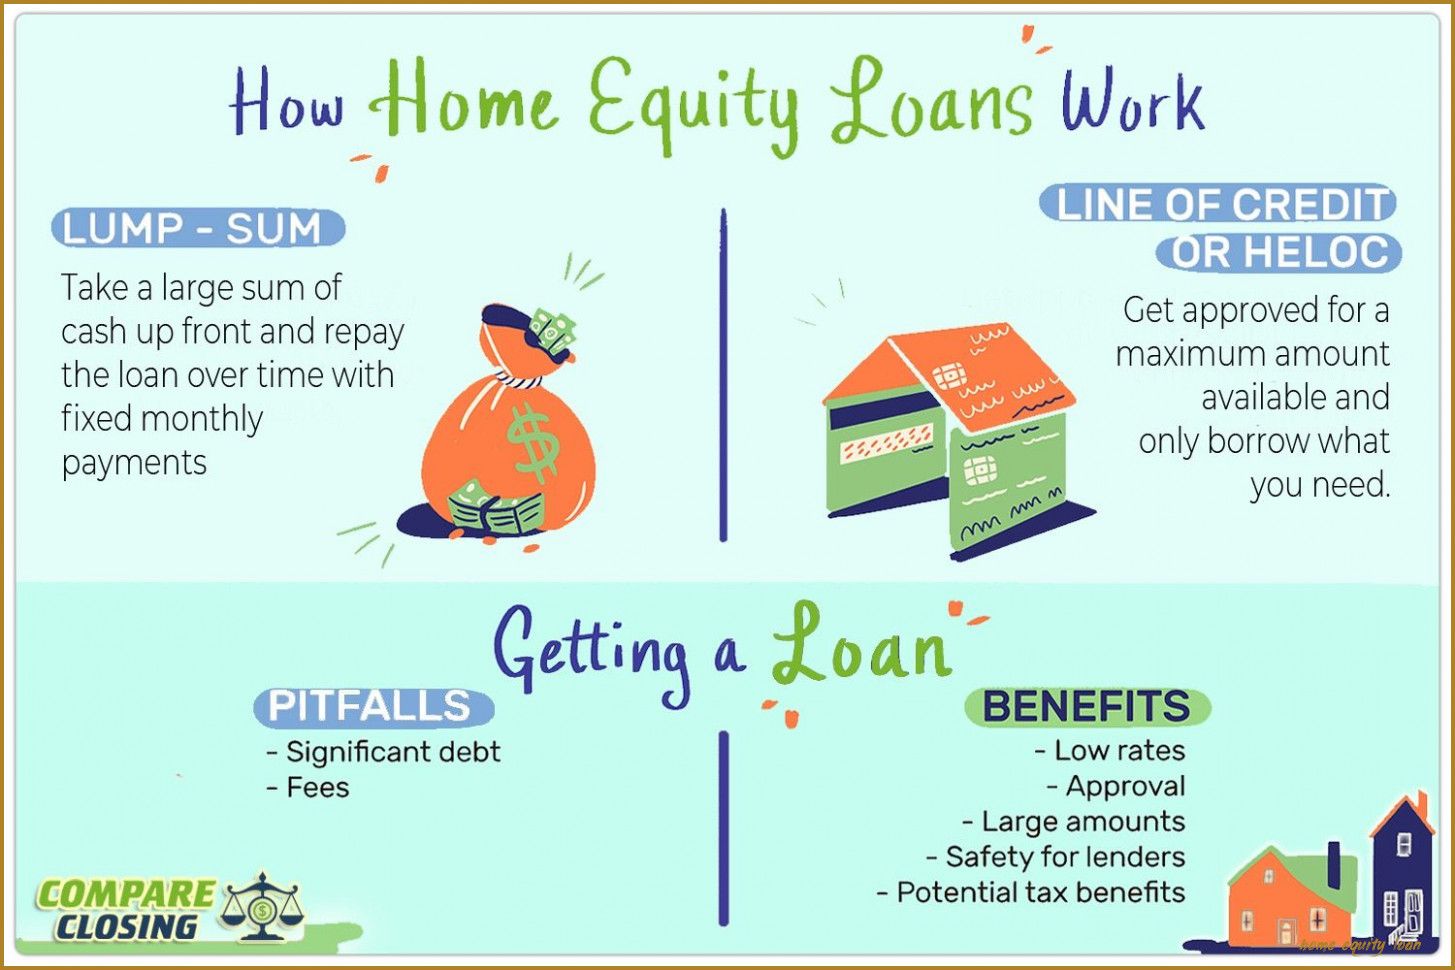
A home equity loan is a type of loan that allows homeowners to borrow against the value of their property. This type of loan can be used for a wide range of purposes, including home improvements, debt consolidation, or even paying for college tuition. One important aspect to consider when taking out a home equity loan is the principal balance.
The principal balance refers to the amount of money borrowed on the loan. This amount will typically include any fees or charges associated with obtaining the loan as well as the interest rate charged by the lender. It’s important to understand how your monthly payments are applied towards your principal balance and how it affects your overall financial situation.
Monthly payments on a home equity loan are typically structured so that they first cover interest charges and then apply any remaining funds towards reducing the principal balance. This means that in order to reduce your total debt over time, you need to make regular payments that exceed just covering interest charges.
One strategy for reducing your principal balance quickly is making extra payments whenever possible. Even small additional payments can have a significant impact over time by accelerating repayment and reducing overall interest charges.
Another factor affecting your principal balance is fluctuations in interest rates. If you have an adjustable-rate home equity loan, changes in market conditions could result in higher or lower monthly payments depending on where rates stand at any given point.
If you’re considering taking out a home equity line of credit (HELOC), it’s worth noting that this type of financing operates differently than traditional loans with fixed terms and amortization schedules. A HELOC provides access to funds up to a certain limit but doesn’t require borrowers to take out all available funds at once or repay them according to set terms like other loans do.
Instead, borrowers are free to draw upon their HELOC as needed up until reaching their credit limit while only paying back what they’ve actually borrowed plus interest each month during what’s known as the draw period. Once this phase ends, however, borrowers are required to begin repaying both principal and interest over a set term.
Finally, it’s important to keep in mind that your home serves as collateral for any home equity loan you take out. This means that if you’re unable to make payments on the loan or default entirely, your lender has the right to foreclose on your property in order to recover their losses.
In conclusion, understanding how your monthly payments impact your home equity loan principal balance is essential for keeping track of your debt and ensuring that you’re making progress towards repayment goals. By staying informed about interest rates and taking advantage of opportunities to make extra payments whenever possible, homeowners can reduce their overall debt burden and achieve greater financial stability over time.