Unlocking the Value of Your Home: A Comprehensive Guide to Home Equity Loans and Lines of Credit (HELOCs)
Home Equity Loans/Lines of Credit (HELOCs) – A Comprehensive Guide
As a homeowner, you may have heard about home equity loans and lines of credit, but do you really know what they are and how they work? In this comprehensive guide, we will explore everything you need to know about HELOCs.
What is a Home Equity Loan?
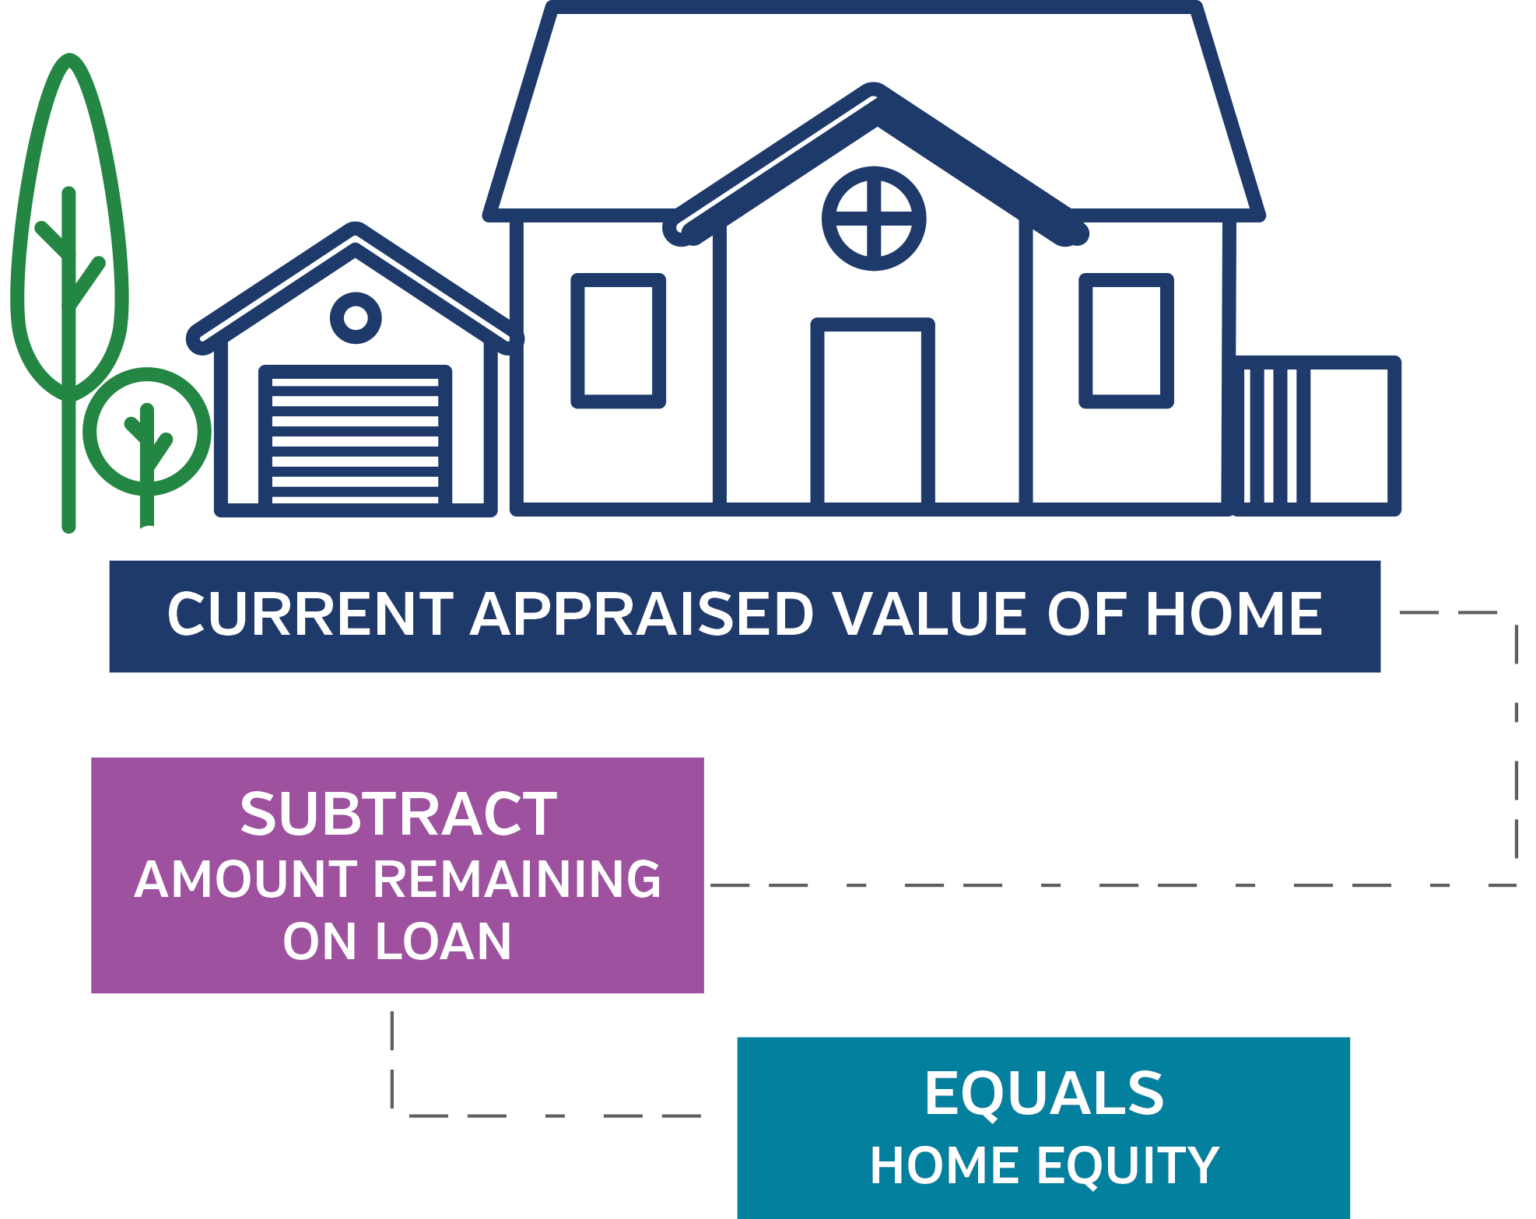
A home equity loan is a type of loan that allows homeowners to borrow money against the value of their homes. The amount that can be borrowed is typically based on the difference between the current market value of the home and any outstanding mortgage debt. This type of loan usually has fixed interest rates and terms ranging from 5-30 years.
What is a Home Equity Line of Credit (HELOC)?
A HELOC is similar to a home equity loan in that it allows homeowners to borrow money against the value of their homes. However, instead of receiving one lump sum payment like with a traditional home equity loan, borrowers are given access to a line of credit that they can draw from as needed. The interest rates for HELOCs are typically variable and fluctuate based on market conditions.
How Does a Home Equity Loan/Line Work?
When applying for either type of loan, lenders will evaluate your credit score, income, debt-to-income ratio, and other financial factors before determining if you qualify for financing. If approved for funding, homeowners can use the funds from their home equity loans or lines for anything they desire such as consolidating debt or making renovations/improvements to their property.
One key difference between these two types of loans lies in how borrowers receive funds. With a traditional home equity loan—borrowers receive one lump sum payment at closing which includes all funds available under the terms agreed upon by both parties; whereas with an open-ended line-of-credit structure offered through HELOCS—you only withdraw amounts needed when required up until reaching your pre-approved limit.
Another notable difference is the interest rate structure. Home equity loans usually have fixed interest rates which remain the same throughout the life of the loan, whereas HELOCs have variable interest rates that can fluctuate over time.
How Much Can You Borrow?
The amount you can borrow with a home equity loan or line of credit depends on several factors including your credit score, income, debt-to-income ratio, and how much equity you have in your home. Typically lenders will let homeowners borrow up to 80% of their homes’ value. If you own your home outright—that means no mortgage—you may be able to qualify for an even higher amount depending on other factors.
Benefits of Home Equity Loans/Lines
There are numerous benefits associated with borrowing against your home’s value. Here are some of the most common advantages:
– Access to Large Sums: By tapping into your homes’ value, you can access larger sums than what is typically available through unsecured personal loans.
– Lower Interest Rates: Because these types of loans are secured by property—homeowners often benefit from lower interest rates compared to other forms of financing.
– Tax Deductible Interest: In many cases, homeowners who take out a mortgage or HELOC may be able to deduct their monthly payments on their federal taxes.
– Flexibility: With HELOCs—borrowers only pay back what they use so there is more flexibility in how funds are used and borrowed.
Drawbacks/Considerations
While there are plenty of benefits associated with borrowing against your homes’ value—their also exist potential drawbacks and considerations worth noting before taking out either type of loan such as:
– Risking Your Home – Both types of loans involve putting up one’s house as collateral; if something goes wrong financially speaking like defaulting—it could result in foreclosure proceedings initiated by lenders seeking repayment.
– Fees – Depending on where you live and which lender(s) you work with—you may be responsible for paying fees like appraisal, closing, and annual maintenance costs.
– Interest Rates – While HELOCs may initially offer lower interest rates than traditional home equity loans; they also come with a variable rate structure which means payments could increase or decrease over time.
Things to Keep in Mind When Applying
If you’re considering applying for either type of loan—it’s important to keep the following things in mind:
– Shop Around: Make sure you compare offers from multiple lenders before deciding on one. Different lenders will have different terms and interest rates.
– Check Your Credit Score: A higher credit score typically results in better loan terms including lower interest rates.
– Consider the Risks: Before borrowing against your homes’ value—consider the risks involved if something goes wrong financially speaking (i.e., foreclosure proceedings).
– Be Prepared for Fees: Depending on where you live and which lender(s) you work with—you may be responsible for paying fees associated with appraisals, closing costs, and annual maintenance expenses.
Conclusion
Home equity loans/lines of credit are an excellent option for homeowners who need access to larger sums of money at lower interest rates. If used properly—they can help finance things like renovations, consolidating debt, or even starting a new business venture. However, because these types of loans involve putting up your home as collateral—it’s important to weigh the risks involved before taking out financing.