“Boost Your Retirement Savings with Catch-Up Contributions to IRAs”
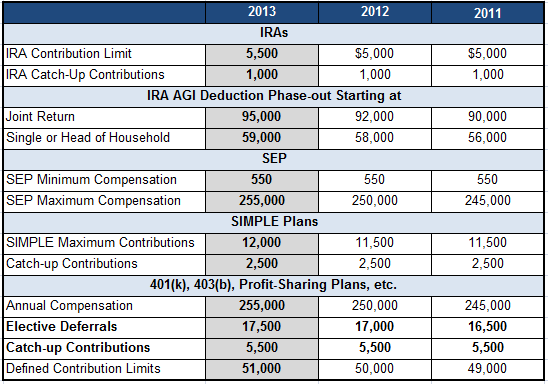
As the years go by, it’s important to keep a close eye on your retirement savings and ensure you’re on track for retirement. One way to do this is by making catch-up contributions to your IRA. Catch-up contributions allow individuals who are 50 or older to contribute more money than the annual contribution limit set by the IRS.
For 2021, the maximum contribution limit for IRAs is $6,000 per year for those under age 50. However, if you’re age 50 or older, you can make catch-up contributions of up to $1,000 in addition to the $6,000 regular contribution limit. This means that those over age 50 can contribute up to $7,000 per year in total.
Catch-up contributions can be made to both Traditional and Roth IRAs. It’s important to note that catch-up contributions are not automatic and must be manually initiated by the account holder.
One benefit of making catch-up contributions is that they can help boost your retirement savings quickly. For example, if a person were able to max out their IRA at $7,000 from ages 50-55 (assuming no growth), they would have contributed an additional $35,000 towards their retirement compared with someone who was not eligible for catch-up contributions.
Another benefit of making catch-up contributions is that they may lower your taxes owed come tax time. Contributions made to Traditional IRAs are tax-deductible up front and grow tax-deferred until withdrawn in retirement. By contributing more money upfront via a catch-up contribution, you’ll reduce your taxable income for the year which could result in lower taxes owed overall.
On the other hand, Roth IRA contributions are made with after-tax dollars but grow tax-free throughout one’s lifetime as long as certain conditions are met when withdrawing funds during retirement years. With Roths there isn’t an immediate reduction in taxes owed but because withdrawals aren’t taxed later on, you’re getting a tax advantage in the long run.
It’s important to note that catch-up contributions cannot be made to employer-sponsored retirement plans such as 401(k)s or 403(b)s. Catch-up contributions are only available for IRAs.
When considering making catch-up contributions, it’s important to evaluate your overall financial situation and ensure you can afford the additional contribution amount. It may not make sense to contribute more if you have high-interest debt or haven’t established an emergency fund yet.
Additionally, it’s important to consider how much time is left until retirement. If you’re only a few years away from retiring and haven’t saved enough for retirement, making catch-up contributions may not be enough to close the gap.
One common misconception about IRA catch-up contributions is that they can only be made in one lump sum payment at the end of the year. This is not true – catch-up contributions can be made throughout the year just like regular IRA contributions.
It’s also worth noting that there are income limitations on who can contribute directly to Roth IRAs (though there are ways around this – see backdoor Roth conversions). Individuals with modified adjusted gross incomes over $140,000 (single filers) or $208,000 (married filing jointly) aren’t eligible for direct Roth IRA contributions but they could still contribute after-tax dollars into their Traditional IRA and then convert those funds into a Roth via a backdoor conversion.
In addition, keep in mind that if you withdraw money from your IRA before age 59 ½, early withdrawal penalties may apply unless certain exceptions apply such as disability status or first-time home purchase expenses.
Finally, remember that investment returns cannot be guaranteed so while contributing more money towards retirement savings through catch up provisions will certainly help give your portfolio greater potential growth opportunities but it doesn’t guarantee higher returns compared with other types of investments like stocks or bonds.
In conclusion; Catch-Up Contributions to IRAs can be a great way for those over the age of 50 to increase their retirement savings and potentially reduce their tax liability. However, before deciding whether or not catch-up contributions are right for you, it’s important to evaluate your overall financial situation and long-term goals. Always remember that investment returns aren’t guaranteed so consider all of your options carefully when choosing how to invest your money.