Understanding the Difference Between Interest Rate and APR: Making Informed Financial Decisions
Understanding the Difference Between Interest Rate and APR
When it comes to borrowing money, it’s essential to understand the difference between interest rate and APR (Annual Percentage Rate). These two terms are often used interchangeably but have distinct meanings. Knowing what each represents can help you make informed financial decisions and avoid potential pitfalls. In this article, we will break down the differences between interest rate and APR, how they impact your loans, and when to use each metric.
Interest Rate: The Cost of Borrowing Money
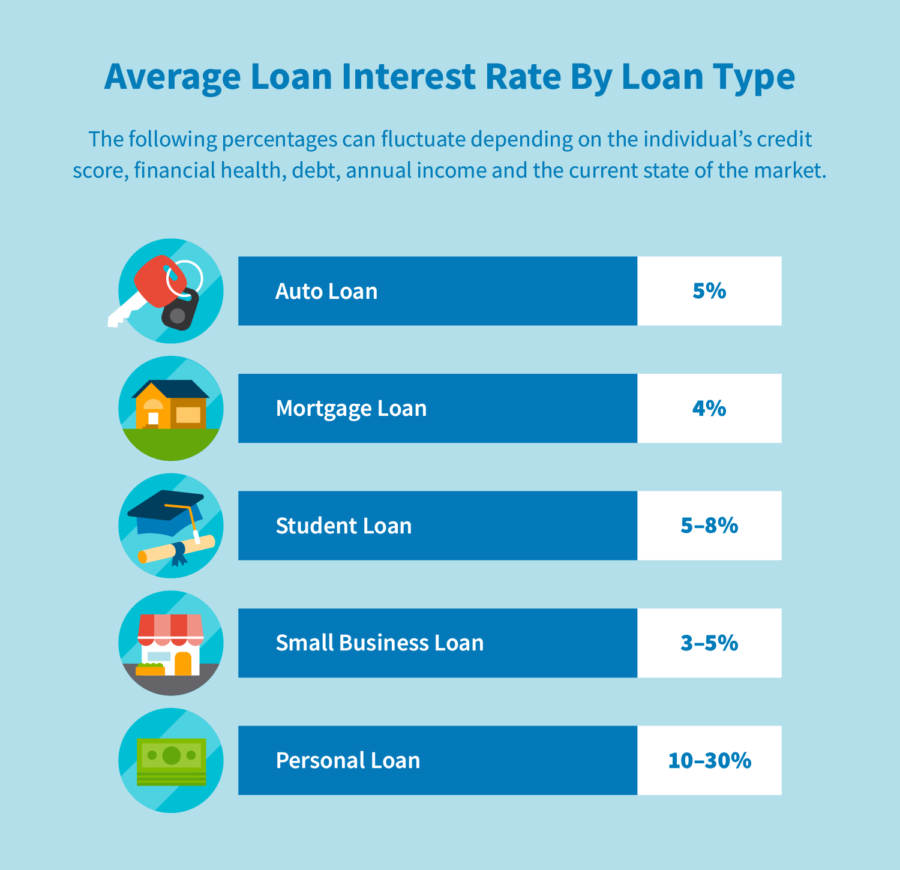
The interest rate is simply the cost of borrowing money expressed as a percentage. It is determined by several factors such as market conditions, inflation rates, creditworthiness of borrowers, and the type of loan or credit product being offered. When you borrow money from a lender—whether it’s for a mortgage, auto loan, personal loan, or credit card—the interest rate determines how much extra you will pay over time on top of repaying the principal amount borrowed.
For example, if you take out a $10,000 personal loan with an annual interest rate of 5%, you will owe $500 in interest charges per year. The higher the interest rate on your loan or credit product is, the more expensive it becomes to borrow that money.
APR: A Comprehensive Measure
While interest rates provide insight into how much you’ll be charged for borrowing funds annually relative to the principal sum owed (the initial amount borrowed), they don’t necessarily encompass all costs associated with obtaining that credit facility. This is where APR comes into play.
APR includes both the nominal interest rate charged by lenders plus any additional fees or costs involved in securing financing. These expenses may include origination fees for mortgages or personal loans; closing costs for real estate transactions; points paid upfront; prepaid finance charges; discount points on mortgages; etc.
By incorporating these additional costs into its calculation formula, APR provides borrowers with a more comprehensive understanding of their overall borrowing costs. It helps you make an apples-to-apples comparison when considering loans from different lenders or credit products with various terms and conditions.
For instance, if Lender A offers a mortgage at 4% interest rate but charges significant origination fees, while Lender B has a slightly higher interest rate of 4.25% but with lower fees, comparing the APRs will give you a clearer picture of which option is more cost-effective over the long run.
When to Use Interest Rate vs. APR
The choice between using interest rate or APR depends on your specific needs and circumstances:
1. Interest Rate:
– If you want to understand how much extra you’ll be paying annually based solely on the principal amount borrowed.
– When comparing rates across different loan options without factoring in additional expenses.
2. APR:
– To determine the true cost of borrowing money after incorporating all associated fees.
– When comparing multiple loan offers from different lenders or credit products with varying terms and conditions.
– For assessing mortgages, auto loans, personal loans, or other financing options that may have upfront costs beyond just the nominal interest rate.
It’s important to note that while APR provides valuable information for making informed decisions, it still has limitations. The calculation assumes that you will hold the loan for its entire term without refinancing or paying it off early. Additionally, not all lenders include the same fees in their APR calculations, so it’s essential to scrutinize each lender’s disclosures carefully before making any financial commitments.
Conclusion
Understanding the difference between interest rate and APR empowers borrowers like yourself to make better financial choices by considering both factors appropriately. While interest rates indicate how much extra money you’ll pay annually based on your principal balance borrowed, APR incorporates additional costs such as origination fees into its calculation formula for a more comprehensive view of borrowing expenses over time.
Remember that deciding whether to focus on interest rates or APR depends on your specific needs and circumstances. Interest rates are useful for quick comparisons between loans, while APR provides a more accurate representation of the total cost of borrowing money.
By being aware of these distinctions and evaluating loan options accordingly, you can make well-informed financial decisions that align with your goals and budget.