Navigating the Foreclosure Timeline: Protecting Your Home and Financial Well-Being
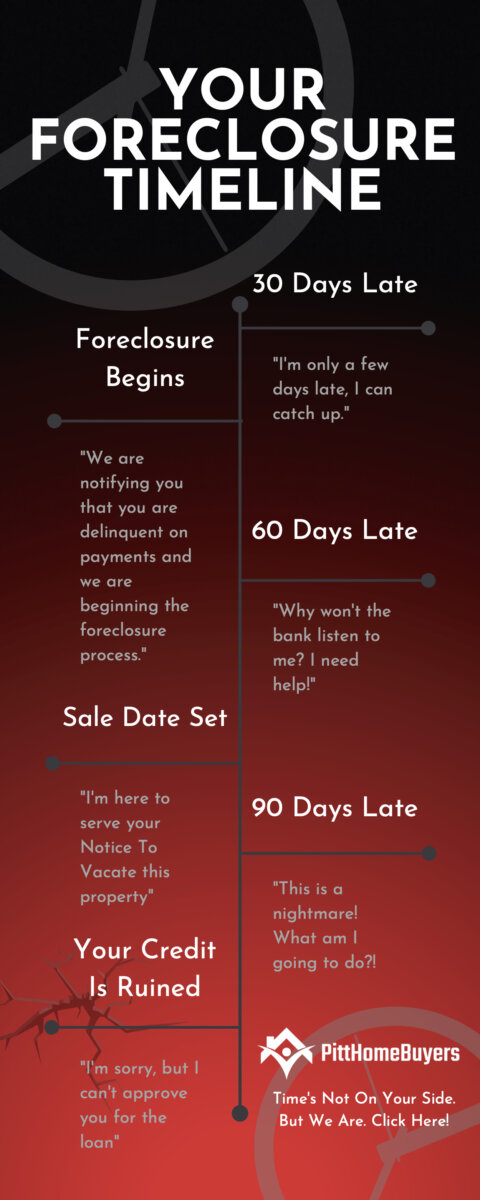
Foreclosure Timeline: Understanding the Process and Protecting Your Home
Introduction:
Facing foreclosure is a distressing situation that no homeowner wants to experience. However, understanding the foreclosure timeline can help you navigate through this challenging process with clarity and make informed decisions. In this article, we will delve into the various stages of foreclosure, highlighting key milestones along the way. By familiarizing yourself with this timeline, you can take proactive steps to protect your home and financial well-being.
Stage 1: Missed Payment(s)
The first stage in the foreclosure timeline begins when you miss one or more mortgage payments. Generally, lenders allow a grace period before considering a payment late. The exact length of this grace period varies from lender to lender but is usually around 15 days after the due date.
During this initial stage, it is crucial to communicate with your lender as soon as possible if you anticipate difficulties in making timely payments. Many lenders offer loan modification programs or temporary forbearance options which can provide relief during times of financial hardship.
Stage 2: Notice of Default (NOD)
If you fail to bring your mortgage current within a specified timeframe (typically 90 days), your lender will issue a Notice of Default (NOD). This notice informs you that your loan is in default due to non-payment and officially marks the beginning of the foreclosure process.
Once an NOD has been issued, it becomes public record, meaning it can be accessed by anyone who conducts a title search on your property. Additionally, credit reporting agencies may also include this information on your credit report, negatively impacting your credit score.
Stage 3: Pre-Foreclosure Period
After receiving an NOD, homeowners enter what is known as the pre-foreclosure period. During this time frame (which varies by state but generally lasts for several months), homeowners have an opportunity to resolve their delinquency by paying off their outstanding debt or negotiating alternative arrangements with their lender.
To explore alternatives, homeowners can work with housing counselors or attorneys who specialize in foreclosure prevention. These professionals can help negotiate loan modifications, repayment plans, or even short sales to avoid foreclosure altogether.
Stage 4: Auction and Sale
If a homeowner fails to resolve the delinquency during the pre-foreclosure period, the property will move into the auction phase. This typically involves scheduling a public auction where the property is sold to the highest bidder. The auction is usually held at a designated location such as a courthouse or an auction house.
The specific rules governing foreclosure auctions vary from state to state. In some states, lenders are able to conduct non-judicial foreclosures, while others require judicial supervision. It’s important for homeowners to understand their state’s laws and regulations regarding foreclosure auctions.
Stage 5: Post-Foreclosure Redemption Period
Following the auction and sale of your home, some states offer a post-foreclosure redemption period during which you may have an opportunity to reclaim your property by paying off all outstanding debts plus associated fees and costs. This time frame allows homeowners one last chance to save their homes before losing them permanently.
However, it’s worth noting that not all states provide a redemption period. If your state does offer this option, be sure to familiarize yourself with its duration and requirements so that you can take appropriate action if necessary.
Stage 6: Eviction
Should all attempts at resolution fail and no redemption period is available (or has passed), eviction becomes imminent once ownership of the property has legally transferred to the new buyer at auction. At this point, it is crucial for homeowners facing eviction to prepare accordingly by making arrangements for alternative housing options.
Conclusion:
Facing foreclosure is undoubtedly challenging both emotionally and financially; however understanding each stage of the process can empower homeowners to make informed decisions about protecting their interests throughout this difficult time. By seeking professional advice early on and exploring all available options, homeowners can increase their chances of avoiding foreclosure or minimizing its impact. Remember, timely communication with your lender is key, and seeking assistance from housing counselors or attorneys specializing in foreclosure prevention can provide valuable guidance and support.