Navigating Credit Card Use in Emergencies: Key Tips for Wise Utilization
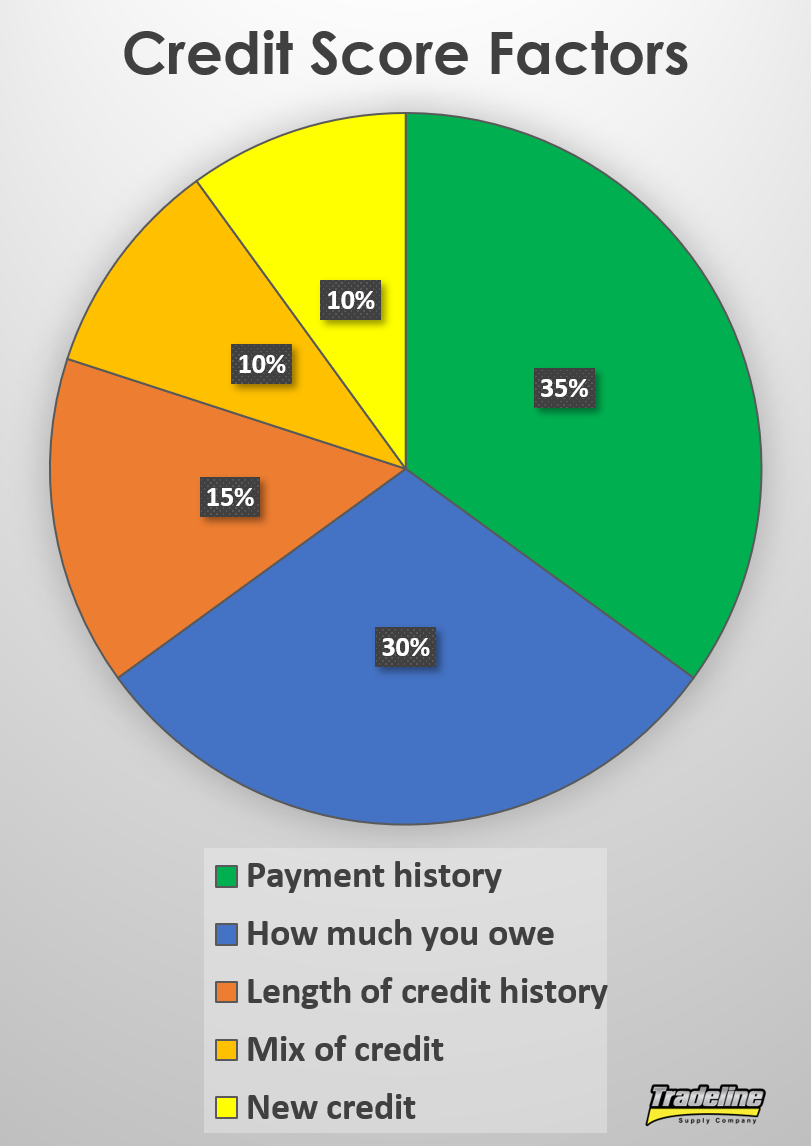
Managing Credit Utilization During Emergencies
In times of emergencies, it’s common for individuals to rely on credit cards to cover unexpected expenses. While credit cards can be a useful tool in such situations, it is important to manage your credit utilization wisely to avoid potential financial pitfalls down the road. Here are some key points to consider when using credit during emergencies:
1. Evaluate your available credit: Before making any decisions, assess how much unused credit you have across all your cards. This will give you an idea of how much capacity you have left and help you plan accordingly.
2. Prioritize essential expenses: Determine which expenses are absolutely necessary and allocate funds towards those first. Focus on covering essentials like food, shelter, healthcare, and utilities before considering non-essential purchases.
3. Create a budget: Establishing a realistic budget is crucial during an emergency situation. Calculate your income and compare it with your expenses to ensure that you’re not overspending or accruing unnecessary debt.
4. Communicate with creditors: If you anticipate difficulty in meeting minimum payments due to the emergency situation, contact your creditors as soon as possible. Many lenders offer hardship programs or temporary relief options that may help alleviate some financial stress.
5. Avoid maxing out your cards: While it can be tempting to use up all available credit during tough times, maxing out your cards negatively impacts your credit utilization ratio — the amount of available credit compared to outstanding balances — which influences your overall credit score negatively.
6. Limit unnecessary spending: During emergencies, try to minimize discretionary expenditures such as eating out or buying non-essential items until things stabilize financially.
7. Explore other sources of funding: Consider alternative ways of accessing funds before relying solely on high-interest credit cards. These could include personal loans from banks or online lenders at potentially lower interest rates.
8. Monitor statements regularly: Keep a close eye on all account statements for accuracy and fraudulent activities during and after the emergency. Report any suspicious transactions to your card issuer immediately.
9. Pay on time: Aim to make at least the minimum payment on all credit cards by the due date, even if it means making smaller payments across multiple cards. This will help you maintain a good payment history and avoid penalties or increased interest rates.
10. Reevaluate your financial plan: After the emergency is resolved, take some time to reassess your overall financial situation and adjust your budget accordingly. Building an emergency fund for future unforeseen events should be a priority moving forward.
Remember, managing credit utilization during emergencies requires careful consideration of your financial situation and prioritizing necessities over luxuries. With responsible planning and disciplined spending habits, you can navigate through challenging times while minimizing long-term negative impacts on your credit health.