“Choosing the Right Retirement Account: Solo 401(k) vs. SEP IRA for Self-Employed Individuals”
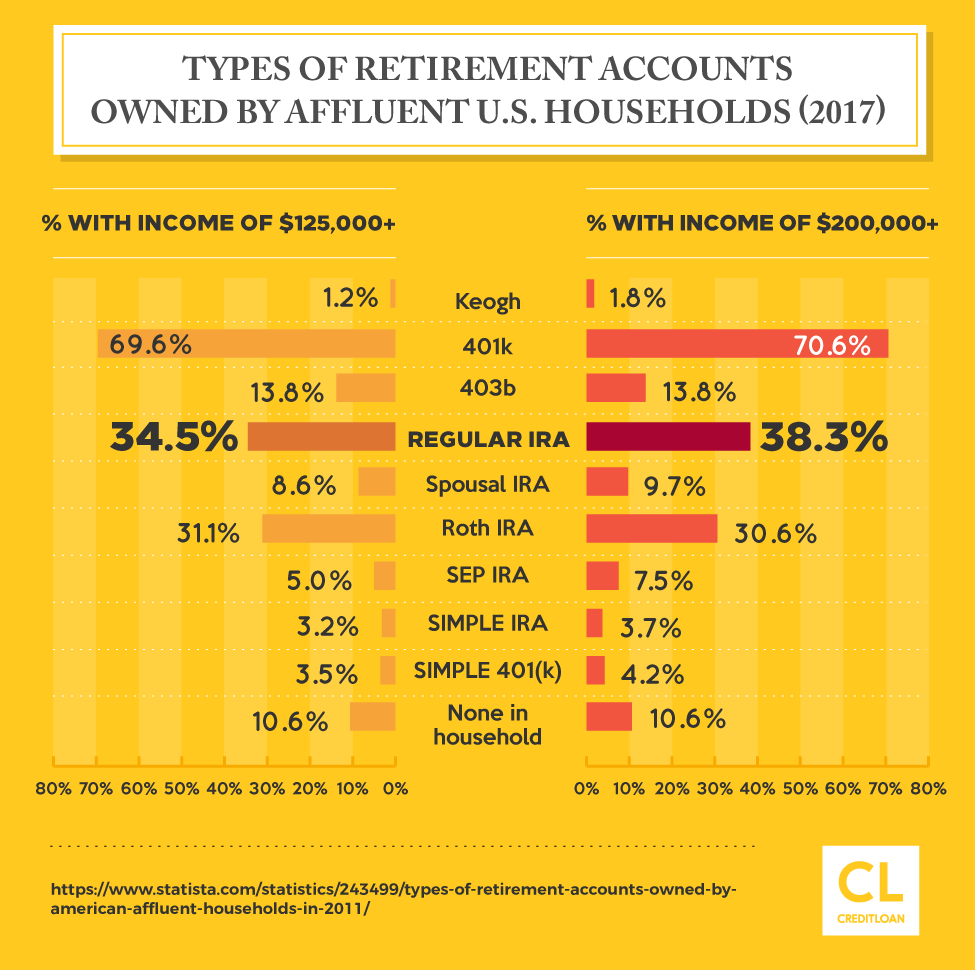
As a self-employed individual, planning for retirement is crucial. Two popular retirement account options for the self-employed are the Solo 401(k) and SEP IRA. Both offer tax advantages and flexibility, but they have some key differences.
The Solo 401(k), also known as an Individual 401(k), is designed specifically for business owners with no employees other than their spouse. It allows higher contribution limits compared to a SEP IRA. In 2021, you can contribute up to $58,000 ($64,500 if over age 50) or 100% of your self-employment income, whichever is less. This includes both employee and employer contributions.
On the other hand, a SEP IRA allows contributions up to $58,000 in 2021 (up to 25% of compensation or net self-employment earnings). While it has lower contribution limits for the employer portion compared to a Solo 401(k), it offers more flexibility when it comes to hiring employees in the future since you can include them in your plan.
Another significant difference lies in how these accounts handle loans. With a Solo 401(k), you may be able to borrow against your account balance like a traditional employer-sponsored plan. However, with a SEP IRA, borrowing is not allowed.
Both plans offer tax advantages such as deductible contributions and tax-deferred growth potential until retirement withdrawals begin. However, keep in mind that both types of accounts require you to pay taxes on distributions taken during retirement.
Ultimately, choosing between a Solo 401(k) and SEP IRA depends on various factors including your income level, future hiring plans, and desire for loan access from the account. Consulting with a financial advisor who specializes in retirement planning can help determine which option best suits your unique needs and goals.