Mastering the Art of Capital Losses: Key Strategies for Effective Investment Management
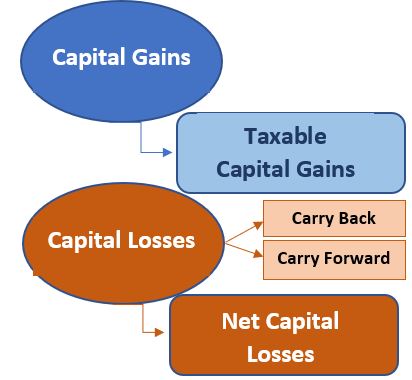
When it comes to investing, understanding the difference between long-term and short-term capital losses is essential for managing your finances effectively. Capital losses occur when you sell an investment for less than what you paid for it. These losses can be offset against capital gains to reduce your overall tax liability.
Long-Term Capital Losses:
Let’s begin by exploring long-term capital losses. A long-term loss occurs when you hold an investment for more than one year before selling it at a lower price. The specific time period required to classify as a long-term investment may vary depending on your country’s tax laws.
One significant advantage of long-term capital losses is that they are taxed at a lower rate compared to short-term losses. In many countries, including the United States, the tax rate on long-term capital gains is generally lower than ordinary income tax rates. This means that if you have incurred a net capital loss from your investments over one year, it can help offset any taxable gains and potentially reduce your overall tax bill.
Another benefit of long-term capital losses is that they can be carried forward indefinitely in some jurisdictions. If you have more long-term losses than gains in a given year, you can use those excess losses to offset future years’ taxable income or even carry them forward until retirement when your income might be lower.
Short-Term Capital Losses:
On the other hand, short-term capital losses occur when you sell an investment within one year of acquiring it at a lower price than what you initially paid. Unlike their long-term counterparts, these types of losses are subject to higher tax rates as they are considered part of ordinary income.
Short-term capital gains are typically taxed at the same rate as regular income—your marginal tax bracket—which could result in higher taxes being owed on these gains compared to longer-held investments.
Unlike with long-terms loses, where there may be flexibility in carrying them forward indefinitely, most jurisdictions limit how much short-term capital loss can be used to offset taxable income in a given year. In the United States, for example, you can use up to $3,000 of short-term losses each year to reduce your taxable income. Any remaining losses after this limit is applied can be carried forward into future years.
Strategies for Capital Losses:
Now that we understand the difference between long-term and short-term capital losses let’s explore some strategies for managing these investment losses effectively:
1. Tax-Loss Harvesting: This strategy involves strategically selling investments at a loss to offset any capital gains you may have realized throughout the year. By doing so, you can minimize your overall tax liability while staying invested.
2. Asset Location: Consider locating investments with potential capital gains in tax-advantaged accounts like Individual Retirement Accounts (IRAs) or 401(k)s where gains are sheltered from immediate taxation. On the other hand, holdings with expected losses could be placed in taxable accounts to take advantage of potential deductions.
3. Diversification: Maintaining a well-diversified portfolio spread across different asset classes and sectors helps mitigate risks associated with individual investment performance. If one investment incurs a significant loss, it may be balanced out by positive returns from other holdings.
4. Consult an Advisor: Seeking guidance from a financial advisor or tax professional can provide valuable insights into managing your investments and optimizing tax benefits related to capital gains and losses.
It’s important to note that while minimizing taxes is essential when investing, it should not drive all decisions regarding buying or selling securities solely for tax purposes alone. It’s crucial always to consider your overall investment goals and risk tolerance before making any decisions.
In conclusion, understanding long-term and short-term capital losses is key to effectively manage your investments’ tax implications. While long-term losses offer more flexibility in terms of carry-forward options and lower tax rates, short-term losses are limited in their deductibility. By employing strategies like tax-loss harvesting, asset location, diversification, and seeking professional advice, you can optimize your investment decisions and minimize your overall tax liability.