Mastering Self-Employment Taxes: The Key to Financial Success
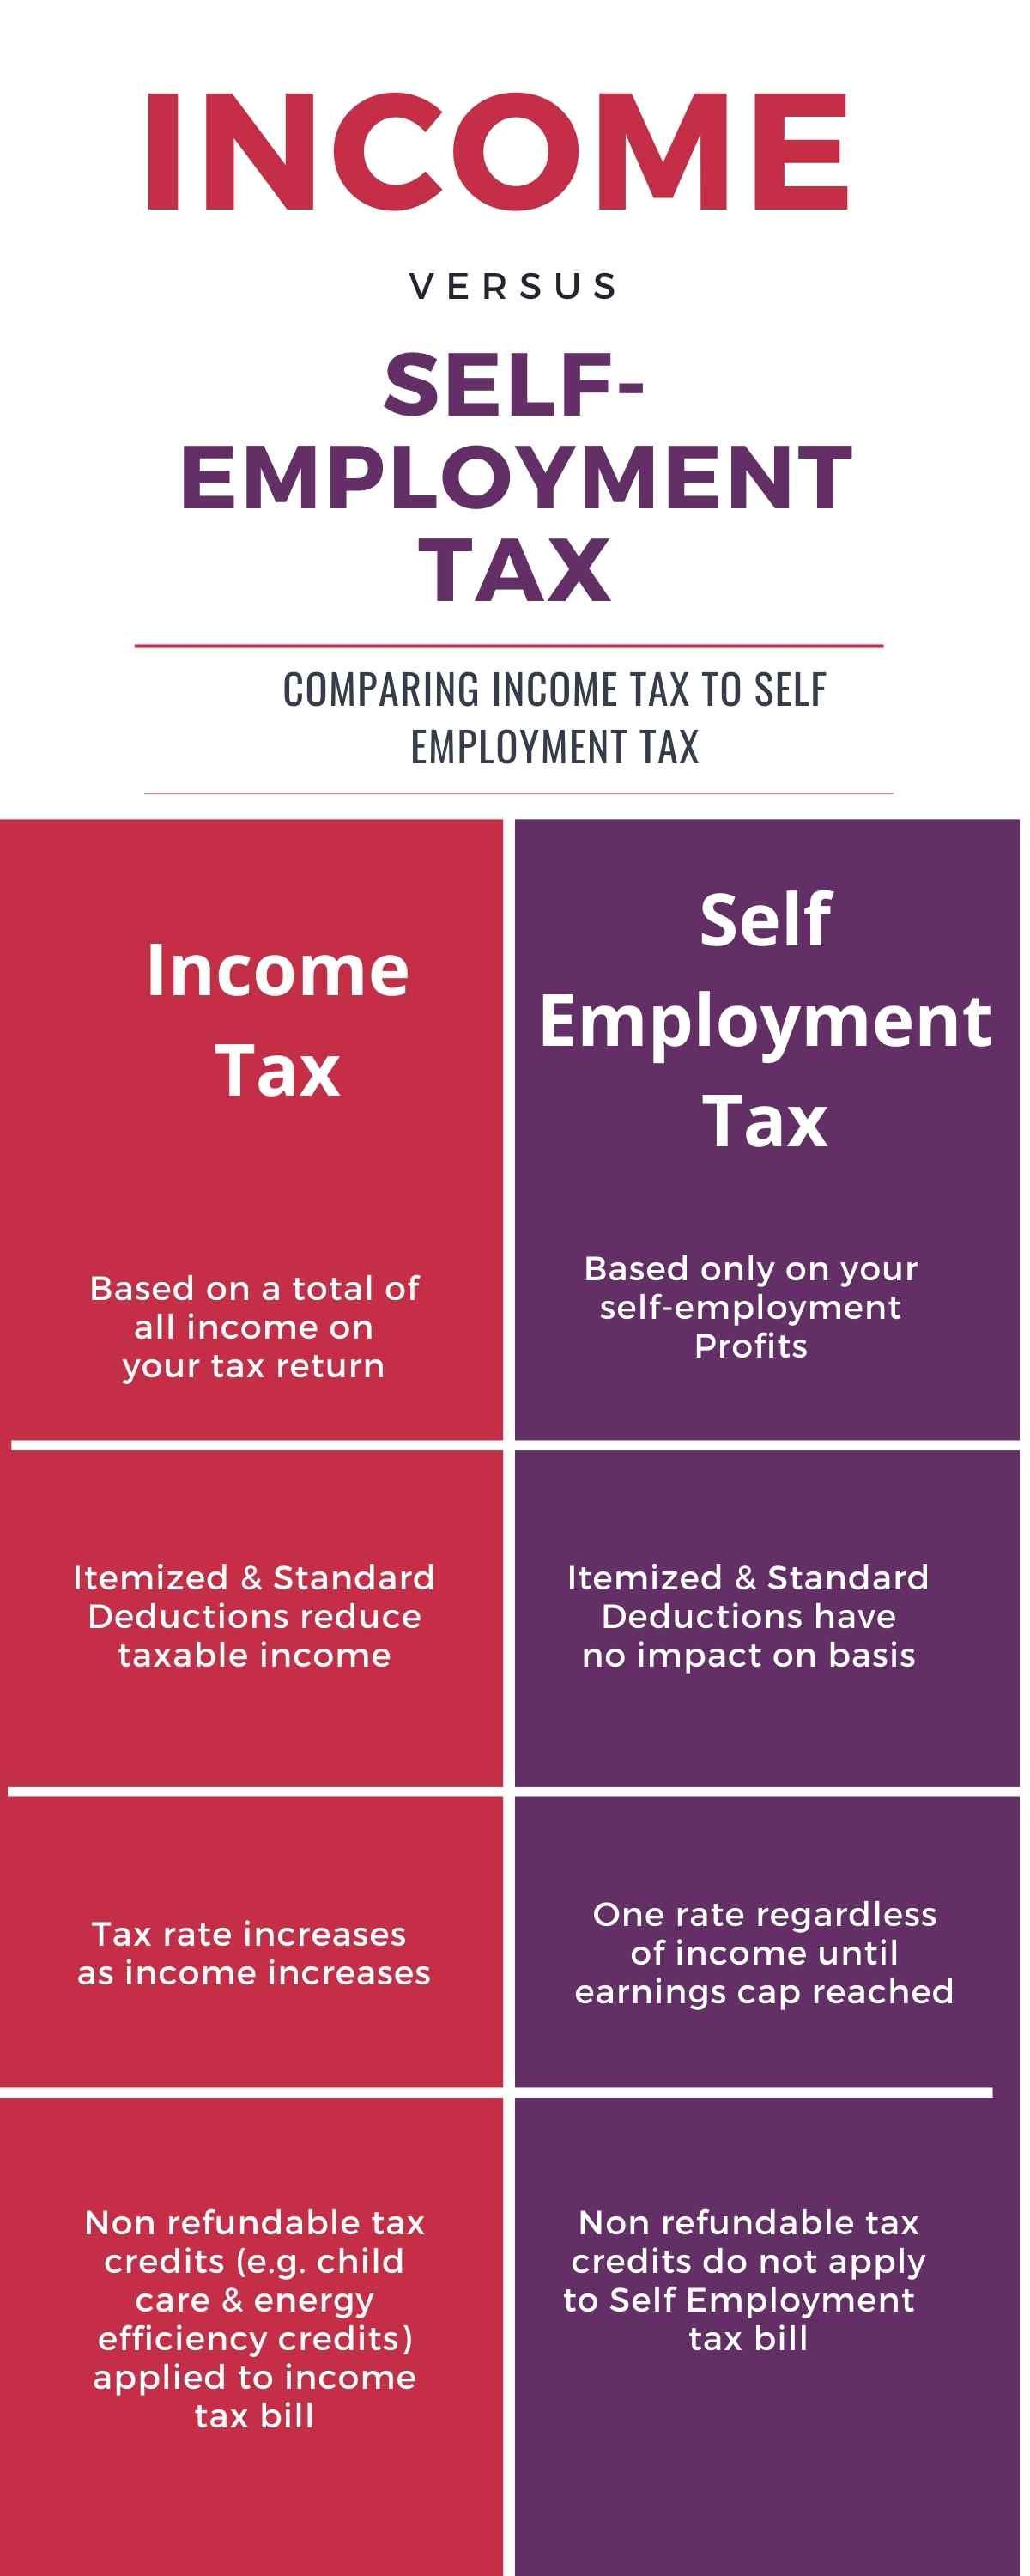
Self-employment Taxes: Understanding the Basics
When it comes to being self-employed, there are several financial responsibilities that may differ from those of traditional employees. One crucial aspect is understanding and managing self-employment taxes. Unlike employees who have their income taxes withheld by their employers, self-employed individuals are responsible for paying their own taxes directly to the government.
1. What Are Self-Employment Taxes?
Self-employment taxes consist of two components: Social Security and Medicare taxes, collectively known as the Self-Employment Tax (SE tax). These taxes cover your contributions towards these social programs and are typically paid by both employees and employers in traditional employment arrangements.
2. Calculating Self-Employment Taxes
To calculate your SE tax liability, you need to determine your net earnings from self-employment. This figure represents the profit generated from your business after deducting allowable expenses. The SE tax is then calculated as a percentage of this net income.
3. The Current Rates
As of 2021, the SE tax rate is set at 15.3% of your net earnings from self-employment. However, only a portion of this amount is deductible for income tax purposes—currently up to 7.65%. The remaining 7.65% represents the Social Security and Medicare contribution that would have been covered by an employer in a traditional job setting.
4. Reporting Income and Paying Taxes
As a self-employed individual, you must report your income on Schedule C or Schedule C-EZ attached to your annual personal income tax return (Form 1040). Additionally, if you anticipate owing $1,000 or more in total tax liability for the year after considering any withholding or refundable credits, you might also be required to make quarterly estimated tax payments throughout the year.
5. Estimated Tax Payments
Making quarterly estimated tax payments helps prevent underpayment penalties when filing your annual return due to not meeting the required tax liability threshold. These payments are typically due in April, June, September, and January and should reflect your projected income for the year.
6. Deductible Business Expenses
One advantage of being self-employed is that you can deduct legitimate business expenses from your taxable income. Common deductible expenses include office supplies, equipment, professional fees, advertising costs, and travel expenses directly related to your business activities.
7. Self-Employment Tax Deduction
To alleviate some of the burden imposed by self-employment taxes, there is a provision that allows self-employed individuals to deduct half of their SE tax liability when calculating their adjusted gross income (AGI). This deduction helps reduce both federal income taxes and self-employment taxes.
8. Additional Medicare Tax
In addition to the regular SE tax rate of 15.3%, high-income earners may be subject to an additional 0.9% Medicare Tax on earnings exceeding certain thresholds ($200,000 for individual filers or $250,000 for married couples filing jointly). This additional tax applies only to the portion of income above these thresholds.
9. State and Local Taxes
While this article primarily focuses on federal self-employment taxes, it’s important to consider state and local tax obligations as well. Each state has its own rules regarding taxation for self-employed individuals; some states have no income tax at all while others impose various rates based on earnings.
10. Retirement Savings Options
As a self-employed individual without access to employer-sponsored retirement plans such as a 401(k), it’s crucial to plan for your future financial security independently. Consider options like Simplified Employee Pension (SEP) IRAs or solo 401(k)s that allow you to contribute pre-tax dollars towards retirement savings while potentially reducing your taxable income.
11. Keeping Accurate Records
Maintaining accurate records is essential when it comes time to calculate your net earnings from self-employment or substantiate any deductions. Keep detailed records of your income, expenses, and tax payments so you can easily prepare your tax returns and defend any claims in the event of an audit.
12. Seeking Professional Advice
Due to the complexities involved in self-employment taxes, it’s advisable to consult with a qualified tax professional or accountant who specializes in small business taxation. They can help ensure you comply with all legal requirements, maximize deductions, and develop strategies to minimize your overall tax burden.
In conclusion, understanding self-employment taxes is crucial for anyone venturing into entrepreneurship or working as an independent contractor. By familiarizing yourself with the basics of calculating and reporting these taxes while exploring available deductions and retirement savings options, you can navigate this aspect of self-employment successfully while maintaining compliance with applicable laws.