Mastering Credit Utilization: A Comprehensive Guide for Self-Employed Individuals
Credit Utilization for Self-Employed Individuals: A Comprehensive Guide
Introduction
Managing personal finances can be a challenge, especially when you are self-employed. One crucial aspect of financial management is understanding and effectively utilizing credit. This guide will provide an in-depth explanation of credit utilization for self-employed individuals, covering what it is, how it affects your credit score, tips to optimize it, and potential pitfalls to avoid.
What is Credit Utilization?
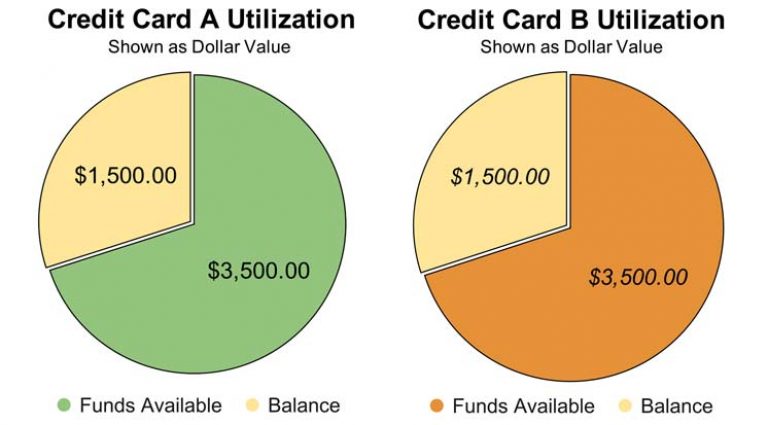
Credit utilization refers to the ratio between your outstanding credit card balances and your total available credit limit. It is a significant factor that influences your credit score and plays a vital role in lenders’ decisions when assessing your creditworthiness.
For example, if you have two credit cards with limits of $5,000 each and carry a combined balance of $3,000 across both cards, your total available credit limit would be $10,000 ($5,000 + $5,000), and your current utilization rate would be 30% ($3,000 ÷ $10,000).
How Does Credit Utilization Affect Your Credit Score?
Your credit utilization ratio has a considerable impact on your overall credit score. In fact, it accounts for approximately 30% of the FICO scoring model. Lenders consider lower ratios as indicators of responsible borrowing behavior.
A high utilization rate suggests that you may rely too heavily on borrowed funds or potentially struggle to repay debts promptly. On the other hand, maintaining a low ratio demonstrates financial stability and responsibility.
Optimizing Credit Utilization
1. Keep Track of Your Spending Patterns:
Self-employed individuals often experience inconsistent income streams due to varying client payments or seasonal fluctuations in their business. Consequently, tracking spending patterns becomes even more critical for effective budgeting.
By monitoring expenses regularly using accounting software or spreadsheets tailored to track business expenditures separately from personal ones (if applicable), you gain better control over cash flow management and can plan accordingly to avoid reliance on credit.
2. Set a Budget:
Creating a budget is crucial for any individual, but it becomes even more essential when you are self-employed. Consider all your business and personal expenses while setting financial goals. Allocate funds to cover both necessities and future savings consistently.
By adhering to a realistic budget, you can minimize the chances of overspending and reduce the need to rely on credit cards excessively.
3. Separate Personal and Business Finances:
As a self-employed individual, separating your personal finances from your business finances is highly recommended. Opening separate bank accounts for personal and business use streamlines record-keeping, simplifies tax filings, ensures accuracy in expense tracking, and provides clarity when calculating credit utilization rates specifically related to business expenditures.
4. Pay Your Bills on Time:
Late payments have adverse effects on your credit score regardless of whether you are self-employed or not. Ensure that all bills—personal or business-related—are paid promptly by setting reminders or automating payments where possible.
Consistently paying bills on time helps maintain a positive payment history, which bolsters your creditworthiness over time by minimizing negative marks against your profile.
5. Monitor Credit Utilization Ratio Regularly:
Keeping tabs on your credit utilization ratio is crucial for maintaining good financial health as a self-employed individual. Reviewing this metric periodically allows you to make necessary adjustments if it starts trending upward.
If you notice an increasing trend in utilization due to large purchases or temporary cash flow challenges, consider making multiple payments throughout the month instead of waiting until the due date to lower outstanding balances faster.
Potential Pitfalls
1. Overreliance on Credit Cards:
While using credit cards can be convenient for managing expenses, relying too heavily on them can lead to debt accumulation and high utilization ratios if balances are not paid off promptly each month.
To prevent this scenario, exercise caution in charging expenses only up to what you can afford without carrying revolving balances. This practice ensures that your credit utilization ratio remains low and manageable.
2. Applying for Multiple Credit Accounts Simultaneously:
As a self-employed individual, you may be tempted to apply for multiple credit accounts to expand your business or cover unforeseen expenses. However, submitting several applications within a short period triggers hard inquiries on your credit report, temporarily lowering your credit score.
Instead, evaluate your needs carefully before applying for new lines of credit and consider seeking advice from financial professionals to explore alternative financing options.
Conclusion
Credit utilization is an essential aspect of managing personal finances effectively as a self-employed individual. By understanding its significance and implementing strategies to optimize it, you can improve your creditworthiness, strengthen your financial standing over time, and access better borrowing opportunities when needed. Remember to track spending patterns, set realistic budgets, separate personal and business finances, pay bills on time consistently, monitor utilization ratios regularly, and avoid potential pitfalls associated with excessive reliance on credit cards or haphazardly applying for new lines of credit.