Unlock the Secrets to Securing the Best Auto Loan Interest Rates
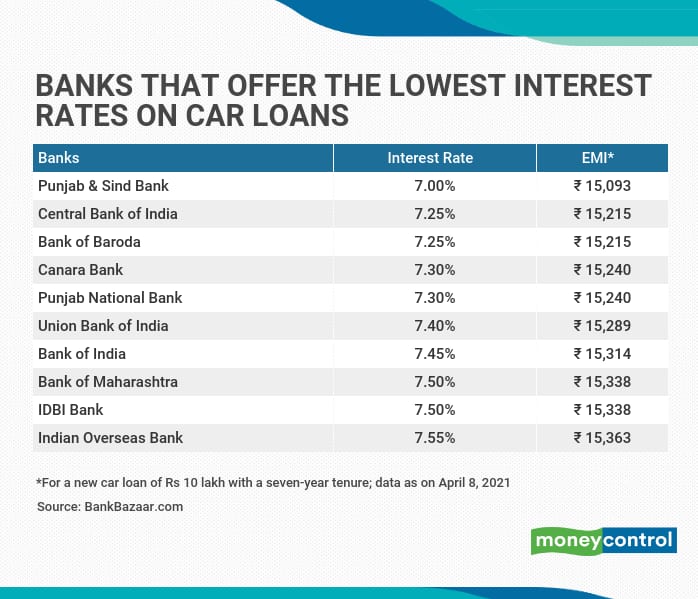
Auto Loan Interest Rates: A Comprehensive Guide
Introduction:
Purchasing a car is a significant financial decision for many individuals. For most people, buying a vehicle outright with cash is not feasible, which leads to the need for an auto loan. When taking out an auto loan, one of the crucial factors to consider is the interest rate. Auto loan interest rates can have a substantial impact on your monthly payments and the overall cost of financing your vehicle.
In this comprehensive guide, we will explore everything you need to know about auto loan interest rates – how they are determined, what factors affect them, and how you can secure the best possible rate.
Understanding Auto Loan Interest Rates:
Auto loan interest rates are essentially fees charged by lenders for borrowing money to purchase a vehicle. These rates are expressed as an annual percentage and represent the cost of borrowing over time. The lower the interest rate, the less expensive it is to borrow money.
Factors that Influence Auto Loan Interest Rates:
Several factors determine your auto loan interest rate. Understanding these factors will help you make informed decisions when applying for an auto loan:
1. Credit Score:
Your credit score plays a significant role in determining your interest rate. Lenders use credit scores as indicators of creditworthiness – higher scores often result in lower interest rates because borrowers with good credit histories tend to be less risky from a lender’s perspective.
2. Loan Term:
The length or term of your auto loan affects your interest rate too. Generally, shorter-term loans carry lower interest rates compared to longer-term loans since lenders assume less risk with shorter repayment periods.
3. Down Payment:
The size of your down payment also influences your eligibility for better terms and conditions on an auto loan. A larger down payment reduces both the amount borrowed and perceived risk by lenders, potentially leading to more favorable rates.
4. Vehicle Age:
Newer vehicles typically qualify for lower rates than older ones due to their higher resale value and lower risk of mechanical issues. Lenders may charge higher interest rates for used vehicles, especially those beyond a certain age or mileage.
5. Market Conditions:
Fluctuations in the overall economy, including interest rate shifts set by central banks, can impact auto loan interest rates. It’s essential to keep an eye on market conditions before applying for an auto loan to take advantage of favorable times.
Types of Interest Rates:
When obtaining an auto loan, you’ll come across two types of interest rates: fixed and variable.
1. Fixed Interest Rates:
Fixed interest rates remain constant throughout the life of your loan, ensuring predictable monthly payments. These rates are generally recommended for borrowers who prefer stability and want to avoid potential increases in future payments due to market fluctuations.
2. Variable Interest Rates:
Variable interest rates fluctuate based on changes in the market index or benchmark rate (e.g., Prime Rate). While they may start at a lower rate than fixed rates, they carry more uncertainty as repayment amounts can increase if the index rises over time.
Securing the Best Auto Loan Interest Rate:
Now that we understand the factors influencing auto loan interest rates let’s explore some strategies to help secure a favorable rate:
1. Improve Your Credit Score:
Before applying for an auto loan, review your credit history and take steps to improve your credit score if necessary. Paying bills on time, reducing outstanding debt balances, and correcting any errors on your credit report can lead to better terms and lower interest rates.
2. Shop Around for Multiple Lenders:
Don’t settle for the first lender you encounter; instead, shop around and compare offers from several financial institutions or lenders. Each lender has different criteria when setting their interest rates; therefore, it’s crucial to explore all available options before making a decision.
3. Make a Larger Down Payment:
Consider saving up for a larger down payment as it not only reduces the amount borrowed but also demonstrates financial stability to lenders. A substantial down payment can help negotiate better terms and lower interest rates.
4. Consider Shorter Loan Terms:
While longer loan terms may seem appealing due to lower monthly payments, they often come with higher interest rates. Opting for a shorter loan term can result in significant savings over the life of the loan.
5. Pay Attention to Market Conditions:
Keep an eye on market conditions and any potential changes in interest rates before applying for an auto loan. Timing your application during periods of low-interest rates could help you secure a more favorable rate.
Conclusion:
Auto loan interest rates are critical factors that influence the cost of financing your vehicle purchase. Understanding how these rates are determined and what factors affect them is vital when embarking on this financial journey. By improving your credit score, shopping around for multiple lenders, making a larger down payment, considering shorter loan terms, and paying attention to market conditions, you can increase your chances of securing the best possible auto loan interest rate that fits your budget and needs. Remember, conducting thorough research and seeking guidance from financial professionals will empower you to make informed decisions throughout this process.