Unlock Your Home’s Value: Reverse Mortgage for a Comfortable Retirement
Reverse Mortgage: A Smart Financial Solution for Seniors
Introduction:
As individuals reach retirement age, one of the key concerns they often face is how to supplement their income. With rising healthcare costs and a longer lifespan, it becomes crucial for seniors to explore financial options that can provide them with a comfortable retirement. One such option worth considering is a reverse mortgage.
What is a Reverse Mortgage?
A reverse mortgage is a financial product designed specifically for homeowners aged 62 or older. It enables them to convert part of their home equity into cash without having to sell the property or make monthly mortgage payments. Instead, the loan balance gradually increases over time as interest accrues. The loan only becomes due when the homeowner moves out permanently, sells the property, or passes away.
How Does it Work?
To be eligible for a reverse mortgage, homeowners must have substantial equity in their homes and live in the residence as their primary residence. The maximum amount that can be borrowed depends on several factors including the borrower’s age, home value, current interest rates, and lending limits set by federal agencies.
The borrower has multiple options for receiving funds from a reverse mortgage:
1. Lump Sum: This allows borrowers to receive all available funds at once.
2. Line of Credit: Borrowers can access funds whenever needed up to an approved limit.
3. Monthly Payments: Regular fixed payments are made directly to the borrower.
4. Combination: A combination of any two or more payment methods may also be chosen.
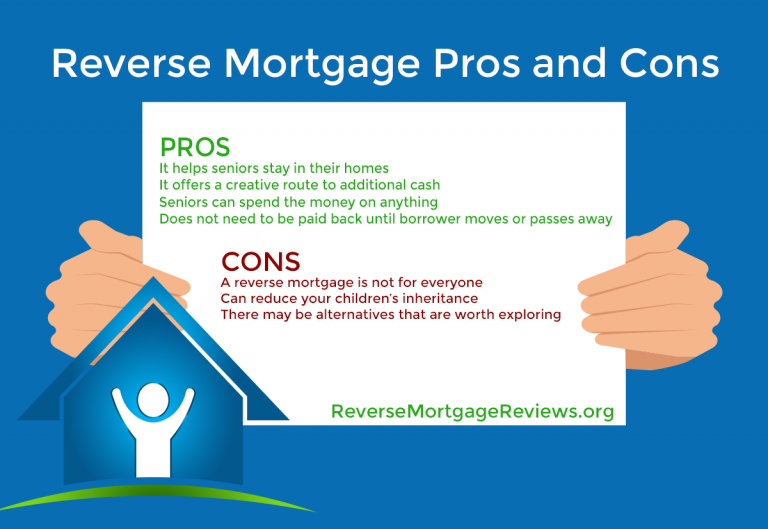
Pros of Reverse Mortgages:
1. Supplement Retirement Income: For many seniors who are struggling financially during retirement, a reverse mortgage offers an excellent way to supplement their income without selling their homes.
2. Flexibility in Fund Usage: Borrowers have complete freedom regarding how they use these funds – whether it’s covering medical expenses, paying off debts, renovating their homes or even taking vacations.
3. No Loan Repayment Until Home Sale or Move-Out: Borrowers are not required to make monthly mortgage payments as long as they live in the home. The loan only becomes due when the borrower permanently moves out or passes away.
4. Tax-Free Loan Proceeds: Reverse mortgage proceeds are generally considered loan advances rather than income, so they are not taxable.
5. Non-Recourse Loan: Reverse mortgages are non-recourse loans, which means that borrowers (or their heirs) will never owe more than the value of the home at the time of repayment.
Cons of Reverse Mortgages:
1. Higher Interest Rates and Fees: Compared to traditional mortgages, reverse mortgages often have higher interest rates and fees attached to them, making them a relatively expensive option.
2. Potential Impact on Heirs’ Inheritance: Since reverse mortgages accrue interest over time, it is possible that there may be little or no equity left in the property for heirs after repayment.
3. Home Ownership Obligations: Borrowers must continue paying property taxes, insurance premiums, and maintaining their homes while also staying current on any existing mortgage obligations.
4. Limited Eligibility Criteria: Reverse mortgages are only available to homeowners aged 62 or older who have sufficient equity in their homes and intend to live there as their primary residence.
Is a Reverse Mortgage Right for You?
A reverse mortgage can be an ideal financial solution for seniors who need additional income during retirement and wish to remain in their homes without selling them. However, it is important to consider individual circumstances before deciding if a reverse mortgage is right for you.
Here are some questions you should ask yourself:
1. Do I plan on living in my current home for an extended period?
2. Am I aware of all applicable costs including origination fees, closing costs, servicing fees, etc., associated with obtaining a reverse mortgage?
3. Have I explored alternative options such as downsizing or renting out part of my property?
4. Can I afford the ongoing costs of maintaining my home?
5. Have I discussed this decision with my family and financial advisor?
Conclusion:
A reverse mortgage can be an effective tool for seniors to improve their financial situation during retirement. It provides a way to access home equity without sacrificing homeownership or making monthly mortgage payments. However, it is crucial to carefully evaluate personal circumstances, consider alternatives, and seek professional advice before committing to a reverse mortgage. By doing so, seniors can make an informed decision that aligns with their long-term financial goals and ensures a comfortable retirement.