Unveiling the Secrets of Net Income: Boost Your Financial Health
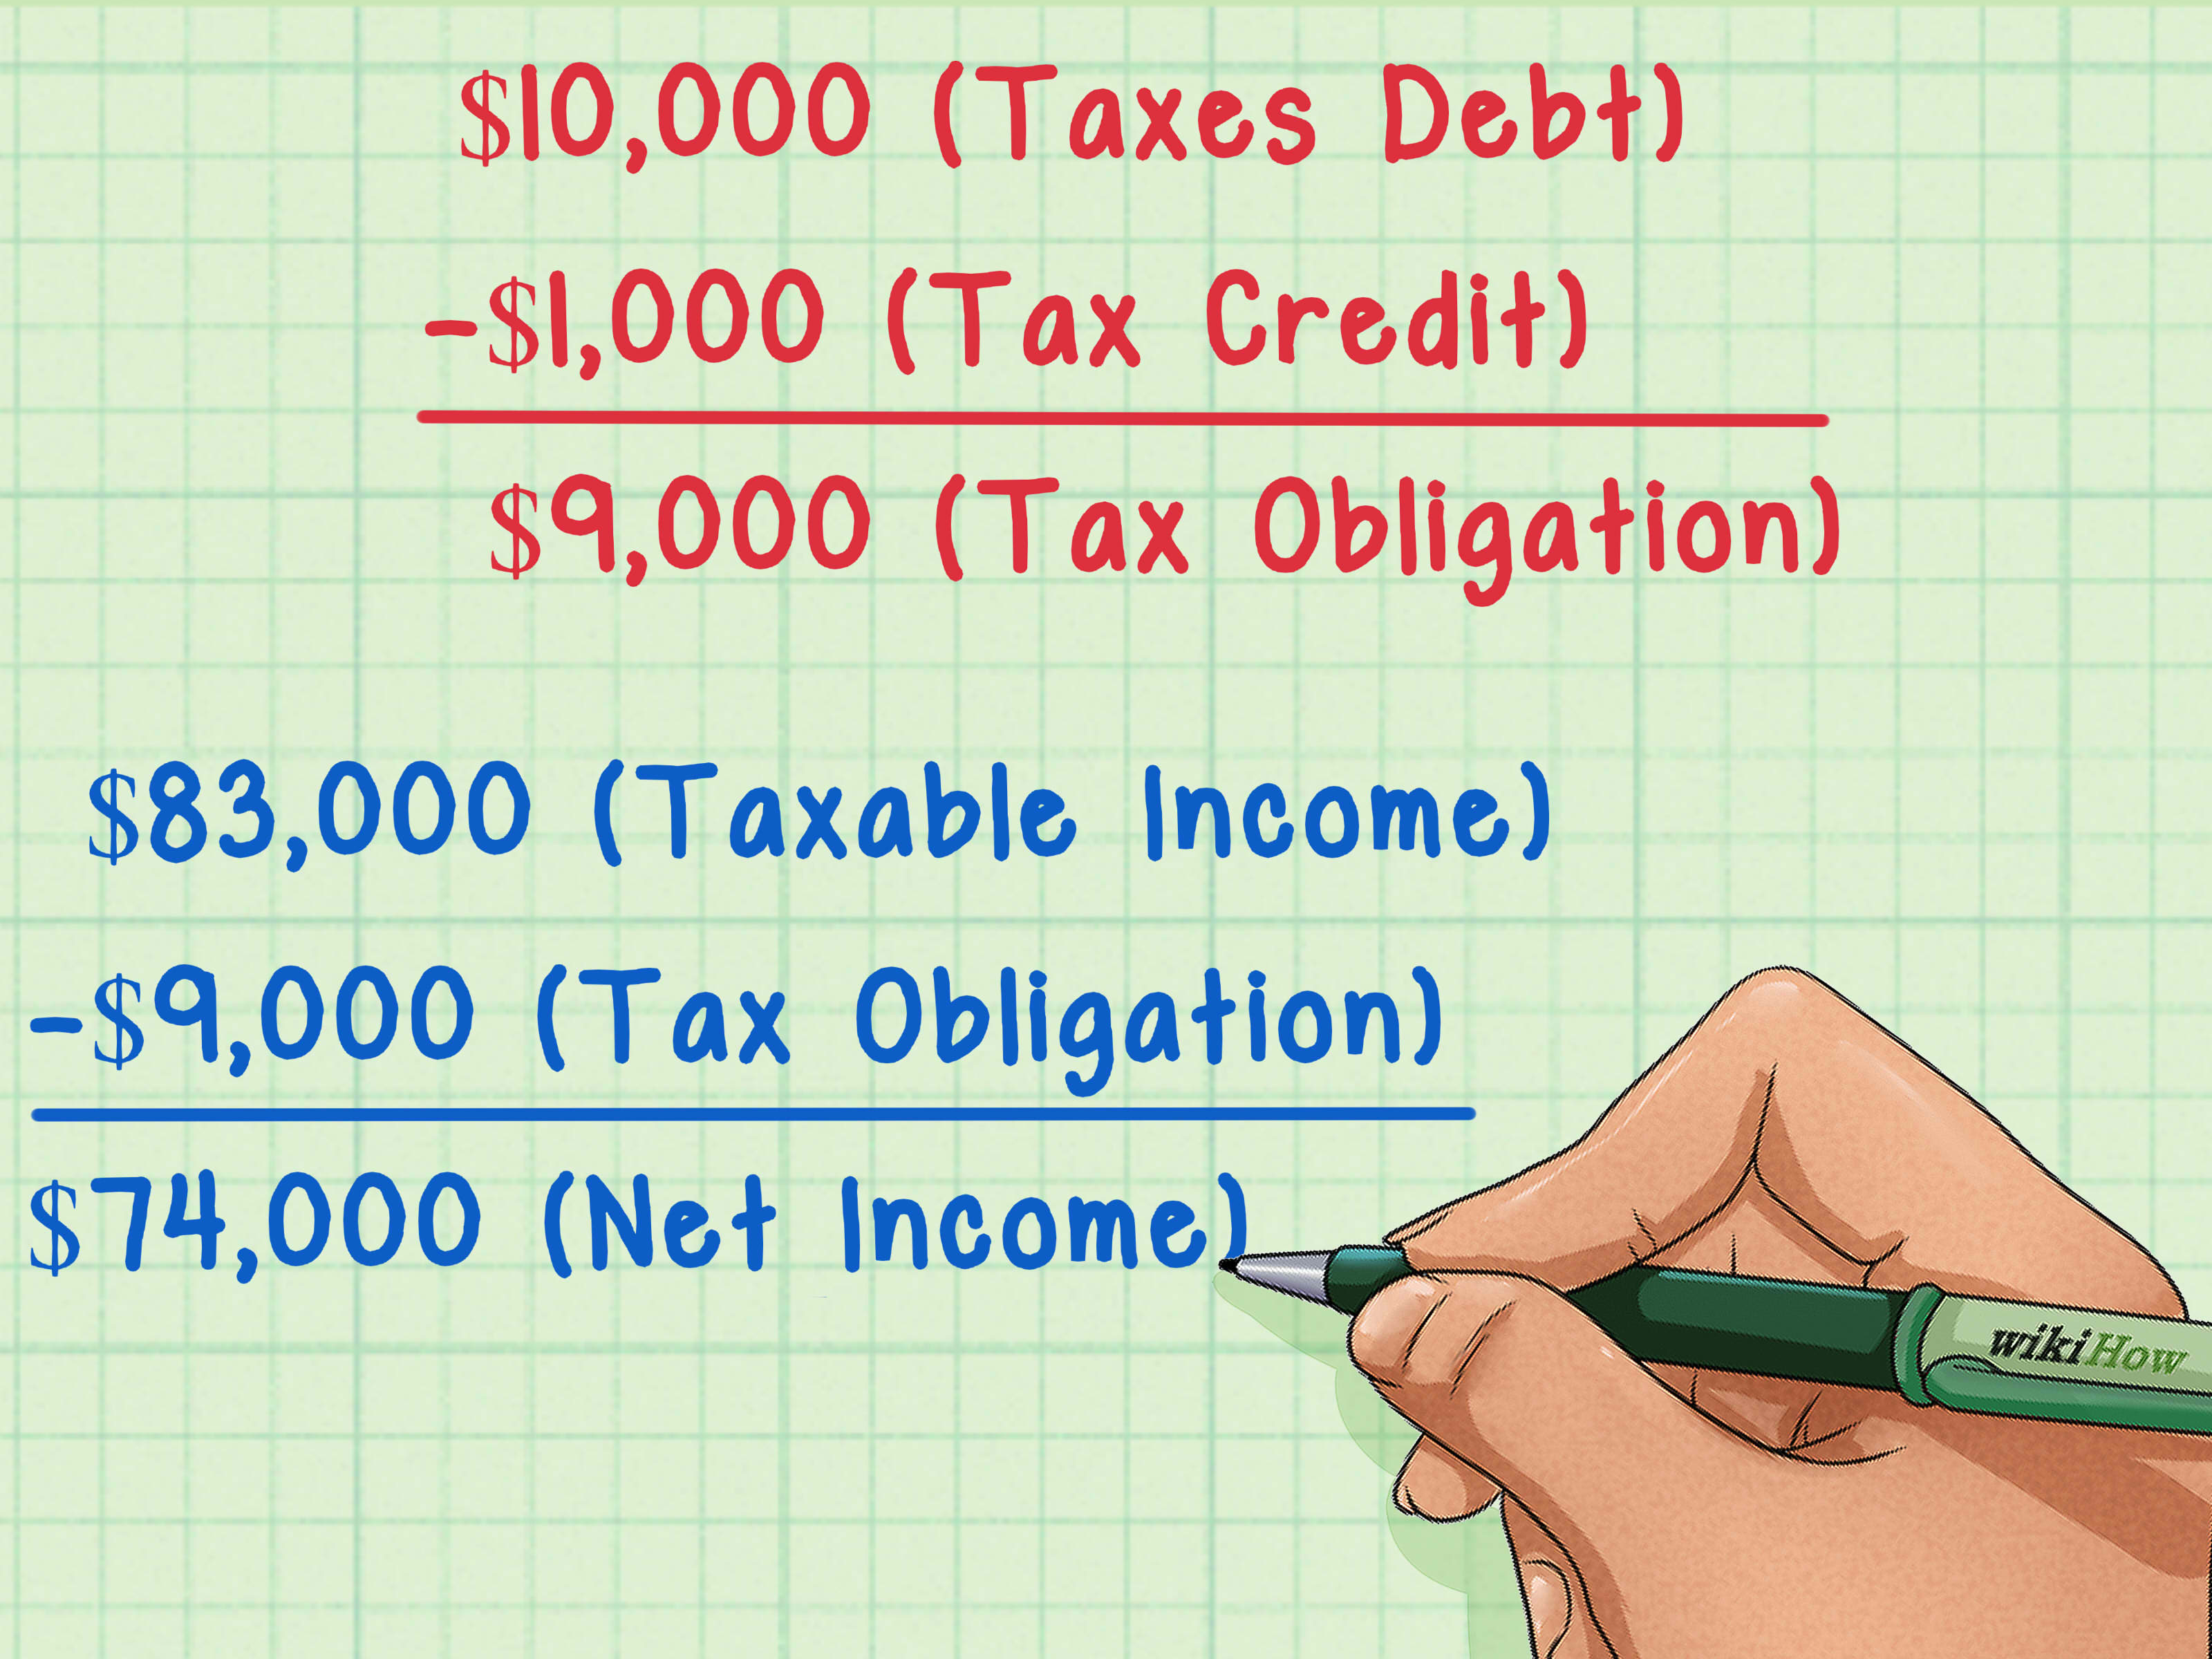
Understanding net income calculations
Net income is a crucial financial metric that provides individuals with an accurate measure of their overall financial health. It represents the amount of money left over after subtracting all expenses, taxes, and deductions from total income. In simple terms, net income is what remains in your pocket at the end of the day.
To calculate net income, you start with your gross income. Gross income includes all sources of revenue such as salary, wages, tips, rental incomes, and any other form of earnings before any deductions are made. From this figure, you deduct various expenses including but not limited to taxes (federal, state, local), insurance premiums (health or life insurance), retirement contributions (e.g., 401(k)), and other necessary expenditures. Once these deductions have been subtracted from your gross income, you arrive at your net income.
Importance of tracking and analyzing net income
Tracking and analyzing net income is essential for several reasons:
1. Financial awareness: By regularly monitoring your net income, you gain a clear understanding of how much money you are actually bringing home each month or year. This helps you make informed decisions about budgeting and spending habits.
2. Planning for the future: Net income plays a vital role in planning for long-term financial goals such as saving for retirement or purchasing a home. Understanding your current net income allows you to set realistic targets based on what is feasible within your means.
3. Identifying areas for improvement: Analyzing your net income can reveal opportunities to reduce expenses or increase earnings by identifying areas where adjustments can be made.
Strategies to increase net income
Increasing your net Income can significantly improve your financial situation over time. Here are some strategies to consider:
1. Negotiate a raise: If possible within your current employment context, negotiate a higher salary or hourly wage with your employer based on factors such as performance reviews or industry standards.
2. Seek additional income streams: Consider taking on a side hustle or freelance work to supplement your primary source of income.
3. Enhance your skills: Invest in education and training to improve your qualifications, making yourself more valuable and marketable in the job market.
4. Start investing: Explore investment opportunities such as stocks, bonds, real estate, or mutual funds that have the potential to generate passive income over time.
Net income vs. gross income: What’s the difference?
Gross Income refers to the total amount of money earned before any deductions are made. It is often expressed as an annual figure and includes all sources of revenue, including wages, salaries, bonuses, rental income, royalties, and dividends. Gross income does not take into account any expenses incurred during the earning process.
On the other hand, net income is what remains after subtracting all necessary expenses (taxes included) from gross income. Net income provides a more accurate picture of an individual’s financial situation since it reflects their actual earnings after accounting for various deductions.
How to calculate net income for self-employed individuals
Calculating net Income for self-employed individuals follows a similar process as calculating net Income for those who receive regular paychecks; however, it involves additional considerations:
1. Track business-related expenses: Self-employed individuals should keep meticulous records of their business-related expenses throughout the year. This includes costs such as office space rent/mortgage payments/utilities/insurance premiums/office supplies/travel expenses/marketing costs/professional fees/vehicle expenses etc.
2. Calculate gross revenue: Add up all sources of business-related revenue received throughout the year.
3. Subtract business-related expenses from gross revenue: Deduct all documented business-related expenses from gross revenue to arrive at your net profit (or loss). If you end up with a positive number after deducting these expenditures from your gross revenue figure – congratulations! This represents your net profit (income). If you end up with a negative number, you have incurred a net loss.
Maximizing deductions to lower net taxable income
Taking advantage of various deductions can help reduce your taxable income, thereby increasing your net income. Here are some common deductions to consider:
1. Standard deduction: If you do not itemize your expenses, you can claim the standard deduction provided by the tax authorities.
2. Itemized deductions: These include expenses such as mortgage interest payments, medical and dental expenses (that exceed a certain threshold), state and local taxes paid (up to a certain limit), charitable donations, etc.
3. Retirement contributions: Contributions made towards retirement accounts such as 401(k)s or IRAs are generally tax-deductible up to specified limits.
4. Health savings account (HSA) contributions: HSA contributions made through pre-tax payroll deductions can effectively reduce your taxable income.
5. Education-related deductions: Certain education-related expenses like student loan interest payments or tuition fees may be eligible for tax deductions depending on specific criteria outlined by the tax authorities.
6. Home office deduction: Self-employed individuals who use part of their home exclusively for business purposes may qualify for a home office deduction based on applicable guidelines set forth by the Internal Revenue Service (IRS).
The impact of taxes on net income
Taxes have a substantial impact on an individual’s net Income since they directly affect how much money is left in one’s pocket after all necessary obligations are met. Understanding how taxes influence net Income is crucial for effective financial planning:
1. Progressive tax rates: Tax systems often employ progressive brackets where higher incomes are subject to higher marginal tax rates – meaning that as your gross Income increases, so does the percentage of it that goes towards taxes.
2. Deductions and credits: As mentioned earlier, taking advantage of various deductions and credits can significantly reduce your overall tax liability, resulting in more favorable outcomes for net Income calculations.
3.Tax-deferred investments: Contributions made to certain retirement accounts, such as traditional IRAs or 401(k)s, are tax-deductible in the year they are made. This reduces your taxable Income and can help increase net Income.
Net income and budgeting: Allocating funds effectively
Understanding your net income is crucial for effective budgeting. Having a clear picture of how much money you have available after all expenses and taxes allows you to allocate funds appropriately. Here’s how to use net income for effective budgeting:
1. Track expenses: Start by documenting all your monthly expenses, including fixed costs (rent/mortgage payments, utility bills) and variable costs (groceries, dining out, entertainment).
2. Prioritize essential expenses: Allocate a portion of your net income towards necessary expenditures such as housing, utilities, transportation, healthcare, debt repayment.
3. Establish savings goals: Set aside a percentage of your net income for short-term savings goals (e.g., emergency fund), long-term goals (e.g., retirement), and any other financial objectives you may have.
4. Plan discretionary spending: After accounting for essential expenses and saving goals, determine how much disposable income is left over for discretionary spending on non-essential items like vacations or entertainment.
Managing debt and its effect on net income
Debt can significantly impact an individual’s overall financial health if not managed properly. High levels of debt can decrease net Income due to interest payments that eat into one’s earnings each month. Therefore it is important to manage debt effectively:
1. Create a repayment plan: Develop a strategy for paying off high-interest debts first while making minimum payments on others until they can be fully addressed.
2. Consolidate loans: Consider consolidating multiple debts into one loan with more favorable terms such as lower interest rates or longer repayment periods.
3.Refinance existing debts : Refinancing existing loans might provide an opportunity to secure better terms based on improved creditworthiness or lower interest rates in the market.
4. Budget for debt repayment: Allocate a portion of your net income specifically towards repaying outstanding debts to ensure that they are being addressed consistently and effectively.
Net income and retirement planning: Saving for the future
Net income plays a critical role in retirement planning as it determines how much money you can set aside for your golden years. Here’s how to approach retirement planning with net Income in mind:
1. Determine your target savings rate: Experts often recommend saving 10-15% of your gross annual Income towards retirement. However, this percentage may vary depending on individual circumstances such as age, desired lifestyle, and existing savings.
2.Establish an emergency fund: Before focusing solely on retirement savings, build an emergency fund that covers at least three to six months’ worth of living expenses. This provides a safety net for unexpected events and expenses.
3.Contribute to employer-sponsored plans: Take advantage of workplace retirement plans such as 401(k)s if available, especially if there is an employer match option. These contributions are usually made pre-tax, reducing taxable Income while increasing net Income.
4.Explore Individual Retirement Accounts (IRAs): Consider opening Traditional or Roth IRAs (depending on eligibility) which offer unique tax advantages when saving for retirement.
5.Review and adjust periodically: Regularly review your progress towards reaching your retirement goals and make adjustments accordingly based on changes in personal circumstances or economic conditions.
Investing strategies to grow net income over time
Investing is a powerful tool that can help grow net income over time by generating passive returns. Here are some key investment strategies:
1.Diversify investments : Diversification involves spreading investments across different asset classes (stocks, bonds, real estate) to reduce risk exposure while maximizing potential returns.
2.Set long-term goals: Invest with a long-term perspective in mind since short-term market fluctuations should not dictate investment decisions.
3.Consider professional advice: Seek guidance from a financial advisor or investment professional to help navigate the complexities of investing and ensure that your portfolio aligns with your risk tolerance and goals.
4.Reinvest dividends: If you invest in dividend-paying stocks or funds, consider reinvesting those dividends into additional shares, compounding your potential returns over time.
5.Keep emotions in check: Avoid making impulsive investment decisions based on market volatility or short-term trends. Stick to a well-thought-out investment strategy based on sound research and analysis.
Net income and financial goal setting: Setting realistic targets
Setting realistic financial goals is crucial for effective money management. When it comes to net Income, understanding what is attainable within your means is key to successful goal setting:
1.Evaluate current net income: Review your current net Income to determine how much you can allocate towards various financial goals such as saving for a down payment on a house, paying off debts, or starting an emergency fund.
2.Set SMART goals: Make sure your goals are Specific, Measurable, Achievable, Relevant, and Time-bound. For example, instead of saying “I want to save more,” set a specific target like “I want to save $10,000 for a down payment on a house within two years.”
3.Break it down: Break larger long-term goals into smaller actionable steps that can be achieved incrementally. This helps track progress and provides motivation along the way.
4.Revisit and adjust regularly: Reevaluate your financial goals periodically (e.g., annually) based on changes in personal circumstances or economic conditions. Adjustments may be necessary due to unforeseen events or shifts in priorities.
Evaluating business expenses to optimize net income
For self-employed individuals or small business owners, carefully evaluating business expenses plays a critical role in optimizing net Income:
1.Track all business-related expenses meticulously throughout the year using accounting software or spreadsheets specifically designed for this purpose.
2.Categorize expenses: Group your business-related expenses into categories such as office supplies, travel and entertainment, marketing costs, professional fees, etc. This provides a clearer picture of where your money is being spent.
3.Evaluate each expense category: Regularly review each expense category to identify areas where costs can be reduced or eliminated without compromising the quality of your products or services.
4.Compare vendors and service providers: Shop around to find the best deals on necessary goods and services. Negotiate with suppliers or consider switching to more cost-effective alternatives if possible.
5.Automate processes: Implementing automation tools or outsourcing certain tasks can help streamline operations and reduce manual labor costs over time.
The role of side hustles in increasing net income
Side hustles have gained popularity in recent years as an effective way to boost net Income. A side hustle refers to any additional work undertaken outside of one’s primary job that generates extra income. Here are some considerations:
1.Identify marketable skills: Assess your skillset and interests to determine what type of side hustle aligns with your abilities and has earning potential.
2.Research opportunities: Investigate various side hustle options such as freelance writing, tutoring, graphic design, pet sitting/walking, ride-sharing/delivery services (e.g., UberEATS), online consulting etc., depending on your strengths and availability.
3.Manage time effectively: Ensure that taking on a side hustle does not interfere with existing commitments like family responsibilities or primary employment duties. Establish clear boundaries between work hours for both endeavors.
4.Market yourself strategically: Leverage online platforms (e.g., social media) or word-of-mouth referrals to promote your side hustle effectively within relevant networks or communities.
Net rental income: Tips for managing rental properties profitably
For individuals who own rental properties as a source of income:
1.Set competitive rent rates based on market research to attract tenants while ensuring a profit margin.
2.Regularly review rental agreements and consider incremental rent increases to keep up with inflation and market trends.
3.Maintain properties effectively to minimize repair costs over time. Promptly address any maintenance issues reported by tenants to prevent them from escalating into more significant problems.
4.Screen prospective tenants thoroughly to reduce the risk of late payments or property damage. Background checks, credit reports, and references can provide valuable insights during the tenant selection process.
5.Consider hiring a property management company if managing properties becomes overwhelming or unmanageable due to time constraints or lack of expertise.
Passive vs active sources of net income
Net Income can be generated through both passive and active sources:
1.Passive income: Passive income refers to money earned with minimal effort after an initial investment of time, money, or resources. Examples include rental properties generating monthly cash flow, dividends from investments in stocks or mutual funds, royalties from intellectual property (books, music), or earnings from peer-to-peer lending platforms.
2.Active income: Active income results from direct participation in work activities where you exchange your time and skills for compensation. This includes salaries earned through employment, wages received for services provided as a freelancer/self-employed individual/contractor etc.
Understanding the difference between these two types of Income is essential when evaluating potential revenue streams and planning for financial goals accordingly.
Impact of interest rates on net investment returns
Interest rates have a significant impact on investment returns and therefore influence net Income:
1.Bond markets: Changes in interest rates affect bond prices inversely – when interest rates rise, bond prices tend to fall. Therefore, if you hold bonds with fixed coupon rates while interest rates increase in the broader market, the value of your existing bonds may decline until they mature at face value.
2.Loan repayments: Rising interest rates increase borrowing costs since loans become more expensive due to higher interest charges. This affects net Income negatively as more money is allocated towards interest payments, leaving less for other purposes.
3.Savings accounts and fixed deposits: Higher interest rates can positively impact net Income by increasing returns on savings accounts or fixed deposit investments. This provides an opportunity to earn more from idle cash that may not be actively invested elsewhere.
Strategies for reducing expenses to boost personal net income
Reducing expenses is a practical way to increase personal net Income. Here are some strategies to consider:
1.Track spending habits: Monitor your monthly expenses carefully and identify areas where costs can be cut or eliminated.
2.Evaluate subscriptions and memberships: Review recurring subscriptions (e.g., streaming services, gym memberships) and cancel those you no longer use or find unnecessary.
3.Shop smartly: Compare prices before making purchases, look for discounts or sales, and consider buying generic brands instead of expensive name-brand products when quality is comparable.
4.Cook at home: Eating out frequently can add up quickly. Cooking meals at home allows you to control portion sizes, save money on ingredients, and potentially improve your overall health.
5.Reduce utility bills: Implement energy-saving measures like using LED light bulbs, unplugging electronics when not in use, conserving water through efficient fixtures/appliances etc., which help lower utility bills over time.
6.Consolidate debt: As mentioned earlier in the article, combining multiple debts into one loan with better terms can reduce monthly payments and save money on interest charges over time.
Analyzing trends in personal net incomes over time
Analyzing trends in personal net Incomes over time helps individuals understand their financial progress and make informed decisions about future goals. Here’s how you can analyze these trends effectively:
1.Gather historical data: Collect information on your net incomes from previous years. This could include tax returns or bank statements that outline your annual earnings after deductions/expenses have been accounted for.
2.Compare year-over-year changes: Calculate the percentage change between each year’s net Income to identify patterns or trends. This allows you to see how your earnings have grown or declined over time.
3.Identify factors driving changes: Analyze the underlying factors that contributed to any significant shifts in net Income, such as career advancements, job changes, investments, side hustles, or major life events (e.g., marriage, starting a family).
4.Consider external influences: Take into account broader economic conditions and industry-specific trends that may impact your personal net Income. For example, recessions can lead to wage stagnation or job losses across various sectors.
5.Set realistic expectations: Based on historical data and trend analysis, set realistic expectations for future net Incomes. Use this information to refine financial goals and adjust strategies accordingly.
Net farming or agricultural incomes and their unique considerations
Net farming income refers to the earnings generated from agricultural activities. Farming has its own unique considerations due to its dependence on variables like weather conditions, market demand for crops/livestock products etc. Here are some points to consider:
1.Expenses: Farming involves various expenses such as equipment maintenance/purchase/insurance costs/seeds/fertilizers/animal feed/veterinary care/labour/water/electricity etc., which should be accounted for when calculating net farm income.
2.Seasonal nature of agriculture