Insuring Your Future: A Comprehensive Guide to Coverage and Policies
Insurance Coverage and Policies: A Comprehensive Guide
Introduction
Insurance is a crucial aspect of personal finance. It provides individuals and families with financial protection against unexpected events, such as accidents, illnesses, or property damage. However, navigating the world of insurance can be complex and overwhelming due to the variety of coverage options and policies available in the market.
In this comprehensive guide, we will explore various types of insurance coverage and policies to help you understand their purpose, benefits, and how they can fit into your overall financial plan.
1. Health Insurance
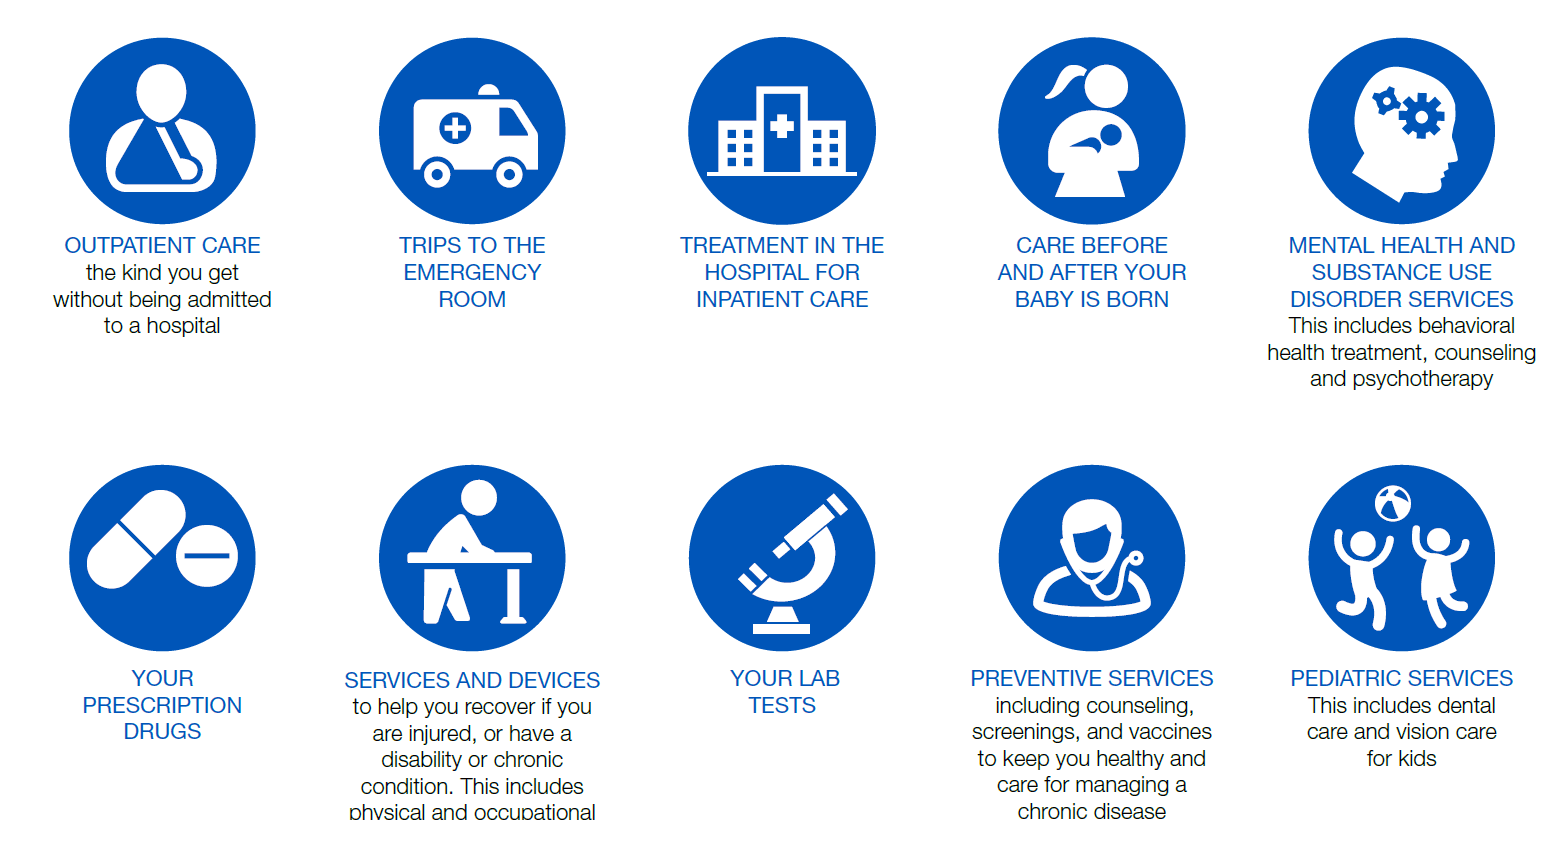
Health insurance is designed to cover medical expenses incurred by policyholders. It offers financial assistance for doctor visits, hospitalization costs, prescription medications, preventive care services, and more.
a) Employer-Sponsored Health Insurance: Many employers provide health insurance plans as part of their employee benefits package. These plans may have different levels of coverage options (e.g., HMOs or PPOs) and cost-sharing arrangements (e.g., deductibles or copayments).
b) Individual Health Insurance: If you’re self-employed or not covered by an employer-sponsored plan, individual health insurance allows you to purchase coverage directly from an insurer. The marketplace offers various plans with different premiums and deductibles based on your needs.
c) Medicare/Medicaid: Medicare is a federal program that provides health coverage for individuals who are 65 years old or older or those with certain disabilities. Medicaid is another government program that offers healthcare assistance to low-income individuals/families.
2. Auto Insurance
Auto insurance protects policyholders from financial loss due to vehicle-related accidents or damages caused by theft/vandalism.
a) Liability Coverage: This type of auto insurance pays for bodily injury or property damage suffered by someone else as a result of an accident where you are at fault.
b) Collision Coverage: Collision coverage helps cover repairs/replacement costs if your vehicle is damaged in an accident involving another vehicle/object.
c) Comprehensive Coverage: Comprehensive coverage protects against damage caused by incidents other than collisions, such as theft, vandalism, fire, or natural disasters.
d) Uninsured/Underinsured Motorist Coverage: This coverage safeguards you if you’re involved in an accident with a driver who has little or no insurance.
3. Homeowner’s Insurance
Homeowner’s insurance is essential for protecting your property and belongings from unexpected events like fire, theft, windstorms, or liability claims.
a) Dwelling Coverage: This covers the structure of your home in case of damage due to covered perils. It typically includes repairs/rebuilding costs.
b) Personal Property Coverage: Personal property coverage compensates for loss/damage to your belongings within the insured property. Special limits may apply to high-value items like jewelry or artwork.
c) Liability Coverage: Liability coverage provides financial protection if someone gets injured on your property and decides to sue you for damages.
d) Additional Living Expenses (ALE): ALE helps cover temporary living expenses if your home becomes uninhabitable due to a covered event (e.g., fire).
4. Life Insurance
Life insurance serves as financial protection for loved ones after the policyholder’s death. It offers a payout (death benefit) to designated beneficiaries upon the insured person’s passing.
a) Term Life Insurance: Term life insurance provides coverage for a specified period (e.g., 10-30 years). Premiums are generally lower but increase when renewing at the end of each term. If the policyholder outlives the term, there is no payout unless they convert it into permanent life insurance or purchase a new policy.
b) Whole Life Insurance: Whole life insurance offers lifelong coverage with premiums that remain constant throughout the policyholder’s lifetime. It also accumulates cash value over time which can be borrowed against or withdrawn under certain conditions.
c) Universal Life Insurance: Similar to whole life insurance, universal life insurance offers lifelong coverage. However, it provides more flexibility in terms of premium payments and death benefits.
5. Disability Insurance
Disability insurance protects policyholders by replacing a portion of their income if they become disabled and unable to work due to illness or injury.
a) Short-Term Disability Insurance: This type of coverage typically lasts for a few months (up to two years). It replaces a significant percentage (e.g., 60-70%) of the insured person’s income during the disability period.
b) Long-Term Disability Insurance: Long-term disability insurance kicks in after short-term disability coverage ends and can last until retirement age. It generally covers around 40-60% of the insured person’s pre-disability income.
Conclusion
Insurance is an essential component of personal finance that provides financial security when unexpected events occur. Understanding different types of insurance coverage and policies enables individuals and families to make informed decisions about protecting themselves from potential risks. Whether it’s health, auto, homeowner’s, life, or disability insurance, carefully assessing your needs and comparing various options will help you choose the most suitable coverage for your circumstances. Remember to review your policies periodically as life situations change – ensuring you have adequate protection throughout all stages of life.