Roth IRA vs Traditional IRA: Which Retirement Account Is Right for You?
When it comes to planning for retirement, one of the most important decisions you need to make is how to invest your money. One option that many people consider is an Individual Retirement Account (IRA). Within the realm of IRAs, there are two popular choices: Roth IRA and Traditional IRA. Each type has its own advantages and disadvantages, so it’s crucial to understand the differences between them before making a decision.
A Roth IRA is named after William V. Roth Jr., a former Senator from Delaware who sponsored the legislation that created this type of account in 1997. A Traditional IRA, on the other hand, has been around since 1974 when Congress first introduced this retirement savings vehicle.
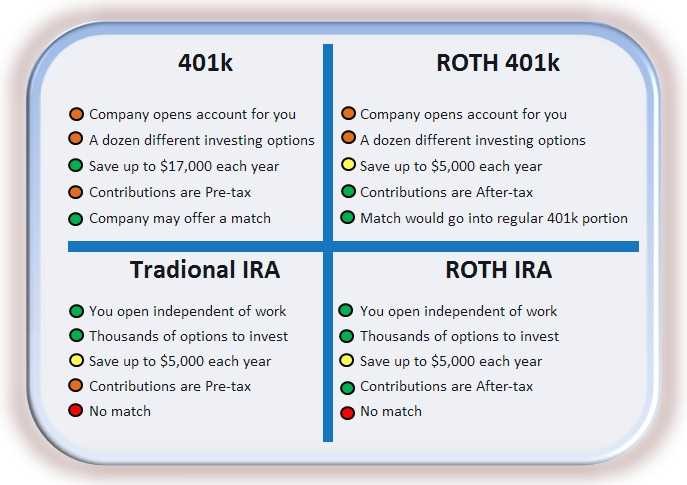
One of the key distinctions between a Roth IRA and Traditional IRA lies in how they are taxed. With a Traditional IRA, contributions are made with pre-tax dollars, meaning you can deduct these contributions from your taxable income for that year. This deduction can potentially reduce your tax liability and increase your current take-home pay. However, when you withdraw funds from your Traditional IRA during retirement, those withdrawals are subject to ordinary income tax rates at that time.
In contrast, contributions to a Roth IRA are made with after-tax dollars – meaning you don’t get any upfront tax deductions for contributing to this account. While this may seem like a disadvantage initially, the real benefit comes into play during retirement because qualified withdrawals from a Roth IRA are entirely tax-free. This means all the growth in your account over time can be withdrawn without paying any taxes on it.
Another important factor when deciding between a Roth or Traditional IRA is eligibility requirements and contribution limits. Both types have certain income restrictions imposed by the IRS which determine whether or not you can contribute directly to each account.
For instance, as of 2021 if you’re single or filing as head of household and have modified adjusted gross income (MAGI) above $140,000 ($208,000 for married couples filing jointly), you are not eligible to contribute directly to a Roth IRA. However, there are ways around this limitation through a technique called the “backdoor Roth IRA” where you make non-deductible contributions to a Traditional IRA and then convert it into a Roth IRA.
On the other hand, with a Traditional IRA, there is no income restriction for direct contributions. However, if you or your spouse are covered by an employer-sponsored retirement plan such as a 401(k) and have MAGI above certain limits ($66,000 – $76,000 for single filers in 2021; $105,000 – $125,000 for married couples filing jointly in 2021), your ability to deduct contributions from your taxes may be limited.
In terms of contribution limits, both types of IRAs have maximum annual amounts that can be contributed. As of 2021, the limit is $6,000 per year ($7,000 if age 50 or older) for both Roth and Traditional IRAs. These limits can change over time due to inflation adjustments set by the IRS.
When considering which type of account might be best for you, it’s essential to evaluate your current financial situation as well as your future goals. Here are some factors worth considering:
1. Current vs Future Tax Rates: If you believe that tax rates will increase in the future or expect to be in a higher tax bracket during retirement than you currently are now—consider contributing to a Roth IRA since withdrawals will be tax-free at retirement when taxes may potentially be higher.
2. Immediate Tax Benefits: If receiving immediate tax deductions is crucial for reducing your taxable income today and potentially increasing cash flow—contributing to a Traditional IRA might make more sense as these contributions can lower your taxable income now.
3. Required Minimum Distributions (RMDs): Keep in mind that starting at age 72 (or 70 ½ if you reached that age before January 1, 2020), Traditional IRA owners are required to take minimum distributions from their accounts annually. These withdrawals are taxed as ordinary income and can impact your tax liability during retirement. Roth IRAs have no RMDs during the account owner’s lifetime.
4. Investment Time Horizon: If you have a long time horizon until retirement and aim to maximize your investment growth potential, contributing to a Roth IRA might be more advantageous since all qualified withdrawals will be tax-free.
5. Estate Planning: For individuals who anticipate leaving an inheritance or want to pass on assets with minimal tax implications for their beneficiaries, a Roth IRA may provide flexibility as it allows for tax-free distributions when inherited by non-spouse beneficiaries.
6. Flexibility of Withdrawals: While it is generally not recommended to withdraw funds from retirement accounts before reaching age 59 ½ due to possible penalties, some circumstances may necessitate early access to funds. Contributions made directly (not earnings) to a Roth IRA can typically be withdrawn without paying taxes or penalties at any time for any reason—a feature that provides flexibility compared to Traditional IRAs.
Ultimately, the decision between a Roth IRA and Traditional IRA depends on several factors unique to each individual’s financial situation and goals. It is advisable to speak with a financial advisor or tax professional who can assess your specific circumstances and help guide you towards the most suitable choice.
It’s important also not just focus only on one type of account; diversification in retirement savings is often recommended. Hence, it might be wise for some individuals to consider having both types of IRAs—contributing simultaneously or switching contribution strategies based on changes in personal finance situations over time.
Regardless of which option you choose, starting early and consistently contributing towards your retirement savings will always put you in a better position down the road when it comes time for enjoying those golden years comfortably.