Maximize Your Savings with the Right CD Rate
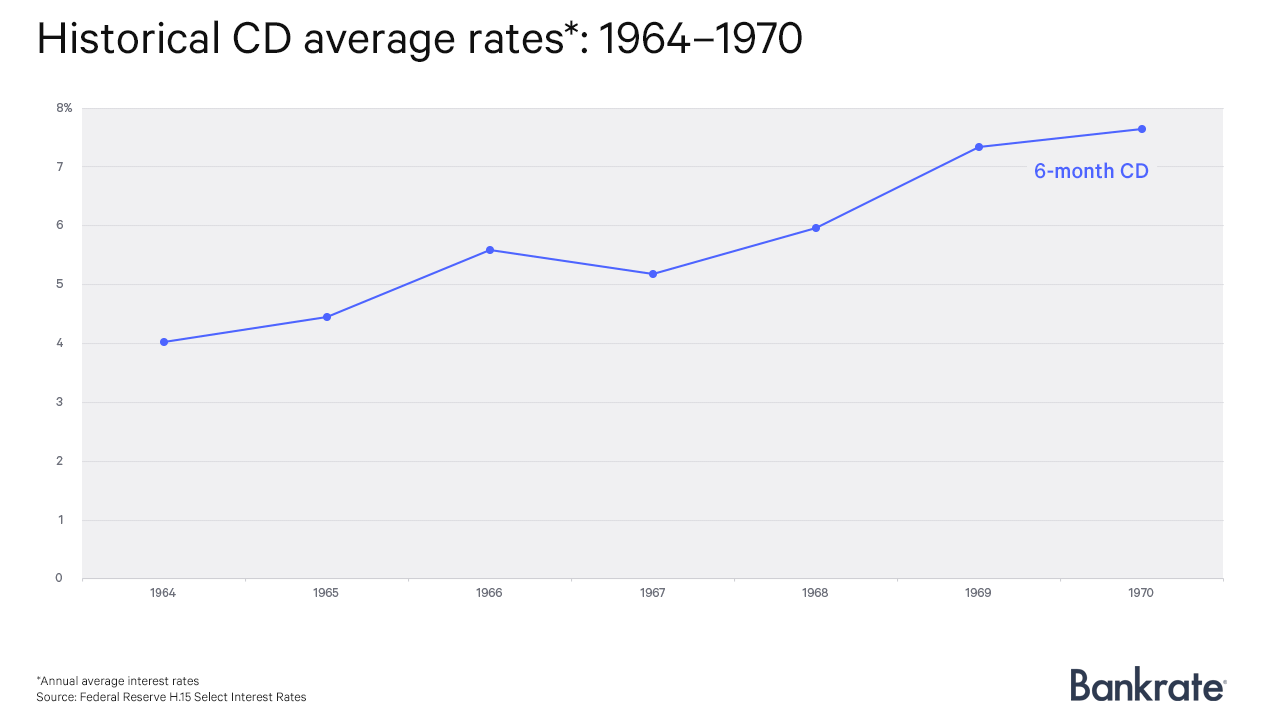
When it comes to saving money, finding the right investment option is crucial. Certificate of Deposit (CD) rates can offer a stable and secure way to grow your savings over time. CDs are popular among investors who prioritize safety and guaranteed returns.
So, what exactly is a CD? A CD is a type of time deposit offered by banks and credit unions. It works like this: you deposit a specific amount of money for a set period of time, known as the term length. During this period, your funds earn interest at an agreed-upon rate.
Now that we understand the basics let’s dive into CD rates. The rates on CDs can vary depending on several factors including market conditions, the institution offering them, and the term length you choose.
1. Short-term CDs: If you’re looking for flexibility or have immediate financial goals in mind, short-term CDs might be ideal for you. These typically have terms ranging from three months to one year but may offer lower interest rates compared to longer-term options.
2. Medium-term CDs: For those with medium-range financial goals such as saving for a down payment or planning for education expenses in a few years, medium-term CDs could be suitable. Terms usually range from one to five years with higher interest rates than short-term options.
3. Long-term CDs: Long-term CDs are perfect if you are looking to save for retirement or other long-range goals where your funds can be tied up for an extended period without any immediate need for liquidity. Terms can span anywhere from five to ten years or even longer depending on the institution.
Keep in mind that longer terms often offer higher interest rates due to the commitment involved since banks benefit from having access to your funds over an extended period.
While knowing the different types of CD terms is important when considering which option fits best with your financial objectives, it’s also essential to compare rates across various institutions before making a decision.
Online banks tend to offer higher CD rates compared to traditional brick-and-mortar banks due to their lower overhead costs. It’s worth exploring options from online-only banks and credit unions, as they often provide competitive rates.
Another important aspect to consider is the annual percentage yield (APY). The APY takes into account compounding interest, which means your money will earn interest on top of previous interest earnings. Be sure to compare APYs rather than just the stated interest rates when evaluating different CDs.
Lastly, remember that CDs are not liquid investments. Withdrawing funds before the end of the term can result in penalties, such as forfeiting a portion of the earned interest. Therefore, if you anticipate needing quick access to your savings or might require flexibility with your funds, it may be wise to explore other investment options.
In conclusion, Certificate of Deposit rates play a significant role in determining how much return you can earn on your savings over time. Understanding the different types of CDs and comparing rates across various institutions can help you make an informed decision about where to invest your hard-earned money. Whether you’re saving for a short-term goal or planning for retirement, finding a suitable CD rate is essential for maximizing your financial growth while ensuring peace of mind through guaranteed returns.