Unlocking the Secrets of Interest: Mastering Borrowing and Investing for Financial Success
Interest from loans and mortgages is a crucial aspect of personal finance that affects individuals and families in various ways. Whether it’s purchasing a new home, buying a car, or funding education, many people rely on loans to fulfill their financial goals. However, understanding how interest works is essential to make informed decisions and avoid unnecessary debt burdens.
To grasp the concept of interest, we must first understand its definition. Interest is essentially the cost of borrowing money. When you take out a loan or mortgage, the lender charges you an additional amount over the principal borrowed. This extra amount compensates them for lending you money and serves as their profit.
The interest rate is expressed as a percentage of the loan amount and determines how much borrowers have to repay in addition to the original sum borrowed. For example, if you borrow $10,000 at an annual interest rate of 5%, you would have to pay back $10,500 after one year ($10,000 + 5% = $10,500). The interest payment increases with time since it accumulates based on the outstanding balance.
There are two main types of interest: simple interest and compound interest.
Simple Interest:
Simple interest is calculated solely on the initial principal amount borrowed or invested. It doesn’t consider any previous accumulated interests during subsequent periods. This type of interest calculation is commonly used for short-term loans or investments without compounding intervals.
To calculate simple interest:
I = P * r * t
Where:
I = Simple Interest
P = Principal (initial loan/investment amount)
r = Annual Interest Rate (expressed as a decimal)
t = Time Period (in years)
For example, if you invest $1,000 at an annual simple interest rate of 3% for two years:
I = 1000 * 0.03 * 2
= $60
After two years, your investment would yield $60 in simple interest.
Compound Interest:
Compound interest is more commonly used for long-term loans, mortgages, and investments. Unlike simple interest, compound interest takes into account the accumulated interests from previous periods. This compounding effect allows your money to grow at an accelerated rate over time.
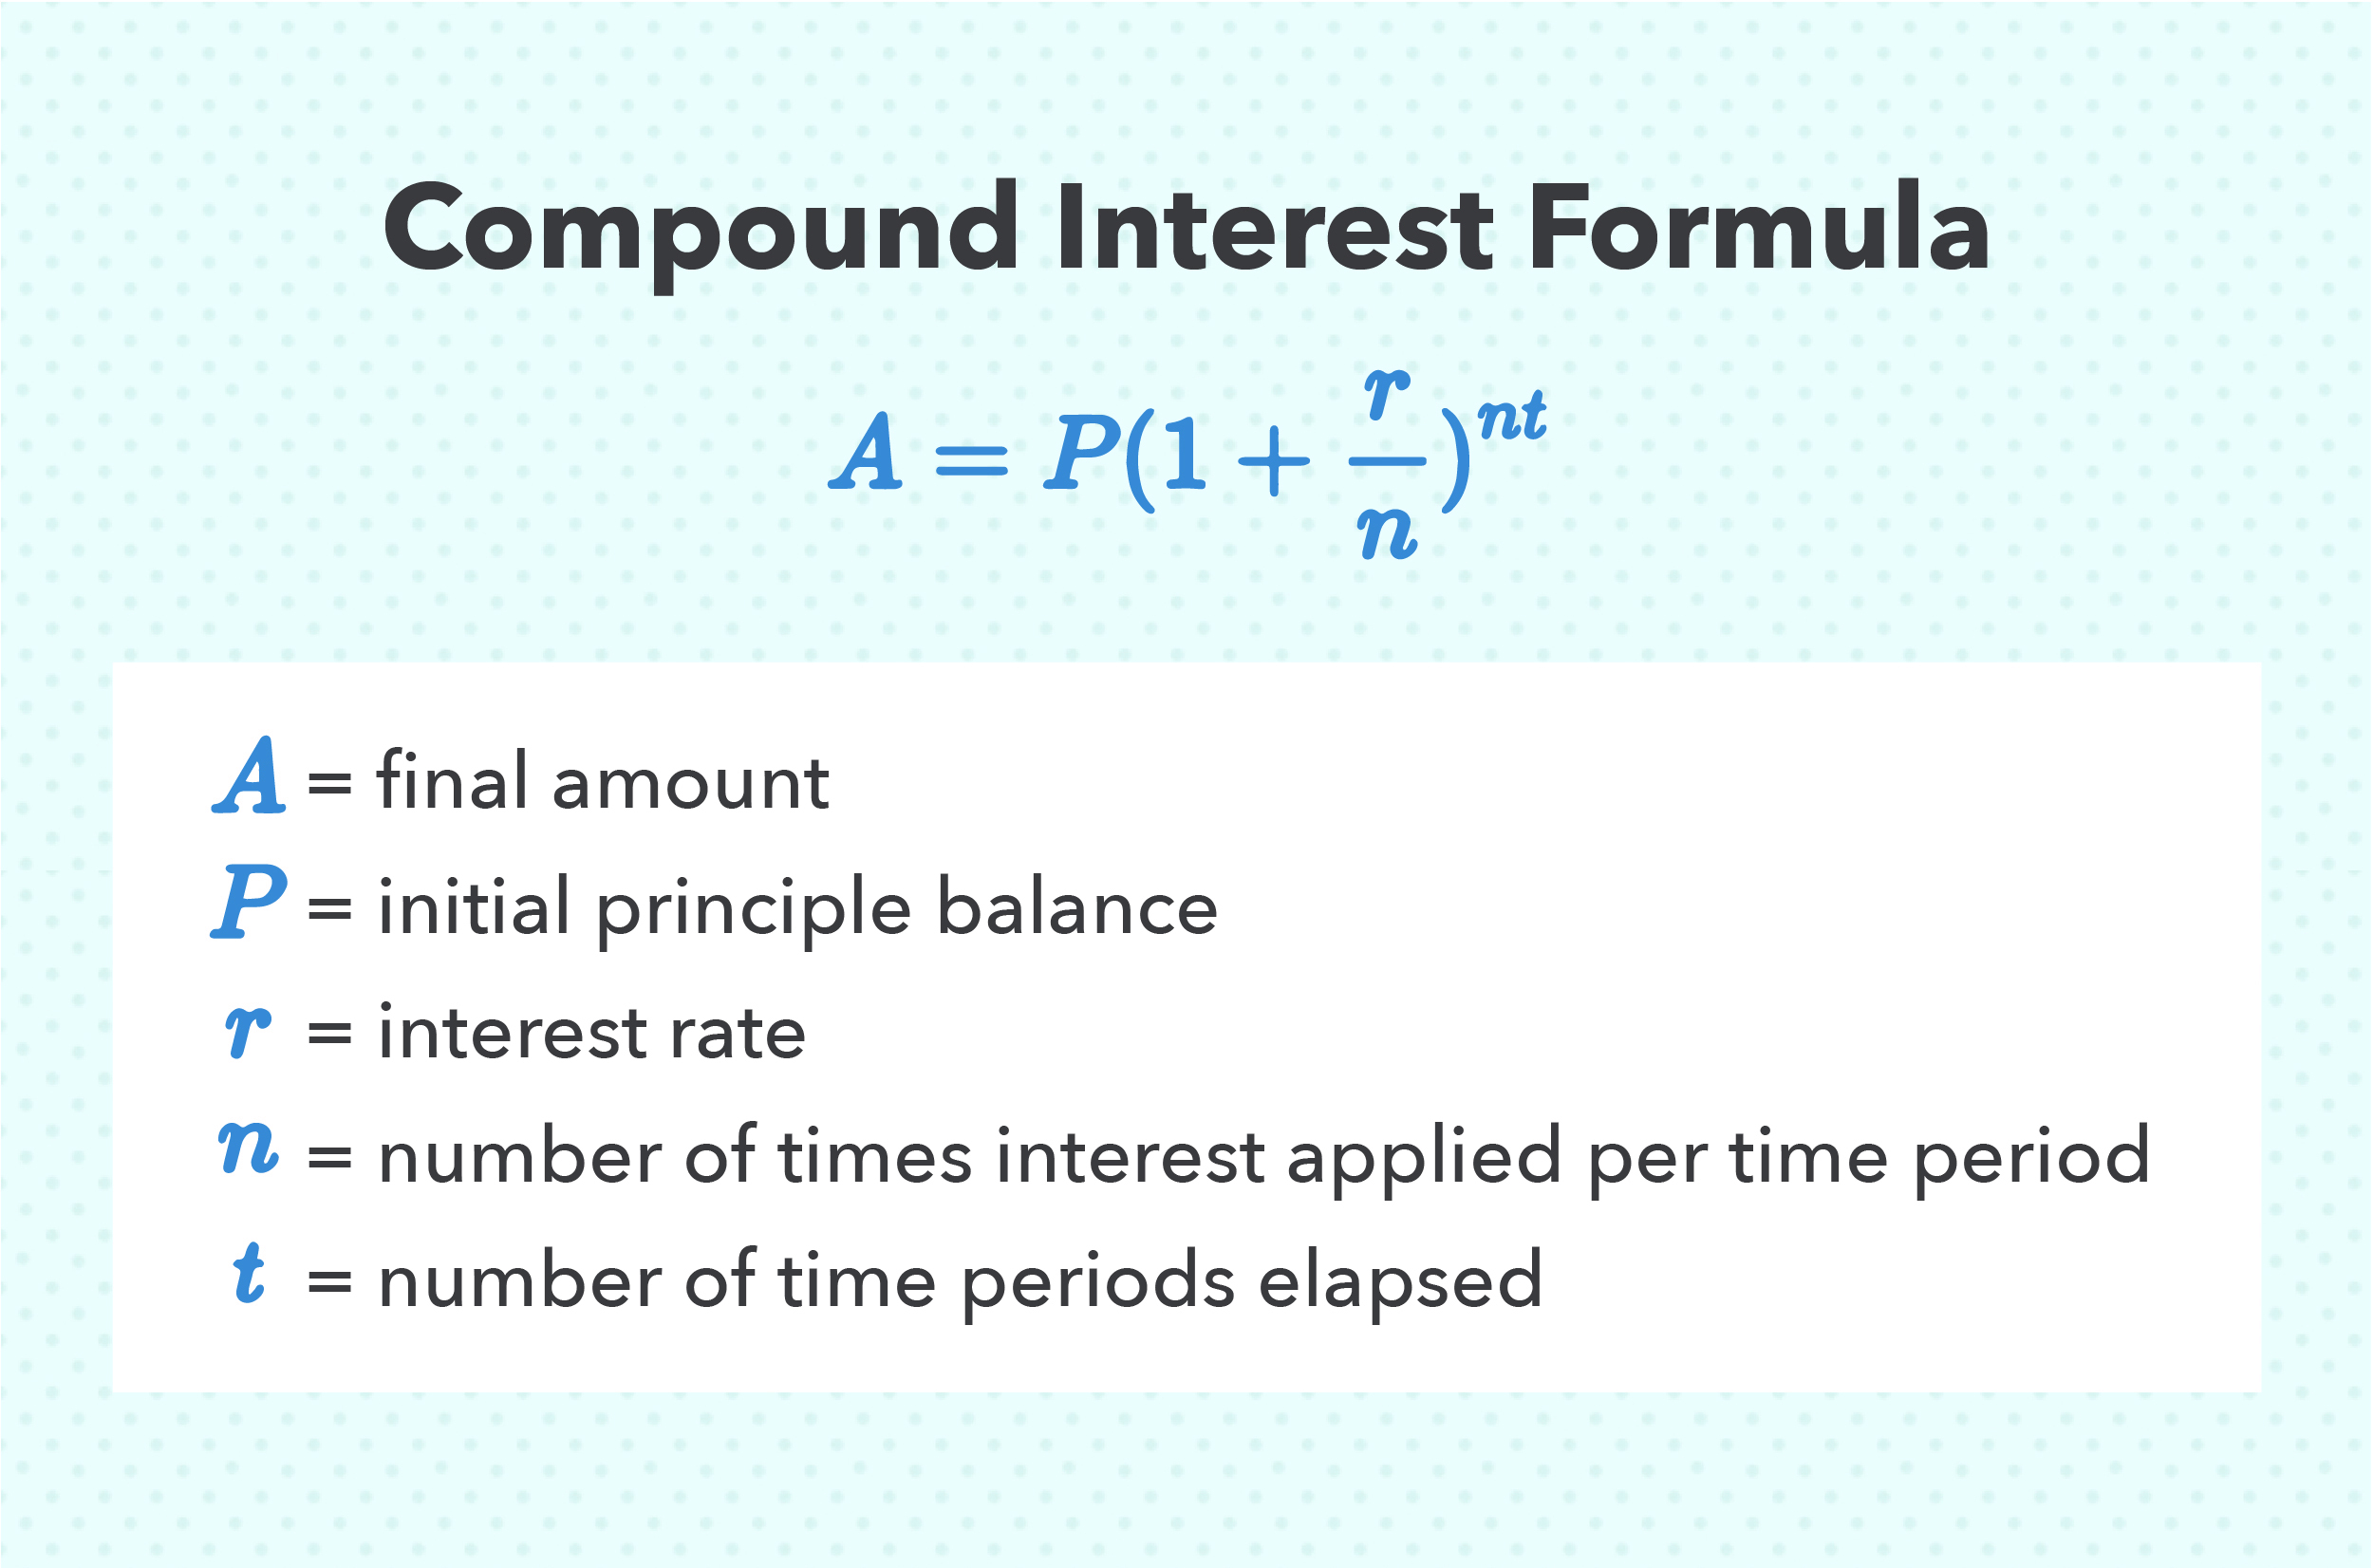
The formula to calculate compound interest is:
A = P * (1 + r/n)^(n*t)
Where:
A = Total Amount after t years
P = Principal (initial loan/investment amount)
r = Annual Interest Rate (expressed as a decimal)
n = Compounding Intervals per year
t = Time Period (in years)
For example, if you deposit $1,000 in a savings account with a 5% annual compound interest rate compounded quarterly for three years:
A = 1000 * (1 + 0.05/4)^(4*3)
= $1157.63
After three years, your initial investment would grow to $1157.63 due to the compounding of interest.
Understanding how compound interest works can be beneficial when taking out loans or mortgages. On one hand, it demonstrates the potential growth of investments over time; on the other hand, it highlights the importance of repaying debts promptly.
When borrowing money through a mortgage or loan, it’s crucial to consider not only the principal amount but also the total cost of borrowing – which includes both principal and accumulated interest payments over time. By comparing different offers and understanding how compounding affects repayment amounts, individuals can make informed decisions about their financial commitments.
Moreover, borrowers should pay attention to different types of mortgage or loan structures that may influence their overall debt burden. For instance, adjustable-rate mortgages often come with lower initial rates but can increase significantly over time due to market fluctuations. Fixed-rate mortgages provide stable monthly payments throughout the loan term but may have higher initial rates compared to adjustable-rate options.
Additionally, borrowers should aim to improve their creditworthiness to negotiate lower interest rates. Lenders assess credit scores, income stability, and debt-to-income ratios when determining the interest rate for a loan. By maintaining a good credit score and reducing existing debts, borrowers can increase their chances of qualifying for better rates.
In conclusion, understanding how interest works is crucial in navigating loans and mortgages effectively. Whether it’s simple or compound interest, individuals must consider the total cost of borrowing when making financial decisions. By comparing different offers, considering various loan structures, and improving creditworthiness, borrowers can reduce their overall debt burden and achieve their desired financial goals more efficiently.